
In the rapidly evolving landscape of digital finance, understanding the intricacies of your financial tools is paramount. One seemingly simple piece of information, your debit card’s billing address, plays a crucial role in countless transactions, from online shopping to subscription services, and is a cornerstone of your financial security. While often taken for granted, knowing how to quickly and accurately check this address can save you from failed transactions, potential fraud, and unnecessary headaches. This article delves into why your billing address is so important, the various methods to verify it, situations where it’s most needed, and best practices for managing this vital piece of your financial identity.
Why Your Billing Address Matters More Than You Think
The billing address associated with your debit card is far more than just a mailing address; it’s a critical security feature and a key piece of information that facilitates successful financial transactions. Understanding its significance is the first step toward managing your debit card effectively and safeguarding your finances.
Ensuring Successful Transactions
When you make a purchase online or sign up for a service, merchants often use the Address Verification System (AVS) as a fraud prevention tool. AVS compares the billing address provided by the customer at checkout with the address on file with the card issuer (your bank). If there’s a mismatch, even a minor discrepancy, the transaction may be declined. This security measure is designed to protect both the consumer and the merchant from unauthorized use of a card. For consumers, a correct billing address ensures that your legitimate purchases go through without a hitch, preventing frustration and delays. For merchants, it reduces the risk of chargebacks and losses due due to fraudulent activity.
Preventing Fraud and Identity Theft
The billing address acts as a layer of authentication. If a fraudulent user attempts to use your debit card, they might have your card number and expiration date, but they often won’t have the correct billing address. By requiring this information, banks and merchants add a significant barrier to unauthorized transactions. This makes it harder for criminals to exploit stolen card details, even if they manage to compromise your card number. Maintaining an accurate and up-to-date billing address is therefore a proactive step in protecting yourself from identity theft and financial fraud. It’s a simple yet effective tool in your overall financial security arsenal.
Account Verification and Security Protocols
Beyond individual transactions, your billing address is frequently used for general account verification purposes. If you need to contact your bank about unusual activity, update your account information, or dispute a charge, you’ll often be asked to confirm your billing address as part of their security protocols. This helps the bank ensure they are speaking with the legitimate cardholder and not an impostor. Furthermore, many financial institutions use your primary billing address as the default mailing address for statements, notices, and new card deliveries. Ensuring this address is correct is vital for receiving important communications about your account and maintaining visibility over your financial health.
Common Ways to Find Your Debit Card Billing Address
Fortunately, checking your debit card’s billing address is a straightforward process, thanks to various accessible financial tools and services. Here are the most reliable methods to locate this essential information.
Utilizing Online Banking Portals
In today’s digital age, your bank’s online banking portal or mobile app is often the easiest and fastest way to access your account details. Once you log in, navigate to the section that displays your personal information, account settings, or profile. Here, you should find your mailing address, which is typically your billing address. Most banks provide a clear overview of the personal details they have on file, including your current address. If you’ve moved recently and haven’t updated it, this is also where you would typically initiate an address change. This method offers instant access and is available 24/7.
Reviewing Physical or Digital Bank Statements
Your monthly bank statements, whether delivered physically via mail or digitally through your online banking portal, prominently display your billing address. Look for your name and address printed at the top of the statement. This is the address your bank has on record and the one associated with your debit card. If you receive paper statements, simply pull out your latest one. For digital statements, log into your online banking, navigate to the “Statements” or “eDocuments” section, and download a recent statement. This method provides a historical record and confirms the address that was valid at the time the statement was issued.
Contacting Your Bank’s Customer Service
If you’re unable to find your billing address through online banking or statements, or if you prefer direct assistance, calling your bank’s customer service department is a reliable option. Locate the customer service number on the back of your debit card or on your bank’s official website. Be prepared to verify your identity by providing personal information such as your account number, date of birth, or the last four digits of your Social Security number. Once your identity is confirmed, the representative can immediately tell you the billing address on file and assist with any necessary updates.
Checking Previous Purchase Receipts (Limited Use)
While not a primary method, some older physical receipts from in-store purchases might occasionally print a partial billing address or zip code. Online purchase confirmations might also include the shipping address you used, which often matches your billing address if you haven’t specified otherwise. However, this method is less reliable as many receipts do not display full billing details for security reasons, and it only confirms the address used for that specific transaction, not necessarily the current one on file with your bank. Use this as a last resort or supplementary check, but always confirm with your bank for accuracy.
Situations Where You Might Need Your Billing Address
Knowing where and how to find your debit card’s billing address is one thing; understanding when you’ll need it is equally important. This information is frequently requested in various financial and transactional contexts.
Making Online Purchases and Subscriptions
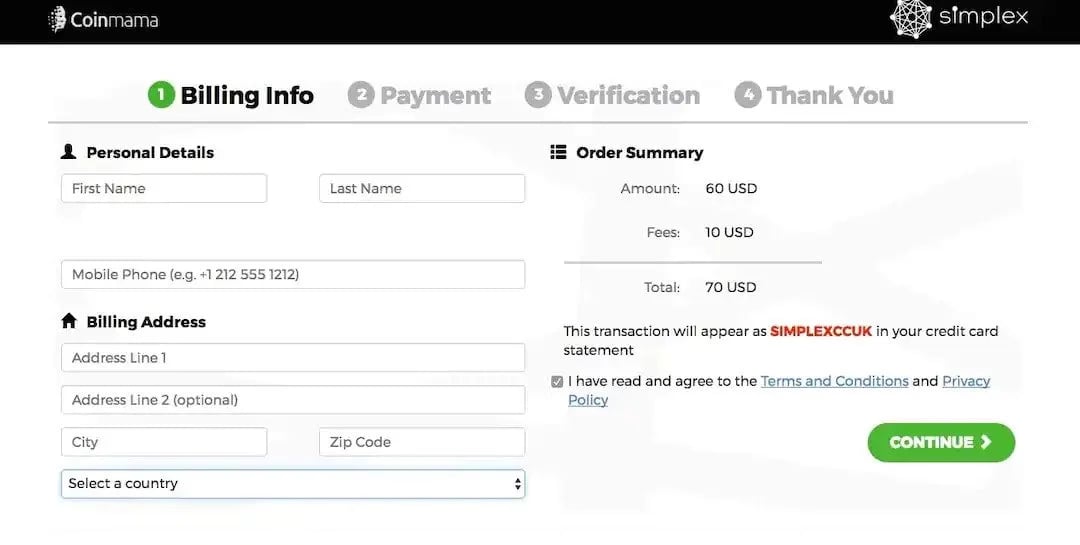
The most common scenario requiring your billing address is during online shopping or signing up for digital subscriptions. As mentioned, merchants often use AVS to verify the address you enter against the one registered with your bank. If these don’t match exactly, your transaction might be declined, leading to frustration and delays. Always ensure the billing address you provide on e-commerce sites is identical to the one on file with your bank, even down to minor details like street suffixes (e.g., “Street” vs. “St.”).
Updating Personal Information with Merchants
When you move or change your address, it’s not enough to update it with your bank; you also need to update it with any merchants, subscription services, or utility providers that have your debit card details on file. If your old billing address is still associated with your card on their system, future recurring payments might fail due to an AVS mismatch. Proactively updating this information ensures uninterrupted service and smooth transactions.

Disputing Transactions or Reporting Fraud
In the unfortunate event that you need to dispute a fraudulent charge or report unauthorized activity on your debit card, your bank will invariably ask for your billing address to verify your identity. This is part of their security protocol to confirm they are speaking with the legitimate cardholder before discussing sensitive account details or initiating investigations. Having this information readily available will expedite the process of resolving financial discrepancies.
Setting Up New Financial Accounts
When opening new bank accounts, credit card accounts, or even applying for loans, you’ll be required to provide your current billing address. This information is crucial for identity verification, regulatory compliance (Know Your Customer – KYC), and for ensuring all official correspondence reaches you. An accurate billing address is a foundational piece of information for any new financial relationship.
Troubleshooting Billing Address Issues
Despite your best efforts, sometimes issues arise with billing addresses that can lead to declined transactions or other financial inconveniences. Understanding how to troubleshoot these problems is key to maintaining smooth financial operations.
Understanding Address Mismatches
An address mismatch occurs when the billing address you provide during a transaction does not exactly match the address your bank has on file for your debit card. Common reasons for mismatches include:
-
Recent Moves: You’ve moved but haven’t updated your address with your bank.
-
Typographical Errors: A simple typo during online checkout (e.g., “Main St.” instead of “Main Street”).
-
Outdated Merchant Information: A merchant still has an old address for you, even if your bank’s record is current.
-
Confusing Shipping vs. Billing: Accidentally entering your shipping address as your billing address.
-
Bank Data Entry Errors: Though rare, your bank might have an incorrect address on file due to an administrative error.
When a transaction is declined due to an AVS mismatch, your bank statement might show a pending authorization for the amount, which will eventually drop off. It’s important to rectify the address rather than repeatedly attempting the transaction, as this can sometimes trigger further security alerts.
How to Update Your Billing Address with Your Bank
If you identify that your billing address is incorrect or outdated, updating it with your bank should be your top priority. Most banks offer several convenient ways to do this:
-
Online Banking Portal/Mobile App: Log in and navigate to your profile or personal information section. You should find an option to edit your address. This typically requires a verification step, such as entering a code sent to your phone or email.
-
By Phone: Call your bank’s customer service. After verifying your identity, the representative can update your address. They may send a confirmation letter to your new address.
-
In Person: Visit a local branch of your bank. A teller or customer service representative can assist you with the address change, often requiring a valid ID and proof of new address (e.g., utility bill).
-
By Mail: Some banks still allow address changes via mail, usually by sending a signed form. Check your bank’s website for specific instructions.
Always confirm that the update has been processed correctly, either by checking your online profile a few days later or by requesting a confirmation.
Resolving Issues with Merchants
Even after updating your address with your bank, you might encounter issues with specific merchants. This typically happens because the merchant’s system still retains your old address. To resolve this:
-
Update Your Profile: Log into your account with the merchant and update your billing address in their system. This is crucial for recurring payments or saved card details.
-
Re-enter Card Details: For one-time purchases, simply re-enter your debit card details and ensure you type in the correct, updated billing address manually.
-
Contact Merchant Support: If issues persist, contact the merchant’s customer support. They might need to manually refresh your billing information or troubleshoot an underlying system issue.
Being proactive and thorough in updating your address across all relevant platforms will prevent future transaction failures.
Best Practices for Managing Your Billing Information
Effective management of your billing address goes hand-in-hand with sound personal finance practices. Adhering to these best practices will enhance your financial security and streamline your transactions.
Regularly Verify Your Account Details
Make it a habit to periodically review your personal information on file with your bank, especially your billing address. A quick check of your online banking profile or a recent statement once every few months, or whenever you perform an annual financial review, can catch discrepancies before they cause problems. This proactive approach ensures all your financial data is accurate and up-to-date.
Implement Strong Security Measures
Your billing address, combined with your name and card number, is sensitive information. Always use strong, unique passwords for your online banking accounts and merchant profiles. Enable two-factor authentication (2FA) wherever possible. Be wary of phishing attempts or unsolicited requests for your personal information. Only provide your billing address on secure, encrypted websites (look for “https://” and a padlock icon in the browser bar). Protecting the access points to your financial information indirectly protects your billing address from unauthorized exposure.
Keep Records of Address Changes
Whenever you change your address, keep a record of the date you updated it with your bank and any other key financial institutions or merchants. This documentation can be invaluable if you encounter a transaction issue later and need to demonstrate when and where you updated your information. A simple spreadsheet or a dedicated folder for financial records can serve this purpose.
Protecting Your Personal Information
Beyond the billing address itself, protect all your personal identifying information (PII). Be cautious about sharing your full address publicly or with unverified sources. Shred old bank statements and documents containing your address before discarding them. The less accessible your personal information is to potential fraudsters, the lower your risk of identity theft and unauthorized debit card use.
In conclusion, the billing address linked to your debit card is a quiet but powerful guardian of your financial transactions and security. By understanding its importance, knowing how to easily check and update it, and adopting best practices for its management, you empower yourself to navigate the digital financial world with confidence and peace of mind. Regular vigilance and accurate information are your strongest allies in maintaining seamless financial operations and safeguarding your assets.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.