
For many, tax season is a period of stress, but for the financially savvy, it is an opportunity to reclaim capital, optimize cash flow, and secure personal data. The question of “how soon” one can file is not merely about the date the Internal Revenue Service (IRS) begins accepting returns; it is a strategic consideration involving document readiness, legislative updates, and the nuances of individual financial portfolios.
Filing your taxes early can offer significant psychological and financial relief. However, rushing the process without the necessary preparation can lead to errors, audits, and the dreaded necessity of filing an amended return. To navigate this period effectively, one must understand the intersection of IRS timelines, employer obligations, and personal financial record-keeping.

Understanding the IRS Tax Season Timeline
The official start of the tax filing season is dictated by the IRS, usually falling in the latter half of January. While the tax year ends on December 31st, the agency requires several weeks to update its systems, integrate new tax law changes, and perform rigorous testing on its e-file platforms.
The Official Launch Date
Typically, the IRS announces the official opening date in early January. In most years, this date falls between January 20th and January 31st. Once the “switch is flipped,” the IRS begins processing electronic returns and issuing confirmation receipts. It is important to note that many tax software providers allow users to prepare their returns and hit “submit” as early as the first week of January. In these cases, the software holds the return in a secure queue and transmits it automatically the moment the IRS systems open.
The Employer and Provider Deadlines
Even if the IRS is ready on January 20th, you can only file as soon as you have your documentation. Federal law requires employers to send out W-2 forms and certain 1099 forms by January 31st. This means that for the average W-2 employee, the real “start date” for taxes is the arrival of that final document in the mail or secure portal. If you are an independent contractor or have diverse investment income, your timeline may be pushed further back, as some brokerage firms do not issue 1099-B forms until mid-February or even early March.
The Impact of the PATH Act
For those who claim the Earned Income Tax Credit (EITC) or the Additional Child Tax Credit (ACTC), filing “early” does not necessarily mean an early refund. Under the Protecting Americans from Tax Hikes (PATH) Act, the IRS is legally prohibited from issuing refunds for returns claiming these credits before mid-February. This delay is designed to give the agency more time to detect and prevent fraudulent claims. Therefore, while you can file in January, you should manage your liquidity expectations accordingly.
The Strategic Advantages of Filing Early
Filing as soon as humanly possible is more than just an exercise in punctuality; it is a defensive and offensive financial maneuver. From mitigating the risk of fraud to accelerating your personal “cost of capital,” the benefits of early filing are multifaceted.
Faster Refunds and Cash Flow Management
The most obvious benefit of early filing is the prompt delivery of your tax refund. For many households, the tax refund is the single largest “windfall” of the year. Receiving these funds in early February rather than late April allows for immediate debt reduction, contributions to high-yield savings accounts, or the funding of an Individual Retirement Account (IRA) for the current year. By filing early, you are essentially shortening the duration of the interest-free loan you have provided to the government.
Protecting Against Identity Theft
Tax-related identity theft remains a significant concern. Scammers often use stolen Social Security numbers to file fraudulent returns early in the season, claiming massive refunds before the legitimate taxpayer even sits down at their computer. The IRS system operates on a “first-come, first-served” basis regarding Social Security numbers. If you file your legitimate return first, any subsequent fraudulent attempt using your information will be automatically rejected. In this context, filing early is one of the most effective security measures you can take.
Ample Time to Plan for Owed Taxes
If your calculations reveal that you actually owe the government money, filing early is still beneficial. Filing your return in January does not mean you have to pay in January. You can submit your return, lock in your figures, and schedule your payment for the actual deadline in mid-April. This provides you with several months to adjust your budget, move funds from investments, or save the necessary cash, preventing the “sticker shock” that often leads to high-interest credit card debt when taxpayers wait until the last minute to calculate their liability.
Essential Paperwork: What You Need Before You Start
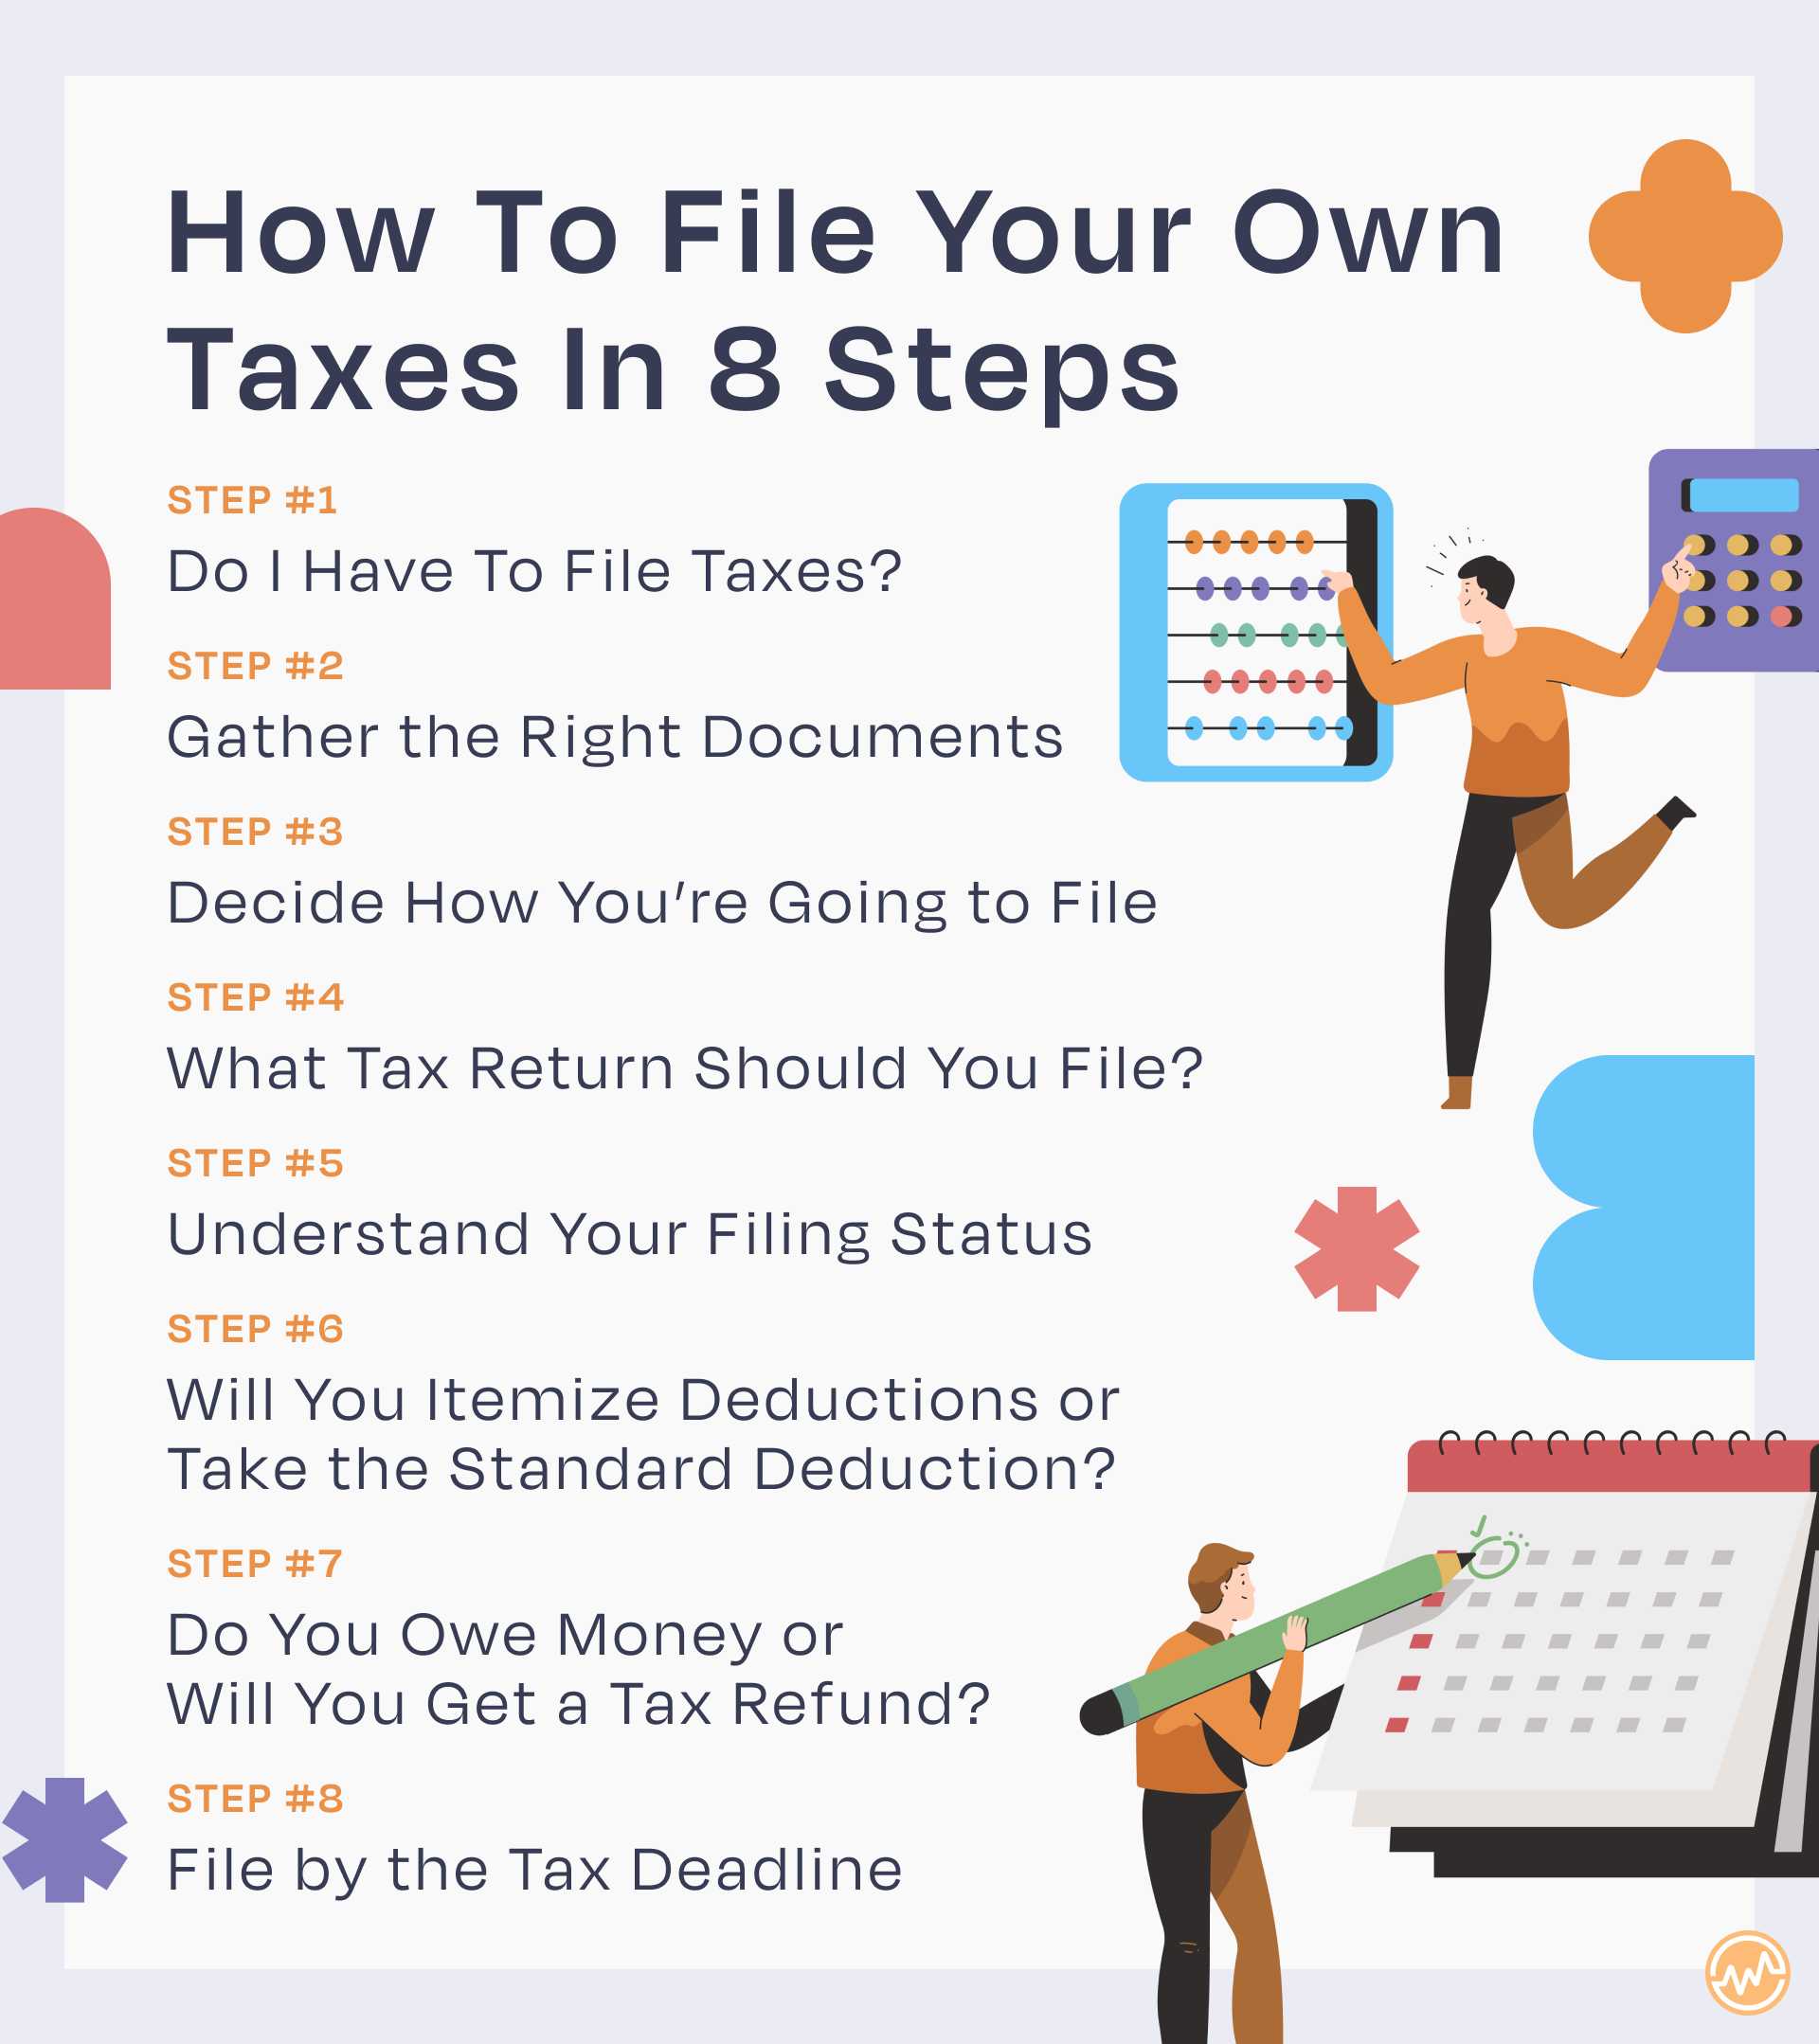
The bottleneck in early filing is almost always documentation. To file accurately, you must move beyond estimates and rely on finalized forms. Attempting to file using a final paystub rather than a W-2 is a common mistake that often results in discrepancies and IRS inquiries.
Income Records and Statements
Before you begin, ensure you have gathered every relevant income document. This includes:
-
W-2s: From every employer you worked for during the calendar year.
-
1099-NEC/MISC: For freelance work or side hustles.
-
1099-INT and 1099-DIV: For interest and dividends earned from bank accounts and brokerage firms.
-
1099-K: Now increasingly important for those receiving payments via apps like Venmo, PayPal, or Cash App for business goods and services.
Deductions and Credits
If you plan to itemize deductions rather than taking the standard deduction, your documentation needs increase exponentially. You will need records of mortgage interest (Form 1098), property taxes, charitable donation receipts, and unreimbursed medical expenses. Even if you take the standard deduction, you may be eligible for “above-the-line” deductions, such as student loan interest or educator expenses, which require their own set of supporting documents.
Investment and Cryptocurrency Considerations
The rise of digital assets has complicated the “how soon” question. Cryptocurrency exchanges are notorious for providing tax documents later than traditional banks. Furthermore, if you traded frequently, you must ensure your cost-basis tracking is accurate across all platforms. Filing before your brokerage issues a corrected 1099-B is a frequent source of error for active investors; often, these firms issue an initial statement in February and a “corrected” version in March. If you have significant investment activity, “early” might mean early March rather than January.
Tools and Resources for a Seamless Filing Experience
The modern financial landscape offers a variety of tools that make early filing more accessible. Whether you choose a DIY software approach or professional consultation, the goal is to leverage technology to ensure accuracy and speed.
Tax Software vs. Professional Accountants
For individuals with straightforward income (a single W-2 and standard deductions), modern tax software is highly efficient. These platforms use “interview-style” formats that guide you through the process, often importing data directly from employers and financial institutions. However, for business owners, high-net-worth individuals, or those with complex international tax obligations, a Certified Public Accountant (CPA) is invaluable. While software is fast, a professional can provide strategic advice on depreciation, tax-loss harvesting, and future-year planning that an algorithm might overlook.
IRS Free File and Electronic Filing
The IRS Free File program provides free brand-name tax software to taxpayers whose adjusted gross income (AGI) falls below a certain threshold (usually around $79,000). Utilizing this or other e-file options is the only way to ensure the fastest possible processing. Paper returns can take six to eight weeks—or longer—to process, whereas e-filed returns with direct deposit are typically processed within 21 days.
The Importance of Direct Deposit
When filing early, the method of refund delivery is just as important as the filing date. Opting for a paper check in the mail adds unnecessary transit time and risk of theft. By providing your routing and account numbers, you ensure that the moment the IRS clears your return, the funds are electronically transferred into your account.
Common Pitfalls of Rushing the Process
While there are many reasons to file early, there is a distinct difference between being “efficient” and being “hasty.” Rushing to file without a complete financial picture can result in consequences that far outweigh the benefits of a quick refund.
The Risk of Amended Returns
If you file your taxes on January 25th and receive a stray 1099-DIV in the mail on February 10th, you cannot simply “ignore” it. You will likely need to file Form 1040-X, the Amended U.S. Individual Income Tax Return. Amended returns are processed manually and can take up to 16 weeks—or more—to resolve. In many cases, filing too early without all documents actually delays your final tax resolution by months.
Missing Late-Arriving Tax Forms
Certain types of income are notorious for late reporting. K-1 forms, which are issued to partners in a partnership, members of an LLC, or S-corporation shareholders, often arrive very close to the April deadline. If your financial portfolio includes private equity, hedge funds, or family-owned businesses, you simply cannot file in January. Attempting to do so will almost certainly trigger a mismatch notice from the IRS’s Automated Underreporter (AUR) system.

Errors Due to Speed
Simple clerical errors—misspelled names, transposed Social Security digits, or incorrect bank account numbers—are more common among early filers who are rushing to beat the clock. While e-filing software catches many of these, some errors pass through and cause significant processing delays. Taking an extra 24 hours to “sleep on it” and perform a final review of your return is a hallmark of professional financial management.
In conclusion, you can do your taxes as soon as the IRS systems open in late January, provided you have a complete and accurate set of financial documents. For the prepared taxpayer, filing early is a powerful tool for financial security and liquidity. However, the ultimate goal should be “accuracy first, speed second.” By aligning your filing timeline with the reality of your documentation, you can navigate tax season with confidence and precision.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.