
The financial landscape has undergone a seismic shift over the last decade, moving away from traditional credit cards toward more flexible, short-term financing solutions. Among the leaders of this movement is Klarna, a “Buy Now, Pay Later” (BNPL) giant that has redefined the checkout experience for millions of consumers globally. However, for many users, the experience is occasionally met with a frustrating digital roadblock: a declined transaction.
Unlike a traditional credit card with a fixed limit, Klarna operates on a dynamic approval system. If you have ever wondered why you cannot use Klarna—despite having a successful history with the platform or a healthy bank balance—the answer lies in a complex web of real-time financial assessments, internal algorithms, and risk management strategies. Understanding these mechanisms is essential for any consumer looking to integrate BNPL services into their broader personal finance strategy.
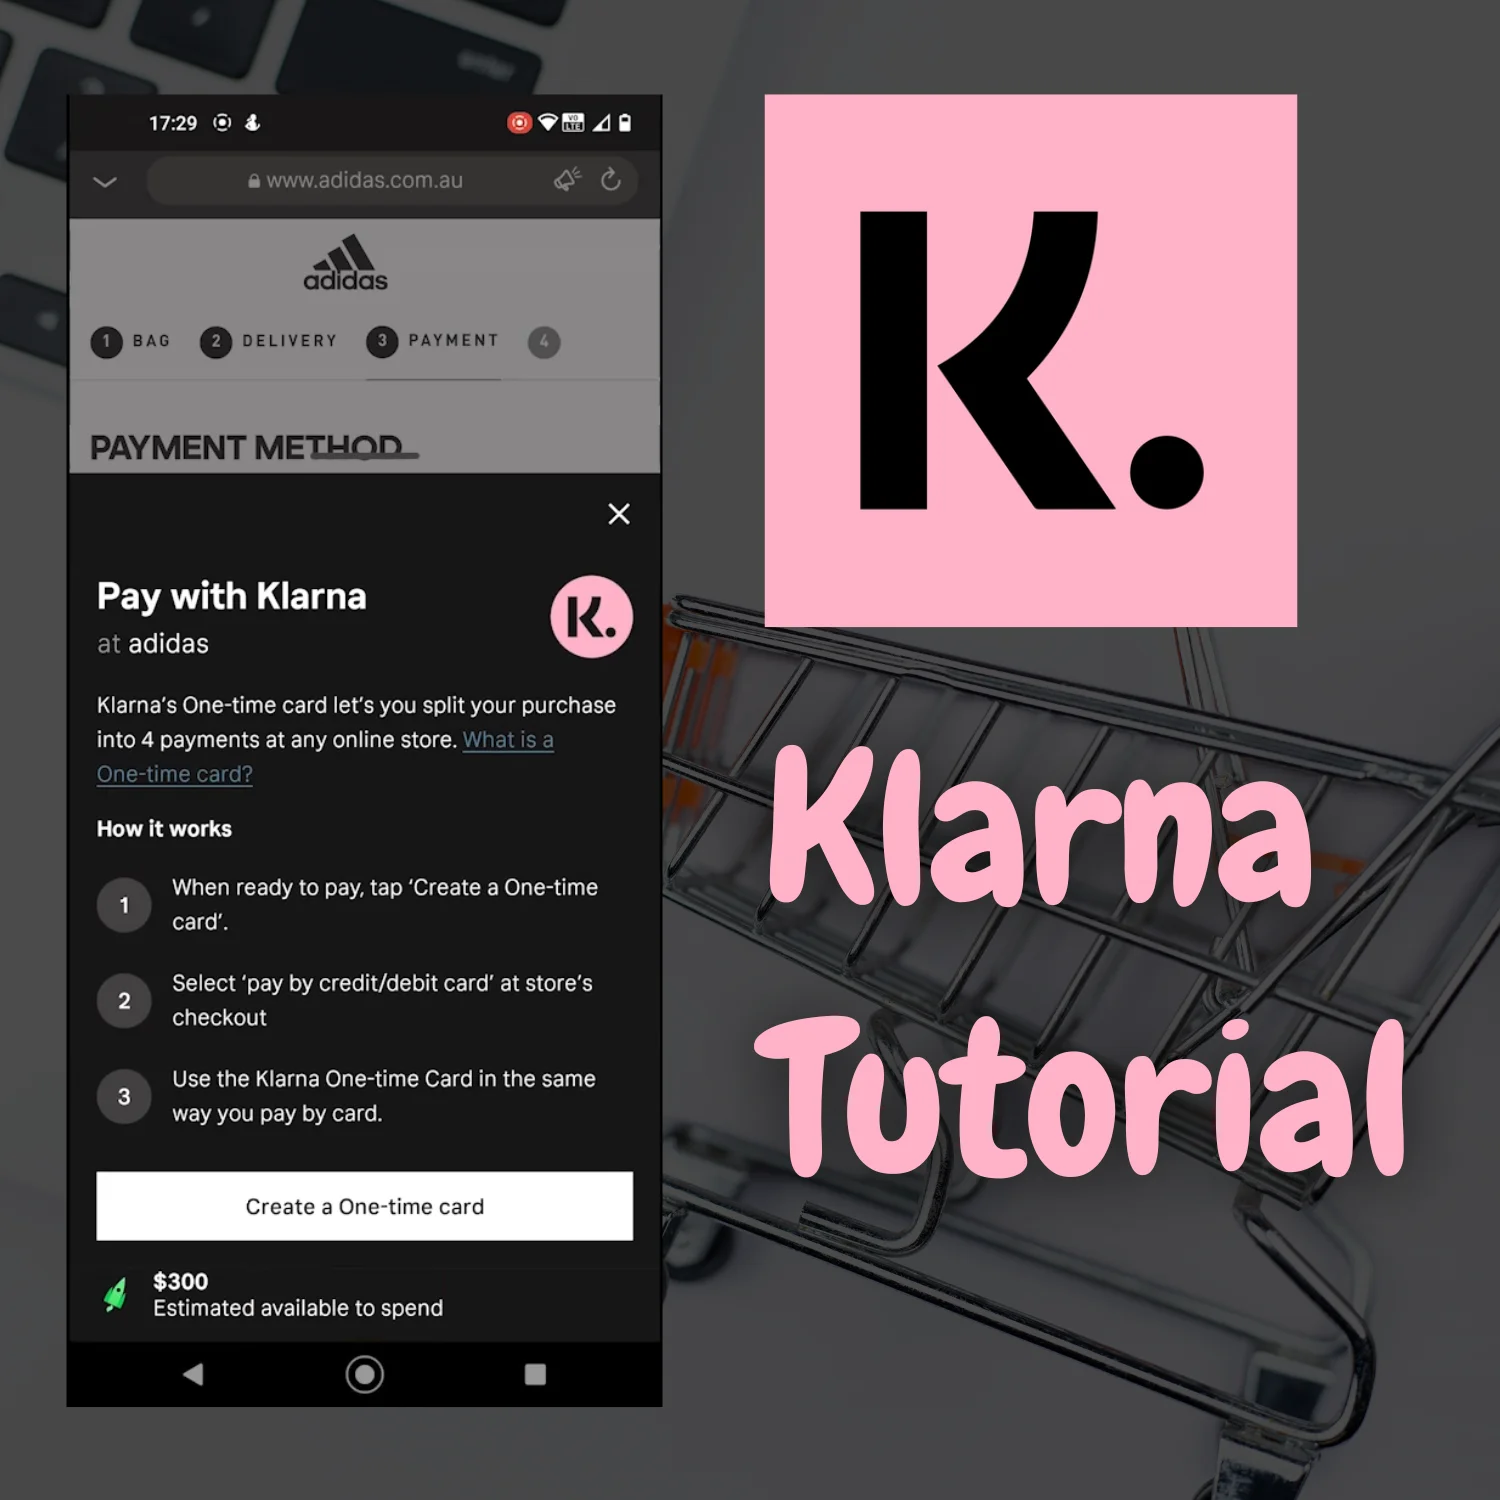
The Invisible Algorithms: How Klarna Evaluates Your Creditworthiness
When you click the Klarna button at checkout, the service performs a lightning-fast evaluation of your financial profile. This is not a static check; it is a live assessment that considers dozens of data points. Understanding what happens behind the scenes can demystify why an approval might be withheld.
The Role of Soft Credit Checks
One of the primary reasons consumers gravitate toward Klarna is the promise of avoiding “hard” credit inquiries that can damage a credit score. Instead, Klarna typically utilizes a “soft” credit check. This allows them to view your credit report—including your payment history with other lenders and your current debt levels—without leaving a permanent mark on your record.
However, if this soft check reveals high levels of existing debt, a history of late payments, or a low overall credit score, Klarna may deem the risk too high for a new transaction. Even if you have the funds available in your checking account today, the algorithm is looking at your long-term reliability as a borrower.
The Internal “Klarna Score”
Beyond external credit bureaus, Klarna maintains its own internal database of your behavior. Every time you use the service, you are essentially building a “Klarna credit score.” If you have a history of paying on time, your internal standing improves, often leading to higher spending limits and a higher likelihood of approval.
Conversely, if you have had a single late payment in the past, or if you frequently return items financed through the platform, the algorithm may flag your account. The platform prioritizes users who demonstrate a consistent ability to meet their financial obligations within the Klarna ecosystem specifically.
Real-Time Risk Assessment Models
Klarna’s approval process is also highly sensitive to the specific transaction at hand. It evaluates the total cost of the order, the type of goods being purchased, and even the retailer you are shopping with. A user might be approved for a $50 pair of shoes but declined for a $1,200 laptop. This is because the “risk of loss” increases with the transaction value. The algorithm calculates the probability of default for that specific amount based on your current financial profile and the time of day, your location, and even the device you are using to make the purchase.
Common Barriers to Approval: Why Your Transaction Was Declined
If your attempt to use Klarna is unsuccessful, it is rarely due to a single factor. Usually, it is a combination of technical discrepancies and financial red flags. Identifying which of these categories you fall into is the first step toward resolving the issue.
Technical Discrepancy and Identity Verification
A surprisingly common reason for a decline has nothing to do with money and everything to do with data. To prevent fraud, Klarna requires a perfect match between your account information and your shipping details. If you are attempting to ship an item to an address that does not match your billing address, or if the name on your Klarna account differs slightly from the name on your debit card, the system may automatically trigger a decline.
Furthermore, if you are a new user, Klarna may not have enough data to verify your identity through the soft credit check. In these cases, the “lack of history” is treated as a risk factor, leading to an initial rejection until more information can be provided or a smaller purchase is attempted.
Insufficient Funds and Card Connectivity
For “Pay in 4” or “Pay in 30 Days” options, Klarna must be able to verify that your connected payment method is valid and has sufficient “buffer” room. If you are using a prepaid card, you will likely be declined, as Klarna generally requires a linked debit or credit card from a mainstream financial institution.
Additionally, if your bank has restrictive settings regarding automated withdrawals or international transactions (as Klarna is a Swedish company, though it operates locally), the initial “authorization hold” might fail. This failure is interpreted by Klarna as an inability to pay, resulting in a declined transaction.
Unpaid Balances and Outstanding Debt
Klarna operates on a revolving door of trust. If you have an outstanding balance on another Klarna purchase—even if it isn’t “late” yet—the system may prevent you from taking on additional debt. The platform calculates your total “exposure.” If your total outstanding balance across all BNPL platforms (which can sometimes be seen via open banking integrations) exceeds a certain percentage of your estimated income, the system will pause new approvals until previous debts are cleared.
Navigating the Concept of Purchasing Power
One of the most misunderstood aspects of Klarna is “Purchasing Power.” Unlike a credit card with a “Credit Limit” of $5,000, Klarna gives you an estimated “Purchasing Power.” This is an elusive figure that can fluctuate daily.
Why Your Spending Limit Isn’t Fixed
Purchasing Power is a dynamic estimate of how much you can spend at any given moment. It is influenced by the current economic climate, Klarna’s own liquidity, and your recent financial activity. If you have recently applied for multiple credit cards or if there is a general economic downturn, Klarna may proactively lower the Purchasing Power for all users to mitigate institutional risk.
It is also important to note that having a certain amount of Purchasing Power does not guarantee approval. You might see an estimate of $1,000 in the app, but if you try to spend $800 at a high-risk merchant, the specific transaction might still be declined. The Purchasing Power is a “best-case scenario” rather than a guaranteed loan amount.
The Role of External Economic Factors
In periods of high inflation or rising interest rates, BNPL providers often tighten their lending criteria. Because Klarna essentially provides interest-free loans for its “Pay in 4” product, their margins are thin. When it becomes more expensive for Klarna to borrow the money they lend to you, they become much more selective about who they approve. If you find you suddenly “can’t use Klarna” despite no changes to your personal habits, it may be a result of the company adjusting its overall risk appetite due to macro-economic shifts.
Strategic Steps to Improve Your Approval Odds
If you have been declined, it is not a permanent ban. There are concrete, financial steps you can take to improve your standing and regain access to the service.
Optimizing Your Financial Profile
The most effective way to ensure Klarna approval is to demonstrate financial stability. This means:
-
Paying Down Existing Debt: Reducing the balance on your credit cards can improve your soft credit score, which Klarna sees instantly.
-
Using a Debit Card: Linking a high-quality debit card from a major bank rather than a credit card or a digital-only neo-bank can sometimes increase trust scores.
-
Ensuring Consistent Data: Make sure your name, address, and phone number are identical across your bank, your Klarna account, and the retailer’s checkout page.
Best Practices for Consistent Use
For those who are new to the platform or trying to rebuild their “Klarna score,” start small. Attempting to finance a $50-100 purchase and paying it off early or on time is the best way to prove reliability. Over time, as the system sees successful repayment cycles, your Purchasing Power will naturally increase, and the algorithmic “threshold” for your account will lower, making future approvals more likely.
The Broader Context of BNPL in Personal Finance
While Klarna offers a convenient way to manage cash flow, it is important to view it through the lens of overall financial health. If you are consistently being declined by Klarna, it may be a signal from an objective algorithm that your current debt-to-income ratio is reaching a critical point.
Debt Management and Credit Scores
While Klarna’s “Pay in 4” doesn’t usually affect your credit score when used correctly, their longer-term financing products can. Furthermore, in some regions, credit bureaus are beginning to integrate BNPL data into standard credit reports. Being unable to use Klarna might be a blessing in disguise, preventing the “stacking” of debt—a common pitfall where users have multiple small payments across various platforms that eventually snowball into an unmanageable monthly obligation.

Alternatives and Financial Planning
If Klarna remains unavailable, it is a prudent time to evaluate alternatives. This might include building an emergency fund to cover larger purchases in cash or using a traditional credit card that offers rewards, provided the balance is paid in full to avoid interest. The goal of using any financial tool, including Klarna, should be to enhance your financial flexibility, not to bridge a gap created by overspending.
In conclusion, “why you can’t use Klarna” is usually a multifaceted answer involving your credit history, your behavior within the app, and the specific details of your purchase. By treating BNPL as a serious financial commitment and maintaining a clean digital financial footprint, you can maximize your chances of approval and use these modern tools to your advantage.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.