
For the majority of households, a vehicle represents the second-largest financial investment after a primary residence. Yet, unlike a home, which typically appreciates over time, a car is a rapidly depreciating asset. Understanding the precise market value of your vehicle is not just a matter of curiosity; it is a fundamental component of proactive personal finance management. Whether you are looking to sell, trade in for a newer model, or simply calculate your current net worth, knowing how to see how much your car is worth requires a blend of data-driven research and an understanding of current market dynamics.
In the modern financial landscape, the value of a car is no longer a fixed number found in a printed guidebook. It is a fluid figure influenced by real-time supply chain issues, regional demand, and the specific maintenance history of the unit in question. To navigate this, one must utilize various valuation tools while accounting for the nuances of the automotive secondary market.
The Financial Mechanics of Vehicle Valuation
Before diving into the tools used to find a car’s value, it is essential to understand the underlying financial mechanics that dictate that number. Every vehicle sits on a depreciation curve, but that curve is rarely a straight line.
Understanding Depreciation and the “Drive-Off” Effect
Depreciation is the most significant cost of car ownership, often exceeding the cost of fuel or insurance. Most new vehicles lose approximately 20% of their value within the first year of ownership and roughly 60% of their original value after five years. However, this is a generalization. Luxury brands often depreciate faster due to high maintenance costs out of warranty, while reliable economy brands like Toyota or Honda tend to hold their value significantly better. Understanding where your specific make and model sits on this curve is the first step in financial planning for your next transition.
Equity vs. Market Value
When determining what a car is worth, you must distinguish between market value and your equity position. Market value is what a buyer is willing to pay. Your equity is the market value minus any remaining balance on a car loan. If you owe more than the car is worth—a situation known as being “underwater” or having negative equity—the valuation process becomes even more critical. Accurate valuation allows you to determine if you need to bring cash to the table during a sale or if you have enough “trade-in equity” to use as a down payment on a replacement.
Essential Tools and Platforms for Accurate Pricing
To get an accurate picture of your car’s worth, you should never rely on a single source. Financial professionals recommend triangulating data from at least three different types of valuation platforms to find a realistic price range.
The Big Three: Kelley Blue Book, Edmunds, and NADA
These are the legacy giants of automotive valuation. Kelley Blue Book (KBB) is perhaps the most well-known, providing a “Fair Purchase Price” and a “Trade-In Value” based on massive amounts of regional transaction data. Edmunds offers a “True Market Value” (TMV) tool that often leans more conservative but is highly regarded for its accuracy in private-party sales. NADA (National Automobile Dealers Association), now powered by J.D. Power, is the gold standard for lenders. If you are applying for a loan or dealing with an insurance claim, the NADA clean retail value is often the benchmark the financial institution will use.
Instant Cash Offer Platforms
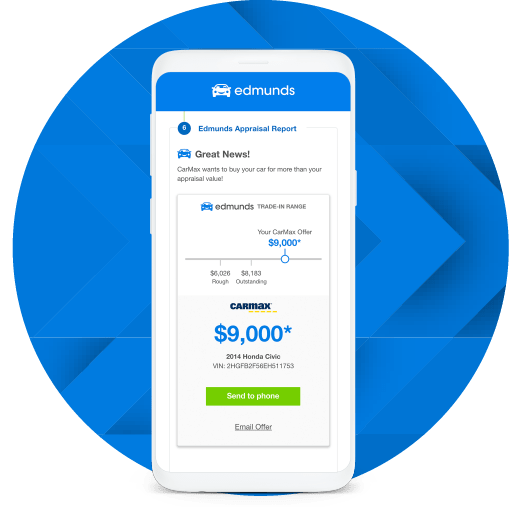
In recent years, the rise of digital retailers like Carvana, Vroom, and CarMax has revolutionized how we see a car’s value. Unlike KBB, which gives you a theoretical estimate, these platforms provide an “Instant Cash Offer.” This is a hard number at which the company is willing to cut you a check right now. In a volatile market, these offers are often the most accurate reflection of “liquid value.” If you need to sell the car within 48 hours, this is what it is worth.
Peer-to-Peer Marketplaces
To see what your car is worth on the retail market, you must look at what similar vehicles are actually selling for in your zip code. Browsing AutoTrader, Facebook Marketplace, and Bring a Trailer (for enthusiast or luxury cars) provides a “boots on the ground” perspective. If KBB says your car is worth $15,000, but every similar listing in your city is priced at $18,000 due to a local shortage, the higher number is your target.
Variables That Influence Your Specific Market Value

No two cars are identical, and several key variables can swing a valuation by thousands of dollars. When using valuation tools, you must be brutally honest about these factors to get a realistic financial outlook.
The “Condition” Trap
Most car owners believe their vehicle is in “Excellent” condition. Statistically, less than 5% of used cars truly fit this description. Most vehicles fall into the “Good” or “Fair” categories. A car in excellent condition has no cosmetic flaws, a perfect interior, and a full service history. Being overly optimistic about condition leads to inflated expectations that can derail a financial plan or a negotiation.
The Impact of Mileage and Maintenance
Mileage is a primary driver of depreciation. Most valuation algorithms use an average of 12,000 to 15,000 miles per year. If your car is significantly above this, its value will drop precipitously as it nears major service intervals (like 100,000 miles). Conversely, a well-documented service history can add a “premium” to your value. In the eyes of a savvy buyer or a dealer, a car with a stack of receipts for every oil change and brake job is worth more than a “black box” vehicle with no history.
Geographic and Seasonal Demand
Where you live matters as much as what you drive. A rear-wheel-drive convertible is worth significantly more in Florida in the spring than it is in Maine in November. Likewise, a four-wheel-drive SUV commands a premium in mountainous regions. When checking your car’s worth, ensure the tools are calibrated to your specific zip code to account for these regional economic variances.
Strategies to Maximize Your Vehicle’s Resale Value
Once you have identified the baseline value of your car, the goal shifts to maximizing that asset. Treating your car like a financial investment requires specific actions to ensure you capture the highest possible return.
Reconditioning vs. ROI
Before selling or trading in, consider the return on investment for repairs. Investing $200 in a professional detail can often add $500 to $1,000 to the perceived value of the car. However, spending $1,500 on a major mechanical repair right before selling rarely nets a dollar-for-dollar return. The key is to address “low-hanging fruit”—fix small dents, replace burnt-out bulbs, and ensure the tires are properly inflated and cleaned.
Choosing the Right Sales Channel
The “worth” of your car changes depending on who you sell it to:
-
Trade-In: This is the most convenient but offers the lowest value (wholesale). However, in many states, you only pay sales tax on the difference between the new car price and the trade-in value, which can provide a significant “tax shield.”
-
Private Party: This offers the highest value (retail) but requires the most effort. You must handle the marketing, showings, and title transfer.
-
Instant Cash Offers: These fall in the middle—higher than many dealer trade-ins but lower than a private sale.
Integrating Car Value into Your Broader Financial Plan
Finally, knowing how to see how much your car is worth is a vital part of overall wealth management. It should not be a one-time check, but a recurring part of your financial audit.
Net Worth Tracking
Your car is an asset on your personal balance sheet. By tracking its value annually, you can get a more accurate picture of your net worth. This is particularly important if you are planning to leverage your assets for a mortgage or other large loan. Seeing the depreciation in real-time also helps you decide the “optimal exit point”—the moment when the cost of maintenance begins to outweigh the remaining value of the asset.
Insurance and Risk Management
If your car’s value has dropped significantly, you may be overpaying for insurance. For instance, if your car is worth $3,000 and you have a $1,000 deductible, the “gap” covered by the insurance company is only $2,000. At that point, it may be financially prudent to drop collision coverage and “self-insure” that risk, potentially saving hundreds of dollars a year in premiums.
Timing the Replacement Cycle
By monitoring your car’s value, you can time your next purchase strategically. If you see that your specific model is currently in high demand due to a market fluke (such as a temporary production halt of new models), it might be the perfect time to sell high and move into a different asset class or a more efficient vehicle.
In conclusion, seeing how much your car is worth is the first step in taking control of one of your largest recurring expenses. By using the right tools, being honest about condition, and understanding the tax and net worth implications, you can transform your vehicle from a mysterious monthly drain into a transparent, managed financial asset.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.