
For the majority of households, a vehicle represents the second-largest financial commitment after a primary residence. Yet, unlike a home, which typically appreciates over time, a car is a rapidly depreciating asset. Understanding how to accurately value your car is not merely a matter of curiosity; it is a critical component of personal finance management. Whether you are looking to sell, trade in for a newer model, update your net worth statement, or ensure you have adequate insurance coverage, mastering the mechanics of vehicle valuation is essential for protecting your financial health.
Understanding the Financial Mechanics of Vehicle Depreciation
To value a car effectively, one must first understand the primary force working against its worth: depreciation. In financial terms, depreciation is the allocation of the cost of a tangible asset over its useful life. For vehicles, this decline in value is often front-loaded and influenced by a variety of market forces.
The Velocity of Value Loss
On average, a new car loses approximately 20% of its value within the first twelve months of ownership. Following that initial plunge, the rate of depreciation typically stabilizes to roughly 10% to 15% per year for the next four years. By the five-year mark, a vehicle may be worth only 40% of its original purchase price. From a wealth management perspective, understanding this curve allows an owner to identify the optimal time to exit the asset before the maintenance costs begin to outweigh the residual value.
Market Variables and External Economic Drivers
While mileage and condition are internal factors, external economic drivers play a significant role in valuation. Interest rates, for instance, have a direct impact on the used car market. When interest rates are high, the cost of financing a used vehicle increases, which can suppress demand and lower the “Fair Market Value” (FMV) of your car. Conversely, supply chain disruptions in the new car market—as seen in recent years—can cause a paradoxical spike in used car values, sometimes allowing owners to sell vehicles for nearly what they paid years prior.
Key Financial Metrics and Valuation Methodologies
When you ask, “How do I value my car?” you are actually asking for several different numbers depending on the context of the transaction. Financial professionals distinguish between various “buckets” of value, each serving a specific purpose.
Trade-In Value vs. Private Party Value
The trade-in value is the amount a dealership is willing to credit you toward the purchase of another vehicle. From a financial standpoint, this is usually the lowest valuation. Dealerships must account for their own overhead, reconditioning costs, and profit margins. However, trading in often provides a “tax shield.” In many jurisdictions, you only pay sales tax on the difference between the new car’s price and your trade-in’s value, which can partially offset the lower valuation.
Private party value, on the other hand, is the price you can expect when selling directly to another individual. This figure is consistently higher—often by 10% to 20%—because you are capturing the profit margin that a dealer would otherwise take. The trade-off is the “opportunity cost” of your time and the increased risk associated with the transaction.
Wholesale vs. Retail Value
Wholesale value (often referred to as “Black Book” value) is what cars fetch at professional auctions. This is the “liquidation value” of the asset. Retail value is what the end consumer pays on a dealer lot. If you are valuing your car for the purpose of a total-loss insurance claim, you are looking for the retail value, as the goal is to find the “replacement cost” of a similar asset in the current market.
The “Comps” Method: Market Comparison
Just as real estate agents use “comps” (comparable sales) to price a home, savvy car owners should look at actual listing prices for vehicles of the same year, make, model, trim level, and mileage within a 50-mile radius. This provides a real-time snapshot of local market liquidity. If three similar cars are sitting on lots for $20,000 and not moving, your car is likely valued closer to $18,500.
Leveraging Digital Financial Tools for Real-Time Appraisal

In the modern era, valuing a car has become a data-driven exercise. Several financial platforms aggregate millions of data points to provide highly accurate estimates.
Algorithmic Pricing Engines
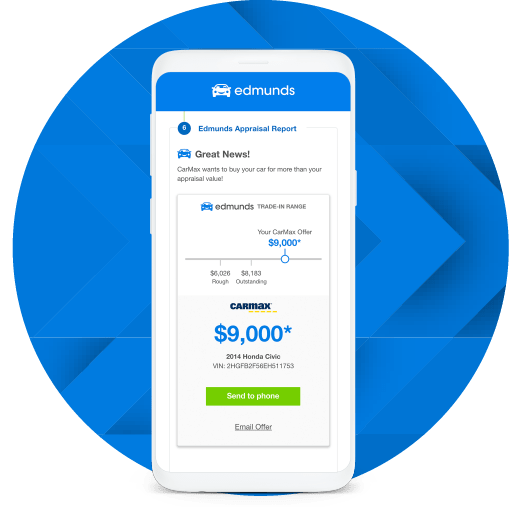
Platforms like Kelley Blue Book (KBB), Edmunds, and NADAguides use proprietary algorithms to track auction results, dealer track records, and private sales. When using these tools, it is vital to be brutally honest about the vehicle’s condition. Financial experts note that while most owners believe their car is in “Excellent” condition, less than 5% of used vehicles actually meet that criteria. Categorizing a “Good” car as “Excellent” can lead to a valuation error of several thousand dollars, skewing your financial planning.
VIN-Specific Data and Vehicle History Reports
The Vehicle Identification Number (VIN) is the key to unlocking a car’s specific financial history. Services like Carfax or AutoCheck are not just for buyers; sellers should use them to understand how their car is perceived by the market. A vehicle with a recorded accident—even if perfectly repaired—suffers from “diminished value.” This is a permanent reduction in the asset’s worth due to its history. Quantifying this hit is essential for an accurate valuation.
Instant Cash Offer Platforms
A relatively new development in the financial landscape of car valuation is the “Instant Cash Offer” from companies like Carvana, Vroom, or Shift. These platforms provide a “buy-figure” that is guaranteed for a short period. While these offers might not represent the absolute ceiling of what your car is worth, they provide a rock-bottom liquidity floor. If you have a cash offer for $15,000 in hand, you know with 100% certainty that your car is worth at least that much in today’s market.
Maximizing Asset Recovery: Strategies to Boost Resale Value
Valuing your car is a passive act; increasing that value is an active financial strategy. To maximize the recovery of your initial investment, you must treat the vehicle as a business asset.
Maintenance Documentation as Financial Proof
In the world of finance, if it isn’t documented, it didn’t happen. A car with a complete, chronological folder of service records is worth significantly more than an identical car with no paperwork. These records serve as “proof of life” for the mechanical components, reducing the risk premium a buyer would otherwise demand. Organized records can often add 5% to 10% to the final sale price.
The ROI of Cosmetic and Mechanical Refurbishment
Before finalizing a valuation for sale, consider the Return on Investment (ROI) of minor repairs. For example, spending $150 on a professional detail can often increase the perceived value of a car by $500 or more. Conversely, replacing tires that have 30% life left may not yield a 1:1 return on investment. Focus on “low-cost, high-visibility” improvements to maximize the asset’s appeal without over-capitalizing on a depreciating item.
The Tax and Insurance Implications of Car Valuation
Accurate valuation is not only about selling; it is about protecting your net worth from catastrophic loss and optimizing your tax position.
Insurance Payouts and Gap Coverage
If your car is totaled or stolen, the insurance company will perform its own valuation to determine the “Actual Cash Value” (ACV). If you owe more on your auto loan than the ACV of the car—a state known as being “underwater”—you face a significant financial liability. Understanding your car’s current value allows you to determine if you need “Gap Insurance,” which covers the difference between the car’s value and the loan balance. Without an accurate valuation, you may be unknowingly exposed to thousands of dollars in personal liability.
Business Use and Tax Deductions
For entrepreneurs and the self-employed, the valuation of a vehicle is tied to tax strategy. If you use your car for business, you can choose between deducting the standard mileage rate or the actual expenses, including depreciation. To calculate depreciation accurately for the IRS, you must have a baseline valuation and a clear understanding of the asset’s “basis.” Furthermore, if you choose to donate your vehicle to charity, the IRS typically limits your deduction to the “Fair Market Value” or the price the charity receives when they sell it. Knowing the FMV beforehand ensures your tax filings are defensible and optimized.

Final Thoughts on Asset Management
Valuing a car is a dynamic process that requires a blend of data analysis, market awareness, and objective self-assessment. By viewing your vehicle through a financial lens—monitoring depreciation, leveraging appraisal tools, and maintaining the asset for maximum recovery—you transform a simple mode of transportation into a well-managed component of your broader financial portfolio. Whether the goal is to liquidate the asset or simply to understand your current equity position, a rigorous approach to valuation ensures that you are making informed decisions backed by hard data rather than emotional attachment.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.