
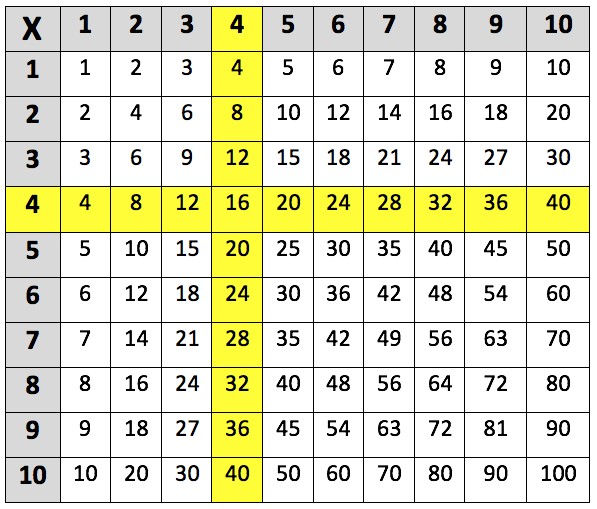
In an era dominated by complex algorithms and sophisticated financial software, the simple arithmetic problem “what is 4 times 3” might seem laughably basic. Yet, its answer – a straightforward 12 – represents far more than a mere numerical result. It embodies the fundamental principles of quantitative understanding that underpin every facet of personal finance, investing, and business strategy. Far from being an relic of elementary education, the ability to grasp and apply such core mathematical concepts is an indispensable skill, forming the bedrock upon which sound financial decisions are built. This seemingly simple multiplication acts as a potent metaphor for the essential numeracy required to navigate and succeed in the intricate world of money.
The Foundational Pillar of Financial Literacy
At its core, financial literacy is the ability to understand and effectively use various financial skills, including personal financial management, budgeting, and investing. Without a solid grasp of basic arithmetic operations like multiplication, addition, subtraction, and division, true financial literacy remains elusive. “4 times 3” is not just an isolated problem; it’s a gateway to comprehending scales, proportions, and the cumulative effects of financial actions.
Beyond Simple Arithmetic: Understanding Proportions
Consider the idea of proportions. If an item costs $4 and you need 3 of them, the total cost is $12. This isn’t groundbreaking, but the underlying principle extends to far more complex scenarios. What if an investment grows by 4% over 3 periods? Understanding how these percentages compound or interact requires a foundational comfort with multiplication. It helps in recognizing that 4 units of effort yielding 3 units of return might differ significantly from 3 units of effort yielding 4 units of return. This proportional thinking is critical for evaluating value, comparing options, and forecasting outcomes, whether you’re assessing the cost-benefit of a new car or the potential return on a stock. It moves individuals beyond memorization to genuine comprehension of financial relationships.
Why Basic Math Still Matters in a Digital Age
While calculators and financial apps can instantly provide the answer to “4 times 3,” relying solely on technology without understanding the underlying mechanics is a perilous path. The digital age, with its rapid transactions and automated calculations, often masks the critical need for human comprehension. When an app calculates your loan payment or investment return, it’s performing these basic operations countless times. Without an intuitive grasp of what these numbers represent and how they interact, individuals are vulnerable to misinterpretations, scams, and poor decision-making. The ability to do quick mental math or to at least sanity-check a technological output is a vital safeguard. It fosters critical thinking and prevents blind trust in algorithms, empowering individuals to question, verify, and ultimately make more informed choices about their money.
Everyday Applications in Personal Finance
The principles embedded in “4 times 3” manifest daily in personal finance, influencing everything from managing a household budget to planning for long-term goals. Ignoring these basic mathematical truths can lead to significant financial strain and missed opportunities.
Budgeting and Expense Tracking
A household budget is essentially a detailed exercise in addition, subtraction, and multiplication. If you spend $4 on coffee 3 times a week, that’s $12 just on coffee weekly – or $48 monthly, and over $500 annually. This simple calculation, extended across all categories of expenditure, reveals where money truly goes. Understanding these multiplications allows for effective expense tracking, identifying areas for potential savings, and allocating funds more strategically. It’s about recognizing the cumulative effect of small, recurring expenses that, when multiplied over time, can significantly impact one’s financial health. Without this clarity, budgeting becomes an abstract exercise rather than a concrete tool for financial control.
Saving Strategies and Growth
Saving is not just about putting money aside; it’s about understanding how that money can grow. If you save $4 every day, in 3 days you have $12. Over a month, that’s $120. Over a year, $1,460. These simple multiplications illustrate the power of consistent contributions. When compounded with interest, the numbers grow even more dramatically. Understanding “4 times 3” in this context helps individuals visualize the impact of consistent, even small, savings contributions over time. It transforms saving from a daunting task into a series of achievable, cumulative steps, demonstrating how seemingly insignificant daily habits can lead to substantial financial reserves. This numerical perspective fosters discipline and commitment to financial goals.
Debt Management and Interest Calculations
On the flip side, multiplication is central to understanding the insidious nature of debt, particularly high-interest debt. If a credit card charges 4% interest per month on a small balance of $300, that’s $12 in interest for that month alone, not even considering the original principal. Over a year, this can amount to a significant sum, especially if the balance isn’t paid off. Grasping this simple multiplication reveals how quickly interest can accumulate, highlighting the importance of paying down high-interest debts promptly. It underscores the concept of the “cost of money” and helps consumers make informed decisions about borrowing, ensuring they understand the true financial implications beyond the principal amount.

Strategic Thinking in Investing and Business
Moving beyond personal finance, the principles exemplified by “4 times 3” are fundamental to strategic thinking in the realms of investing and business. Investors and entrepreneurs constantly engage with figures that require a strong quantitative intuition to interpret and act upon.
Calculating Returns and Compound Interest
The magic of compound interest, often hailed as the “eighth wonder of the world,” is nothing more than repeated multiplication. If an investment yields a 4% annual return, after 3 years, the growth isn’t just 4% times 3 (or 12%). It’s (1 + 0.04) multiplied by itself 3 times. Understanding this distinction, though slightly more complex than a direct 4×3, builds directly on the foundational concept of multiplication. It empowers investors to project future values, compare different investment opportunities, and appreciate the long-term impact of even modest returns. This numerical fluency is crucial for setting realistic financial goals and evaluating the performance of one’s portfolio over time.
Assessing Business Multiples and Valuations
In business, ratios and multiples are critical for valuation. A common metric might be “price-to-earnings” (P/E) ratio. If a company earns $4 per share and its stock trades at a P/E of 3, its stock price might be estimated at $12. While this is a simplification, it illustrates how fundamental multiplication is to quick business assessments. Entrepreneurs use similar calculations to project revenue, calculate profit margins, and understand scalability. If expanding production by 4 units requires 3 times the current raw material cost, understanding the $12 impact (if units cost $1) is vital for operational planning and profitability analysis. These everyday business decisions hinge on the ability to swiftly process and interpret numerical relationships.
Risk Assessment and Diversification
Multiplication also plays a role in risk assessment. If the probability of a negative event is 4% and the potential financial impact is $3,000, the “expected loss” is $120. While risk assessment involves more sophisticated statistics, this simple example highlights how quantification helps in understanding potential exposures. Similarly, diversification strategies often involve allocating funds across different asset classes. If an investor wants to put 4% of their portfolio into 3 different emerging markets, understanding the total 12% allocation and its implications for overall risk profile and potential returns requires basic multiplication. It helps in striking a balance between potential gains and acceptable levels of risk.
Unlocking Financial Empowerment Through Numeracy
The journey from understanding “what is 4 times 3” to confidently navigating complex financial landscapes is a testament to the power of numeracy. It’s not about being a mathematician, but about developing a functional understanding of numbers that empowers informed decision-making.
The Cost of Financial Illiteracy
Conversely, the inability or unwillingness to engage with basic financial math carries a steep price. Individuals who struggle with simple calculations are more susceptible to predatory lending practices, less likely to understand the terms of financial products, and prone to making suboptimal choices with their savings and investments. The cumulative impact of missed savings opportunities, overpaid interest, and poor investment decisions can amount to hundreds of thousands of dollars over a lifetime. This “cost of ignorance” underscores the critical importance of foundational numeracy for protecting one’s financial well-being.
Developing a Quantitative Mindset
Cultivating a quantitative mindset means approaching financial problems with an eye for numbers, patterns, and relationships. It’s about asking “how much?” “how often?” and “what if?” and having the confidence to tackle the resulting calculations. This mindset encourages a proactive approach to financial planning, rather than a reactive one. It transforms money from an abstract concept into a tangible resource that can be managed, grown, and leveraged. It’s about moving beyond simply knowing “4 times 3 is 12” to instinctively applying that understanding to predict, plan, and protect financial futures.

From Calculation to Confident Decision-Making
Ultimately, the mastery of fundamental arithmetic like “4 times 3” serves as a springboard for confident financial decision-making. When individuals are comfortable with the numbers, they can critically evaluate information, understand the true implications of financial choices, and confidently chart their own course. This isn’t about rote calculation; it’s about the analytical thinking that numeracy fosters. It empowers individuals to take control of their financial destiny, making choices that align with their goals and values, rather than being swayed by external pressures or misinformation. In a world saturated with financial data, the ability to discern, interpret, and act upon simple numerical truths remains the most powerful tool for achieving lasting financial security and prosperity.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.