
The question “what is 10 as a fraction?” might seem deceptively simple, akin to a basic arithmetic problem from elementary school. At its core, 10 can be expressed as a fraction in many ways, the most straightforward being 10/1. It can also be written as 20/2, 100/10, or even 1000/100. However, dismissing this inquiry as merely rudimentary would be a disservice to its profound implications within the realm of personal and business finance. Understanding how whole numbers translate into fractions, and vice-versa, is not just an academic exercise; it forms a critical bedrock for robust financial literacy, influencing everything from managing a household budget to making complex investment decisions and navigating intricate business structures.
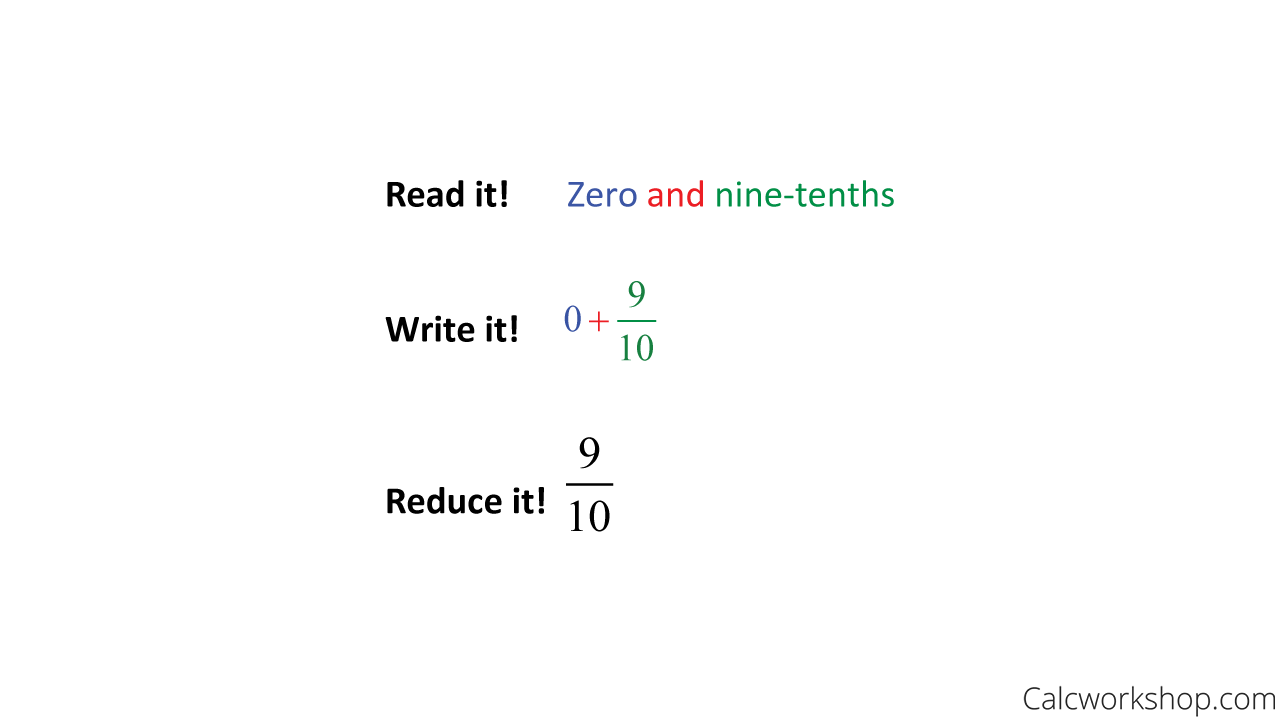
In the world of money, numbers rarely stand alone as simple integers. They are frequently presented as percentages, decimals, ratios, or, indeed, fractions – each representing a part of a whole or a relationship between different quantities. The ability to fluidly convert between these forms, starting with a basic understanding like expressing “10 as a fraction,” is an indispensable skill for anyone aiming to master their financial destiny. Without this fundamental grasp, individuals and businesses risk misinterpreting financial data, making suboptimal choices, and ultimately hindering their wealth accumulation and preservation efforts.
The Foundational Role of Basic Math in Personal Finance
Financial success is not solely about earning more; it’s profoundly about understanding, managing, and strategically deploying the money one has. This strategic deployment is fundamentally numerical. Every budget, investment prospectus, loan agreement, and financial report is saturated with numbers that demand interpretation beyond their face value. The simple act of converting a whole number like 10 into a fraction underscores the broader principle of dissecting financial information into understandable components.
Deciphering Financial Statements and Reports
Consider a company’s earnings report or a mutual fund’s prospectus. These documents are replete with data presented in various formats. A company might report revenue in whole numbers, but its profit margins or market share are almost invariably presented as percentages or fractions (e.g., “we captured 1/5th of the new market segment”). If an investor struggles to conceptualize how 1/5 relates to a whole, or how that translates into a percentage (20%), their ability to evaluate the company’s performance critically is severely hampered. Understanding that 10 is 10/1, and can be seen as a portion of a larger whole (e.g., 10 out of 100 shares, which is 1/10 or 10%), provides a mental framework for processing more complex financial relationships. This foundational understanding allows for a more accurate assessment of financial health and potential growth.
Understanding Percentages and Ratios
Fractions are the direct precursors to percentages and ratios, which are omnipresent in finance. An interest rate is a percentage, representing a fraction of the principal amount. A debt-to-income ratio is a fraction comparing two quantities. A stock’s dividend yield is a percentage derived from its dividend per share divided by its share price. When you see “10% off” in a sale, you’re mentally converting that 10% into a fraction (10/100 or 1/10) to calculate the discount. Similarly, understanding that 10 is a whole number helps one grasp that 10% of something is a part of that whole, just as 10/100 is a part of 1. This seemingly minor cognitive bridge is crucial for interpreting everything from mortgage rates and savings interest to credit card annual percentage rates (APRs) and investment returns. Without this basic fluency, making informed financial decisions becomes a game of guesswork rather than strategic planning.
From Whole Numbers to Wealth Management: Practical Applications
The practical application of understanding numbers as parts of a whole extends across the entire spectrum of personal finance, from day-to-day budgeting to long-term wealth creation.
Budgeting and Income Allocation
Budgeting is fundamentally an exercise in allocating fractions of your income to different categories. If your monthly income is $5,000 and you decide to save $500, you are essentially saving 500/5000, which simplifies to 1/10 or 10% of your income. The whole number “10” (as in 10% or 1/10) here represents a critical portion of your financial strategy. Without a clear understanding of how these fractions or percentages relate to your total income, creating a realistic and effective budget is challenging. It’s the ability to visualize your income as a whole, and then divide it into various fractional components for housing, food, transportation, savings, and discretionary spending, that empowers sound financial planning. This foundational numerical comprehension allows individuals to prioritize spending, identify areas for reduction, and optimize savings goals.
Investment Portfolios and Diversification
In investing, fractions dictate diversification strategies and portfolio allocation. An investor might allocate 1/3 of their portfolio to stocks, 1/3 to bonds, and 1/3 to real estate. Or perhaps, for a more aggressive stance, 8/10 (or 80%) to equities and 2/10 (or 20%) to fixed income. These fractional allocations are critical for managing risk and optimizing returns. If an individual holds 10 shares in a company that has a total of 100 shares outstanding, they effectively own 10/100 or 1/10 of that company. Understanding this fractional ownership is vital for comprehending voting rights, dividend entitlements, and the overall impact of the investment on one’s net worth. The basic concept of 10 as a fraction (10/1, or 10/100 as a part of a larger whole) underpins these sophisticated investment concepts.
Debt Management and Interest Calculations
Debt management heavily relies on understanding how interest accrues, which is often expressed as an annual percentage rate (APR). An APR of 10% means that each year, you owe an additional 10/100 (or 1/10) of the outstanding principal in interest. This fractional relationship compounds over time, making it crucial to grasp the true cost of borrowing. Similarly, when making extra payments on a loan, you are effectively reducing the principal, which in turn reduces the fraction of the principal on which future interest is calculated. The simple act of converting a percentage back to a fraction helps demystify the mechanics of loans, mortgages, and credit card debt, enabling more effective strategies for debt reduction and avoidance.
Business Finance: Shares, Profits, and Capital Allocation
Beyond personal finance, the concept of fractions is interwoven into the fabric of business operations, from small startups to multinational corporations.
Equity Ownership and Profit Sharing
In business, particularly for partnerships or privately held companies, ownership is frequently expressed in fractional terms. A founder might own 5/10 (or 1/2) of the company, while an early investor owns 2/10, and an employee stock option pool accounts for the remaining 3/10. These fractions directly translate into profit sharing, voting rights, and the distribution of assets upon sale or liquidation. Understanding that “10” can represent a whole (100%) or a specific fractional share (e.g., 10 out of 100 units) is essential for negotiating ownership stakes, understanding partnership agreements, and comprehending the dilution of equity as new investors join. The ability to perform these mental conversions accurately ensures that all parties understand their true economic interest in the venture.
Project Budgeting and Resource Allocation
Businesses constantly allocate resources—time, money, personnel—across various projects and departments. This allocation is often done proportionally. If a company has a marketing budget of $100,000 and decides to dedicate $10,000 of it to social media campaigns, they are allocating 10/100 (or 1/10) of their budget to that specific channel. This fractional understanding allows for strategic resource deployment, ensuring that no single area consumes an disproportionate amount of capital relative to its expected returns. It also aids in tracking expenditures against budgeted allocations, providing insights into financial efficiency and potential overruns.
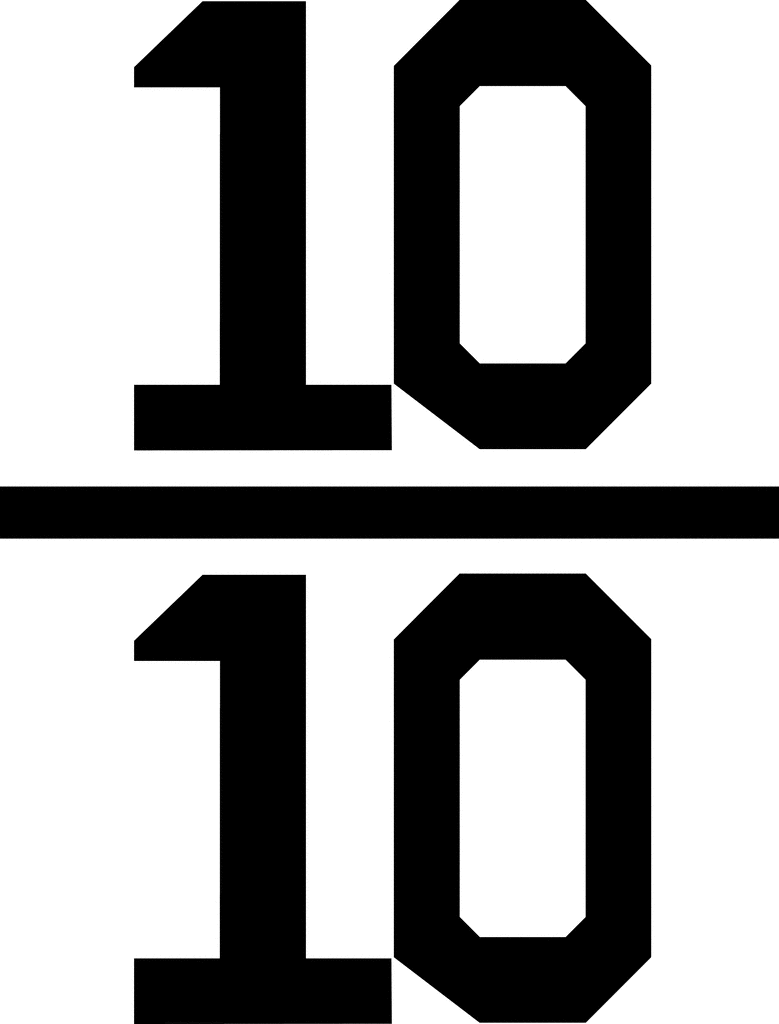
Empowering Financial Decisions Through Numerical Fluency
Ultimately, the question “what is 10 as a fraction?” serves as a gateway to a much broader discussion on financial literacy and numerical fluency. While the answer itself is straightforward, its implications for personal and business finance are expansive. From understanding the basics of saving and budgeting to navigating complex investment portfolios and intricate business deals, the ability to conceptualize numbers as parts of a whole, and to fluidly convert between whole numbers, fractions, decimals, and percentages, is an empowering skill.
In an increasingly data-driven world, where financial information is abundant but often presented in nuanced ways, those with a strong grasp of foundational mathematical concepts are better equipped to make informed, strategic decisions. They can critically evaluate financial products, accurately assess risks and returns, and confidently plan for their financial future. The seemingly simple query about expressing 10 as a fraction thus highlights the fundamental truth: a solid foundation in basic mathematics is not just an academic requirement, but a crucial component of financial intelligence and a key driver of economic empowerment.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.