
At first glance, the question “what fraction is equal to 3/4?” appears deceptively simple, a basic arithmetic problem encountered in elementary school. The answer, of course, is that 3/4 is equivalent to 75% or 0.75 in decimal form. However, beneath this foundational mathematical truth lies a profound relevance to the world of money. In finance, understanding fractions, percentages, and their interrelationships isn’t merely an academic exercise; it’s a cornerstone of financial literacy, impacting everything from personal budgeting and investment strategies to complex business valuations and economic analysis. This article delves into how this seemingly simple fraction—3/4—serves as a powerful lens through which to understand, manage, and optimize our financial lives, transforming abstract numbers into actionable insights.
The Fundamental Role of Fractions in Financial Literacy
Fractions are the building blocks of financial understanding. They allow us to represent parts of a whole, to compare values, and to distribute resources accurately. Without a grasp of these fundamental concepts, navigating the intricate landscape of personal finance, investing, and business operations becomes significantly more challenging, if not impossible. The fraction 3/4, or 75%, is particularly ubiquitous, often representing a significant portion of a whole that demands attention and strategic management.
Beyond Basic Arithmetic: Why Fractions Matter for Your Wallet
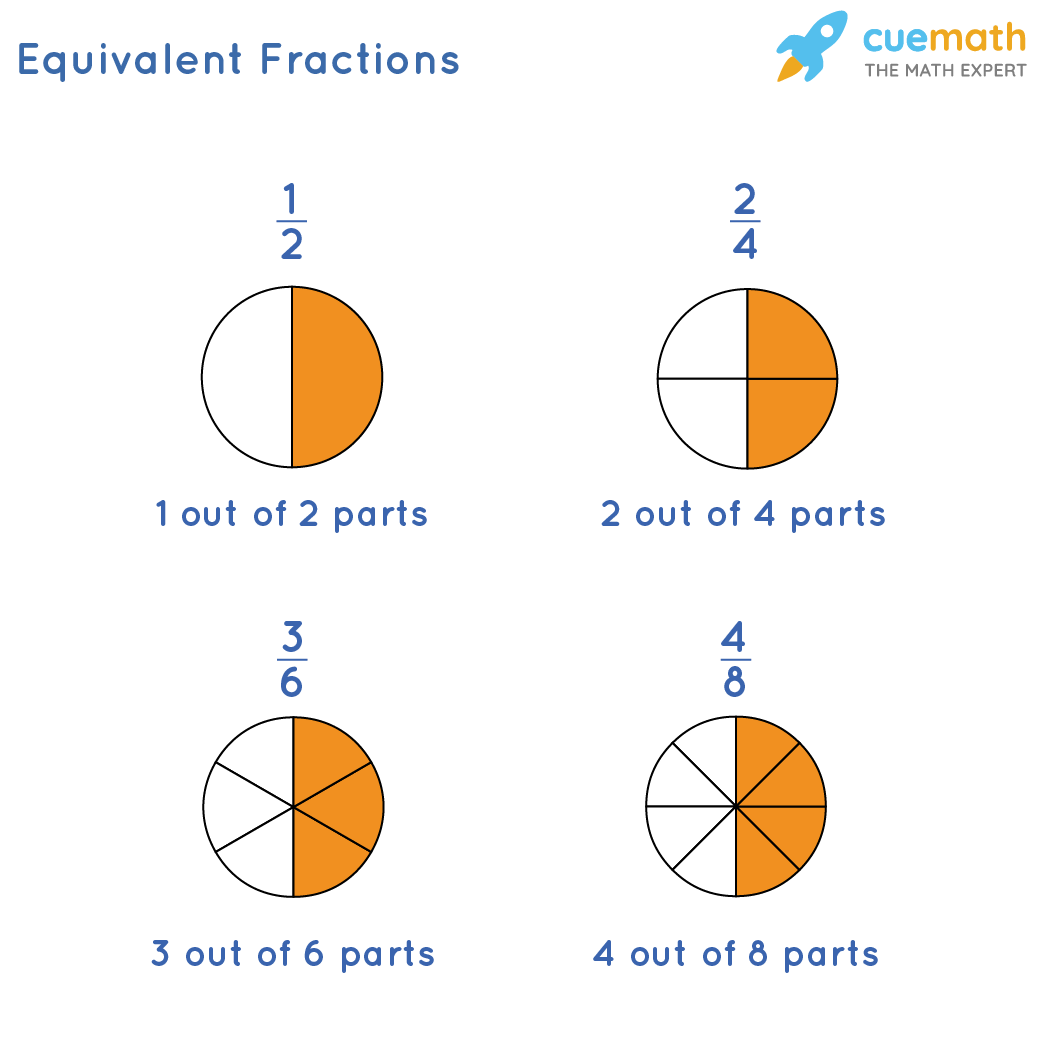
The ability to conceptualize a portion of something, whether it’s a budget, an investment portfolio, or a business’s revenue, is critical. When we understand that 3/4 represents three out of four equal parts, or 75% of a total, we gain immediate clarity. This isn’t just about passing a math test; it’s about making informed financial decisions. For instance, knowing that 3/4 of your income goes towards fixed expenses immediately tells you that 25% is left for discretionary spending or savings – a critical insight for financial planning. Fractions help us visualize distribution, identify imbalances, and allocate resources effectively, moving beyond mere numerical values to grasp the proportional reality of our financial situation. They provide a common language to discuss percentages, ratios, and rates of change that are omnipresent in financial discussions.
Deciphering Financial Statements and Reports
Every financial statement, from a personal bank statement to a corporate annual report, is replete with fractional concepts, often presented as percentages or ratios. Understanding that “3/4” translates to “75%” allows for immediate interpretation. For example, if a company reports that 75% of its revenue comes from a single product line, or that its operating expenses consume 3/4 of its gross profit, these are vital pieces of information. For investors, these figures might signal concentration risk or efficiency issues. For consumers, understanding terms like “3/4 APR” on a loan (meaning 0.75% interest per period) is crucial for comparing financial products. Fractions simplify complex data, enabling swift comprehension of key performance indicators, debt-to-equity ratios, profit margins, and return on investment figures, empowering better decision-making for both individuals and institutional players.
Unpacking “3/4” in Personal Finance
In the realm of personal finance, the fraction 3/4 frequently appears in practical scenarios, guiding individuals toward sound financial habits and helping them manage their money effectively. Its translation to 75% often represents a significant threshold or target in various aspects of financial planning.
Budgeting and Expense Allocation: The 75% Rule
One of the most common applications of 3/4 in personal finance is in budgeting. Many financial experts advocate for budget rules that allocate specific percentages of income. While the “50/30/20 rule” (needs/wants/savings) is popular, variations exist. A less structured, but equally insightful, application comes from understanding that perhaps 3/4 (75%) of your take-home pay might be dedicated to living expenses (housing, utilities, food, transportation, debt payments), leaving 1/4 (25%) for savings, investments, and discretionary spending. Recognizing that 75% of your income is already committed can be a wake-up call, prompting closer examination of spending habits and potential areas for reduction. Conversely, if your expenses are significantly less than 3/4 of your income, it indicates a healthy financial position, allowing greater capacity for wealth building.
Savings Goals and Progress Tracking
When working towards a financial goal, whether it’s saving for a down payment, a child’s education, or retirement, fractions provide a clear measure of progress. If you’ve saved 3/4 of your target amount, you know you’re 75% of the way there, with only 1/4 left to go. This tangible representation of progress can be incredibly motivating. For example, if you aim to save $10,000 and you’ve accumulated $7,500, understanding that you’ve reached the 3/4 mark helps you visualize the remaining effort and stay committed to your plan. It transforms abstract numbers into a concrete sense of achievement and provides a clear indicator of how much more effort is required to reach the finish line, allowing for adjustments to your savings rate if necessary.
Understanding Loan Payments and Interest Accrual
Fractions are embedded in the mechanics of loans and interest. Interest rates are typically expressed as annual percentages, which are essentially fractions. For instance, if you have a variable-rate mortgage where the interest rate can adjust by 3/4 of a percentage point (0.75%), understanding this fractional change is critical for projecting future payments. Similarly, when calculating the portion of your loan payment that goes towards interest versus principal, fractions are implicitly at play. Over the life of a loan, particularly early on, a significant fraction of each payment often goes towards interest, while a smaller fraction reduces the principal. Grasping this helps borrowers understand the true cost of credit and make informed decisions about debt management and accelerated repayment strategies.
The Impact of Fractions in Investing and Wealth Management
In the complex world of investing, fractions move beyond simple proportions to represent strategic allocation, performance measurement, and the distribution of ownership and returns. An astute understanding of these fractional relationships is vital for building and maintaining a robust investment portfolio.
Portfolio Diversification and Asset Allocation
One of the core principles of investing is diversification, which involves spreading investments across different asset classes, sectors, and geographies to mitigate risk. This entire strategy is built upon fractional allocation. For example, a common rule of thumb might suggest allocating 3/4 (75%) of a portfolio to equities and 1/4 (25%) to bonds for a growth-oriented investor. Or, within equities, an investor might decide to put 75% into large-cap stocks and 25% into small-cap stocks. Each decision about asset allocation is a fractional one, directly influencing the portfolio’s risk profile and potential returns. Understanding the impact of these fractions on overall portfolio performance is key to effective wealth management, ensuring the investment strategy aligns with individual risk tolerance and financial goals.

Interpreting Investment Returns and Dividends
Investment returns are almost universally expressed as percentages, which are fractions of the initial investment. A 3/4 (0.75%) quarterly return, for instance, translates to a different annual percentage depending on compounding. Similarly, dividends paid by stocks are often expressed as a fraction of the stock’s price (dividend yield) or as a fraction of the company’s earnings (payout ratio). If a company pays out 3/4 of its earnings as dividends, it signals a high payout ratio, which might be attractive to income investors but could also indicate less capital available for reinvestment and growth. Accurately interpreting these fractional expressions of return and distribution is crucial for evaluating investment opportunities and comparing the performance of different assets or funds.
Real Estate and Fractional Ownership
In real estate, fractions often define ownership structures. Fractional ownership, where multiple parties own distinct shares of a single property, is becoming increasingly common, especially for vacation homes or investment properties. An individual might own a 3/4 share of a property, with another investor owning the remaining 1/4. This division impacts everything from capital contributions and rental income distribution to maintenance responsibilities and voting rights on property decisions. Understanding these fractional shares is essential for legal agreements, profit-sharing, and exit strategies in co-owned assets. Furthermore, when discussing property values, appraisals often refer to “three-quarters of a million” or other fractional amounts, making a firm grasp of these concepts invaluable.
Business Applications: From Startup to Enterprise
For businesses, fractions are integral to operational analysis, strategic planning, and overall financial health. From the smallest startup to the largest multinational corporation, the ability to break down financial data into meaningful proportions is paramount for decision-making.
Profit Margins and Cost Analysis
Businesses live and die by their profit margins, which are fundamentally fractional. Gross profit margin, operating profit margin, and net profit margin are all calculated as a fraction (or percentage) of revenue. For example, if a business achieves a 3/4 (75%) gross profit margin, it means that for every dollar of sales, 75 cents remain after accounting for the direct costs of goods sold. This is a vital metric for assessing efficiency and pricing strategy. Similarly, cost analysis often involves examining what fraction of total expenses is allocated to different departments or functions. Understanding that 3/4 of operational costs are fixed, for instance, significantly impacts strategic decisions regarding scaling production or reducing overheads.
Equity Distribution and Business Valuation
In the lifecycle of a business, especially startups, equity distribution is a critical fractional exercise. Founders, early employees, and investors receive shares that represent a fraction of the company’s ownership. A venture capitalist might take a 1/4 (25%) stake, leaving the founders with 3/4 (75%). These fractions determine voting power, claims on profits, and capital gains upon exit. During business valuation, analysts often use multiples and discounted cash flow models, which rely on fractional growth rates and discount rates to arrive at a value. Understanding what fraction of projected future earnings contributes to current valuation, or what fraction of the company an investment will purchase, is crucial for both raising capital and making investment decisions.
Resource Allocation and Operational Efficiency
Effective resource allocation is a core tenet of business management, and it’s inherently fractional. Companies must decide what fraction of their budget to allocate to research and development, marketing, production, or human resources. For example, a company might dedicate 3/4 of its R&D budget to developing a new flagship product, with the remaining 1/4 for incremental improvements. Similarly, operational efficiency metrics, such as capacity utilization rates or employee productivity ratios, are often expressed as fractions or percentages. If a factory is operating at 3/4 (75%) capacity, it provides insights into potential for growth, bottlenecks, or excess capacity, guiding decisions on expansion or consolidation.
Leveraging Financial Tools for Fractional Understanding
While the conceptual understanding of fractions is vital, modern financial tools significantly enhance our ability to apply these concepts, making complex calculations and analyses accessible to everyone.
Budgeting Software and Spreadsheets
Digital budgeting tools, from simple spreadsheets to sophisticated financial management software, are built upon the ability to handle and visualize fractional data. Users can input their income and expenses, and the software automatically calculates what fraction or percentage of their income goes to housing, food, entertainment, and savings. These tools can readily show that 3/4 of your take-home pay is allocated to fixed expenses, instantly highlighting areas for potential optimization. They transform raw numbers into intuitive charts and graphs that make fractional distribution immediately apparent, empowering users to track their spending, identify trends, and make informed adjustments to their financial habits.
Investment Calculators and Portfolio Trackers
For investors, online calculators and portfolio tracking platforms are indispensable. Investment calculators can project future values based on fractional growth rates (e.g., 75% of your portfolio is in growth stocks, yielding X% annually), while portfolio trackers visually represent asset allocation, showing what fraction of your total assets is in stocks, bonds, or real estate. These tools simplify the analysis of compound interest, dividend reinvestment, and diversification strategies, allowing investors to experiment with different fractional allocations and understand their potential long-term impact on wealth accumulation. They remove the manual burden of calculating complex fractional scenarios, providing instant insights into portfolio health and performance against targets.

The Human Element: Financial Advisors and Education
Despite the sophistication of digital tools, the human element remains critical. Financial advisors play a crucial role in helping individuals and businesses understand and interpret the fractional nuances of their financial situations. They translate complex financial jargon and numerical reports into understandable concepts, guiding clients on appropriate fractional allocations for investments, debt management strategies, and retirement planning. Furthermore, continuous financial education—whether through courses, books, or reputable online resources—reinforces the importance of foundational mathematical concepts like fractions. A deeper understanding of “what fraction is equal to 3/4” in a financial context ultimately empowers individuals to take greater control of their financial destiny, making more informed decisions and building lasting wealth.
In conclusion, the simple question “what fraction is equal to 3/4?” opens a gateway to a sophisticated understanding of financial principles. From the allocation of personal budgets and the diversification of investment portfolios to the analysis of business profitability and equity distribution, the concept of 3/4 (or 75%) permeates the financial world. Mastering this fundamental relationship is not just about knowing a mathematical equivalence; it’s about gaining clarity, making smarter decisions, and ultimately, building a more secure and prosperous financial future. It underscores that even the most basic mathematical concepts hold profound and actionable insights for our money.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.