
In the landscape of high-value real estate, few assets carry as much prestige and consistent market demand as the brownstone. While the term is often used colloquially to describe any vintage townhouse in a metropolitan area, the brownstone represents a specific architectural and financial category that requires a sophisticated understanding of investment strategy, maintenance overhead, and long-term capital appreciation. For the modern investor or high-net-worth individual, a brownstone is more than just a home; it is a legacy asset with a unique risk-reward profile that differs significantly from contemporary glass-and-steel condominiums.
The Financial Fundamentals of the Brownstone Asset Class
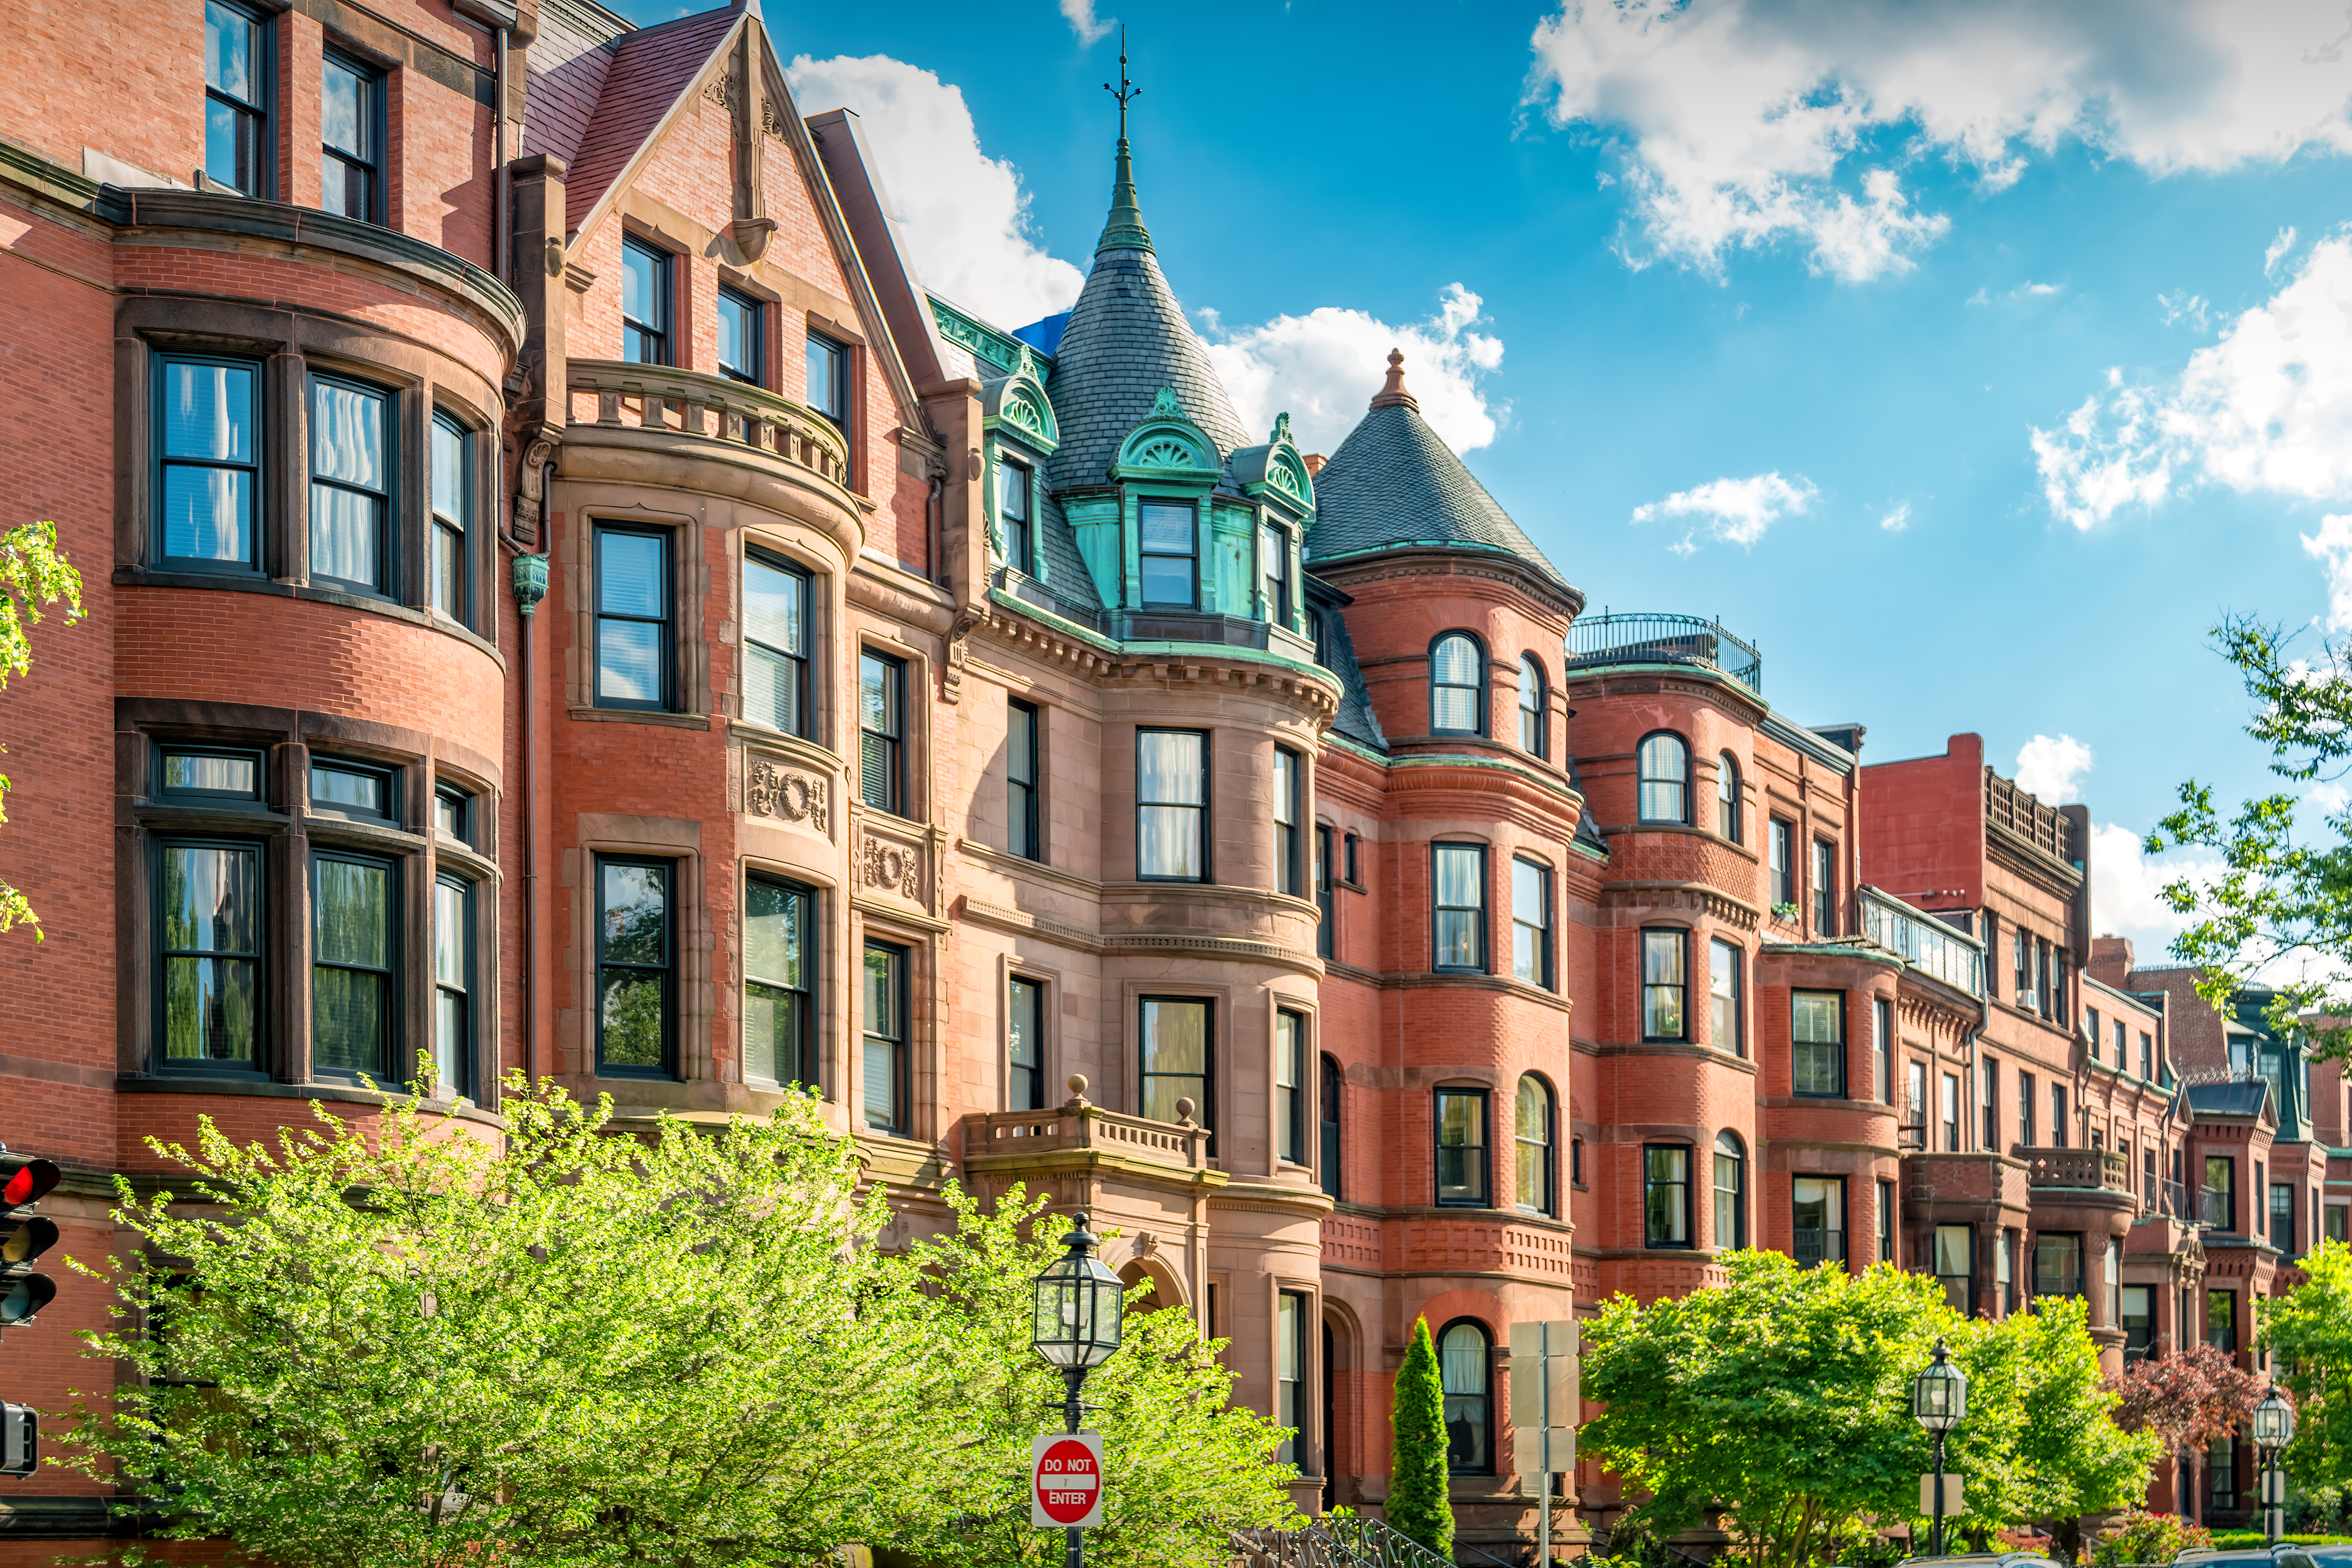
To understand the value of a brownstone apartment, one must first understand the material and its scarcity. Technically, a brownstone is a row house built with a brick facade that is clad in brown sandstone—a material primarily quarried from the Portland Brownstone Quarries in Connecticut during the 19th century. Because these quarries are largely defunct or limited in production, the supply of authentic brownstones is finite. In the world of finance, scarcity is a primary driver of value, and the fixed supply of these properties in desirable neighborhoods like Brooklyn’s Park Slope or Manhattan’s Upper West Side creates a permanent floor for asset pricing.
Appreciation and Market Resilience
Brownstones have historically shown a remarkable ability to retain value during market downturns. Unlike new developments, which can suffer from oversaturation in the market, the limited number of historic brownstones ensures that demand almost always outstrips supply. From a personal finance perspective, this makes them a “defensive” real estate play. While they may not see the 200% speculative spikes associated with emerging tech hubs, they offer steady, compounding appreciation that often outpaces inflation and general residential indices.
The Portfolio Diversification Benefit
For an investor with a portfolio heavily weighted in equities or digital assets, a brownstone provides tangible diversification. It is a “hard asset” with intrinsic utility. Furthermore, because brownstones are often located in high-density, high-income urban corridors, they are less susceptible to the volatility of suburban housing markets. They serve as a hedge against currency devaluation, providing both a store of value and a potential engine for monthly cash flow.
Investment Strategies: Single-Family vs. Multi-Unit Conversions
One of the most critical decisions an investor must make when acquiring a brownstone is how to structure the property’s utility. Brownstones generally fall into two categories: the “stately” single-family residence or the multi-family income generator. Each path carries distinct financial implications and tax treatments.
The Luxury Single-Family Model
Converting a multi-unit brownstone back into a single-family mansion is a popular strategy for high-net-worth individuals. While this reduces the immediate monthly rental income, it significantly increases the property’s resale value to a specific tier of affluent buyers. In markets like New York City or Boston, a meticulously restored single-family brownstone can command a massive premium per square foot compared to individual apartment units. This is a long-term capital gains play, where the investor bets on the scarcity of “turnkey” historic mansions.
The Income-Generating Multi-Family Strategy
Alternatively, many brownstones are divided into separate apartments—typically a “garden-level” unit, a “parlor floor” unit, and several upper-floor units. This structure is ideal for the “owner-occupant” investor. By living in one unit and renting out the others, the owner can effectively offset the mortgage, property taxes, and maintenance costs.
- The Garden Rental: Often the most lucrative unit due to private outdoor access.
- The Parlor Suite: High ceilings and original details allow for premium “boutique” rental rates.
- The Upper Floors: Generally lower ceilings but highly desirable for professional roommates or small families.
Short-Term vs. Long-Term Rental Yields
With the rise of high-end corporate housing and short-term rental platforms, brownstone owners can often achieve higher yields than they would with traditional 12-month leases. However, this requires a higher operational budget for management and a keen eye on local zoning laws and “hotel taxes,” which can impact the net operating income (NOI).
Navigating the High Costs of Historic Ownership

While the upside of brownstone ownership is significant, the financial “entry price” is only the beginning. These are aging structures that require specialized maintenance, and failing to account for these costs can quickly erode an investor’s margins.
The “Brownstone Tax”: Specialized Maintenance
The very feature that gives the building its name—the sandstone facade—is porous and prone to “spalling” or cracking over time due to freeze-thaw cycles. Repairing a brownstone facade is not a standard masonry job; it requires specialized artisans who can mix custom mortars to match the original stone. A full facade restoration can cost upwards of $50,000 to $150,000, a capital expenditure that must be factored into the five-to-ten-year financial plan.
Modernizing Infrastructure
Many brownstones still contain remnants of 19th-century infrastructure. Transitioning these buildings into the modern era involves significant “CapEx” (Capital Expenditure) projects:
- Electrical Upgrades: Replacing old knob-and-tube wiring to meet modern fire codes and the power demands of high-end appliances.
- HVAC Integration: Installing central air or high-efficiency heat pumps without destroying historic plaster moldings is a costly engineering challenge.
- Plumbing Overhauls: Moving from galvanized pipes to copper or PEX to ensure water pressure and quality for high-end tenants.
Landmark Regulations and Legal Constraints
Many brownstone neighborhoods are designated as “Historic Districts.” While this designation protects the property value by preventing unsightly new developments nearby, it also imposes strict (and expensive) requirements on renovations. Any exterior change—down to the color of the window frames—must often be approved by a Landmark Preservation Commission. The time delays associated with these approvals represent a “carry cost” that investors must bridge with liquid capital.
Financing and Tax Strategies for the Brownstone Investor
Financing a brownstone requires a different approach than a standard condo or suburban home. Because these properties often include rental units or mixed-use potential, lenders may view them through a commercial lens.
Leveraging Residential vs. Commercial Loans
If a brownstone has four units or fewer, it typically qualifies for residential financing, allowing for lower down payments and competitive fixed-rate mortgages. However, if the building has five or more units, it is classified as a commercial property. This requires a commercial loan, which usually carries higher interest rates, shorter terms, and requires a deeper dive into the building’s debt-service coverage ratio (DSCR). For the savvy investor, a building with 3-4 units is often the “sweet spot,” providing scale without the complexities of commercial lending.
Tax Advantages: Depreciation and Historic Credits
The IRS allows residential real estate investors to depreciate the value of the building (excluding the land) over 27.5 years. Given the high cost of brownstones, this annual depreciation can provide a massive “paper loss” that offsets the actual rental income, significantly reducing the owner’s tax liability.
Furthermore, certain renovations may qualify for Federal or State Historic Rehabilitation Tax Credits. These programs are designed to encourage the preservation of historic structures by offering a tax credit—not just a deduction—equal to a percentage of the “qualified rehabilitation expenditures.” This can effectively subsidize 20% or more of a major renovation project.
The 1031 Exchange
For those looking to build a real estate empire, the 1031 Exchange is a vital tool. An investor can sell a smaller asset (like a condo) and “roll” the capital gains into a brownstone without paying immediate taxes on the profit. This allows for the compounding of wealth through larger and more prestigious assets over time.

Conclusion: The Brownstone as a Wealth-Building Vehicle
Investing in a brownstone apartment is a sophisticated financial move that combines the stability of historic real estate with the cash-flow potential of urban multi-family housing. While the barriers to entry are high—including significant purchase prices, specialized maintenance requirements, and complex regulatory environments—the rewards are equally substantial.
A brownstone is not merely a place to live; it is a tangible piece of history that functions as a high-performance asset. For the investor who understands the nuances of restoration, the strategies of rental yield, and the advantages of tax-efficient financing, the brownstone remains one of the most reliable and prestigious ways to build and preserve generational wealth in the modern economy. Whether held as a single-family trophy asset or a multi-unit income stream, the brownstone stands as a testament to the enduring value of quality, scarcity, and architectural integrity.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.