
Every year, millions of brand-new vehicles roll off assembly lines and onto dealership lots across the globe. For the automotive industry, the goal is a seamless transition from manufacturer to consumer. However, the reality of the market—fluctuating interest rates, shifting consumer preferences, and economic downturns—means that a significant percentage of inventory often remains stationary as the next model year begins to arrive.
From a business finance perspective, a car sitting on a lot is not just a missed opportunity; it is a depreciating asset that incurs daily carrying costs. Understanding what happens to these unsold vehicles requires a deep dive into the complex financial ecosystems of floorplan financing, manufacturer incentives, and secondary liquidation markets.
The Financial Burden of Stagnant Inventory
To understand why dealerships are so desperate to move metal, one must first understand how they pay for their inventory. Very few dealerships actually own the cars on their lots. Instead, they rely on a specialized type of business loan known as floorplan financing.
Floorplan Financing and Interest Accumulation
Floorplan financing is a revolving line of credit that allows dealers to borrow against their inventory. When a car is delivered from the factory, the lender (often the financial arm of the manufacturer, such as Ford Credit or Toyota Financial Services) pays the manufacturer for the vehicle. The dealer then pays interest on that loan for every day the car remains unsold.
In a high-interest-rate environment, the “holding cost” of a single vehicle can reach hundreds of dollars per month. If a dealership has 500 cars sitting for 90 days, the interest expense alone can threaten the business’s quarterly margins. This financial pressure is the primary driver behind the aggressive sales tactics seen at the end of fiscal months and quarters.
The Depreciation Curve of New Assets
In the world of accounting, a new car is a unique asset. Unlike real estate, which may appreciate, or raw materials, which might hold their value, a vehicle begins to lose value the moment it is manufactured, and its value drops precipitously the moment a newer model year is released.
Once a 2024 model sits next to a 2025 model, its “book value” in the eyes of lenders and consumers drops significantly. For a dealership, this creates a race against time. If a vehicle sits for more than 120 days, it is often considered “stale,” and the financial strategy shifts from making a profit to mitigating a loss.
Strategies for Liquidation and Movement
When a vehicle fails to sell to a retail customer within the expected timeframe, the manufacturer and the dealer enter a collaborative phase of loss mitigation. This involves a variety of financial levers designed to make the asset more attractive or to move it to a different market.
Manufacturer Incentives and “Trunk Money”
The first line of defense is the use of manufacturer-to-consumer incentives. These include 0% APR financing, cash-back rebates, and specialized lease deals. However, there is also a “hidden” financial layer known as “trunk money” or dealer incentives.
Trunk money is a confidential payment from the manufacturer to the dealer for every unit sold of a specific slow-moving model. For example, if a certain SUV isn’t moving, the manufacturer might offer the dealer a $3,000 bonus for every unit sold. This allows the dealer to drop the price below their actual invoice cost while still maintaining a slim profit margin or breaking even.
Dealer-to-Dealer Trades and Regional Allocation
Not every market has the same demand. A rear-wheel-drive convertible may sit unsold for six months in a snowy New England winter while being in high demand in Southern California. Dealerships frequently engage in “dealer trades,” where they swap stagnant inventory with other franchises in different geographic regions.
While this involves transportation costs, it is often more cost-effective than continuing to pay floorplan interest on a vehicle that has zero local demand. This regional arbitrage is a vital part of inventory management in the corporate automotive world.
Fleet Sales and Corporate Leasing
If retail demand remains low, manufacturers often pivot to fleet sales. This involves selling large batches of unsold inventory to rental car agencies (like Hertz or Enterprise), government entities, or large corporate entities.
While fleet sales occur at a significant discount compared to retail prices, they allow manufacturers to clear massive amounts of inventory at once, maintaining the “velocity” of the production line. From a business finance standpoint, selling 5,000 units at a 20% discount is often preferable to having those 5,000 units slowly depreciate on dealer lots for a year.
The Auction Circuit and Secondary Markets
When all retail and fleet efforts fail, the vehicle enters the secondary market. This is the final stage for “new” cars that have never been titled but are no longer viable for the primary showroom floor.
Closed vs. Open Auctions
Unsold inventory is frequently sent to automotive auctions. There are two tiers to this process. The first is “closed auctions,” which are restricted to franchised dealers of that specific brand. Here, a BMW dealer might buy unsold units from another BMW dealer to bolster their own used car inventory.
If the cars don’t sell at closed auctions, they move to “open auctions” (such as those run by Manheim or ADESA), where any licensed dealer can bid. At this stage, the car is often sold for its wholesale value, which can be thousands below the original MSRP.
The Role of Certified Pre-Owned (CPO) Programs
A clever financial maneuver used by dealerships involves “punching” the warranty on a stale new car. The dealer officially registers the car as a “demonstrator” or a service loaner. By doing this, the car is technically no longer “new” in the eyes of the manufacturer’s accounting.
The dealer then places the car back on the lot as a “Certified Pre-Owned” (CPO) vehicle. Ironically, these vehicles can sometimes be more attractive to buyers because they come with an extended warranty and a significantly lower price point, despite having only a few dozen miles on the odometer. This allows the dealership to move the asset while utilizing different marketing budgets and financial incentives.
Tax Implications and Financial Write-Offs
From a corporate accounting perspective, the way a company handles unsold inventory can have massive implications for its year-end tax liabilities.
Inventory Tax and “Lower of Cost or Market”
In many jurisdictions, businesses are taxed on the value of the inventory they hold at the end of the year. This is known as an inventory tax. To minimize this liability, accountants use the “Lower of Cost or Market” (LCM) method. If the market value of a car has dropped below the price the dealer paid for it, they can write down the value of that inventory on their balance sheet. This creates a paper loss that can be used to offset profits elsewhere, reducing the overall tax burden.
The Myth of the “Car Graveyard”
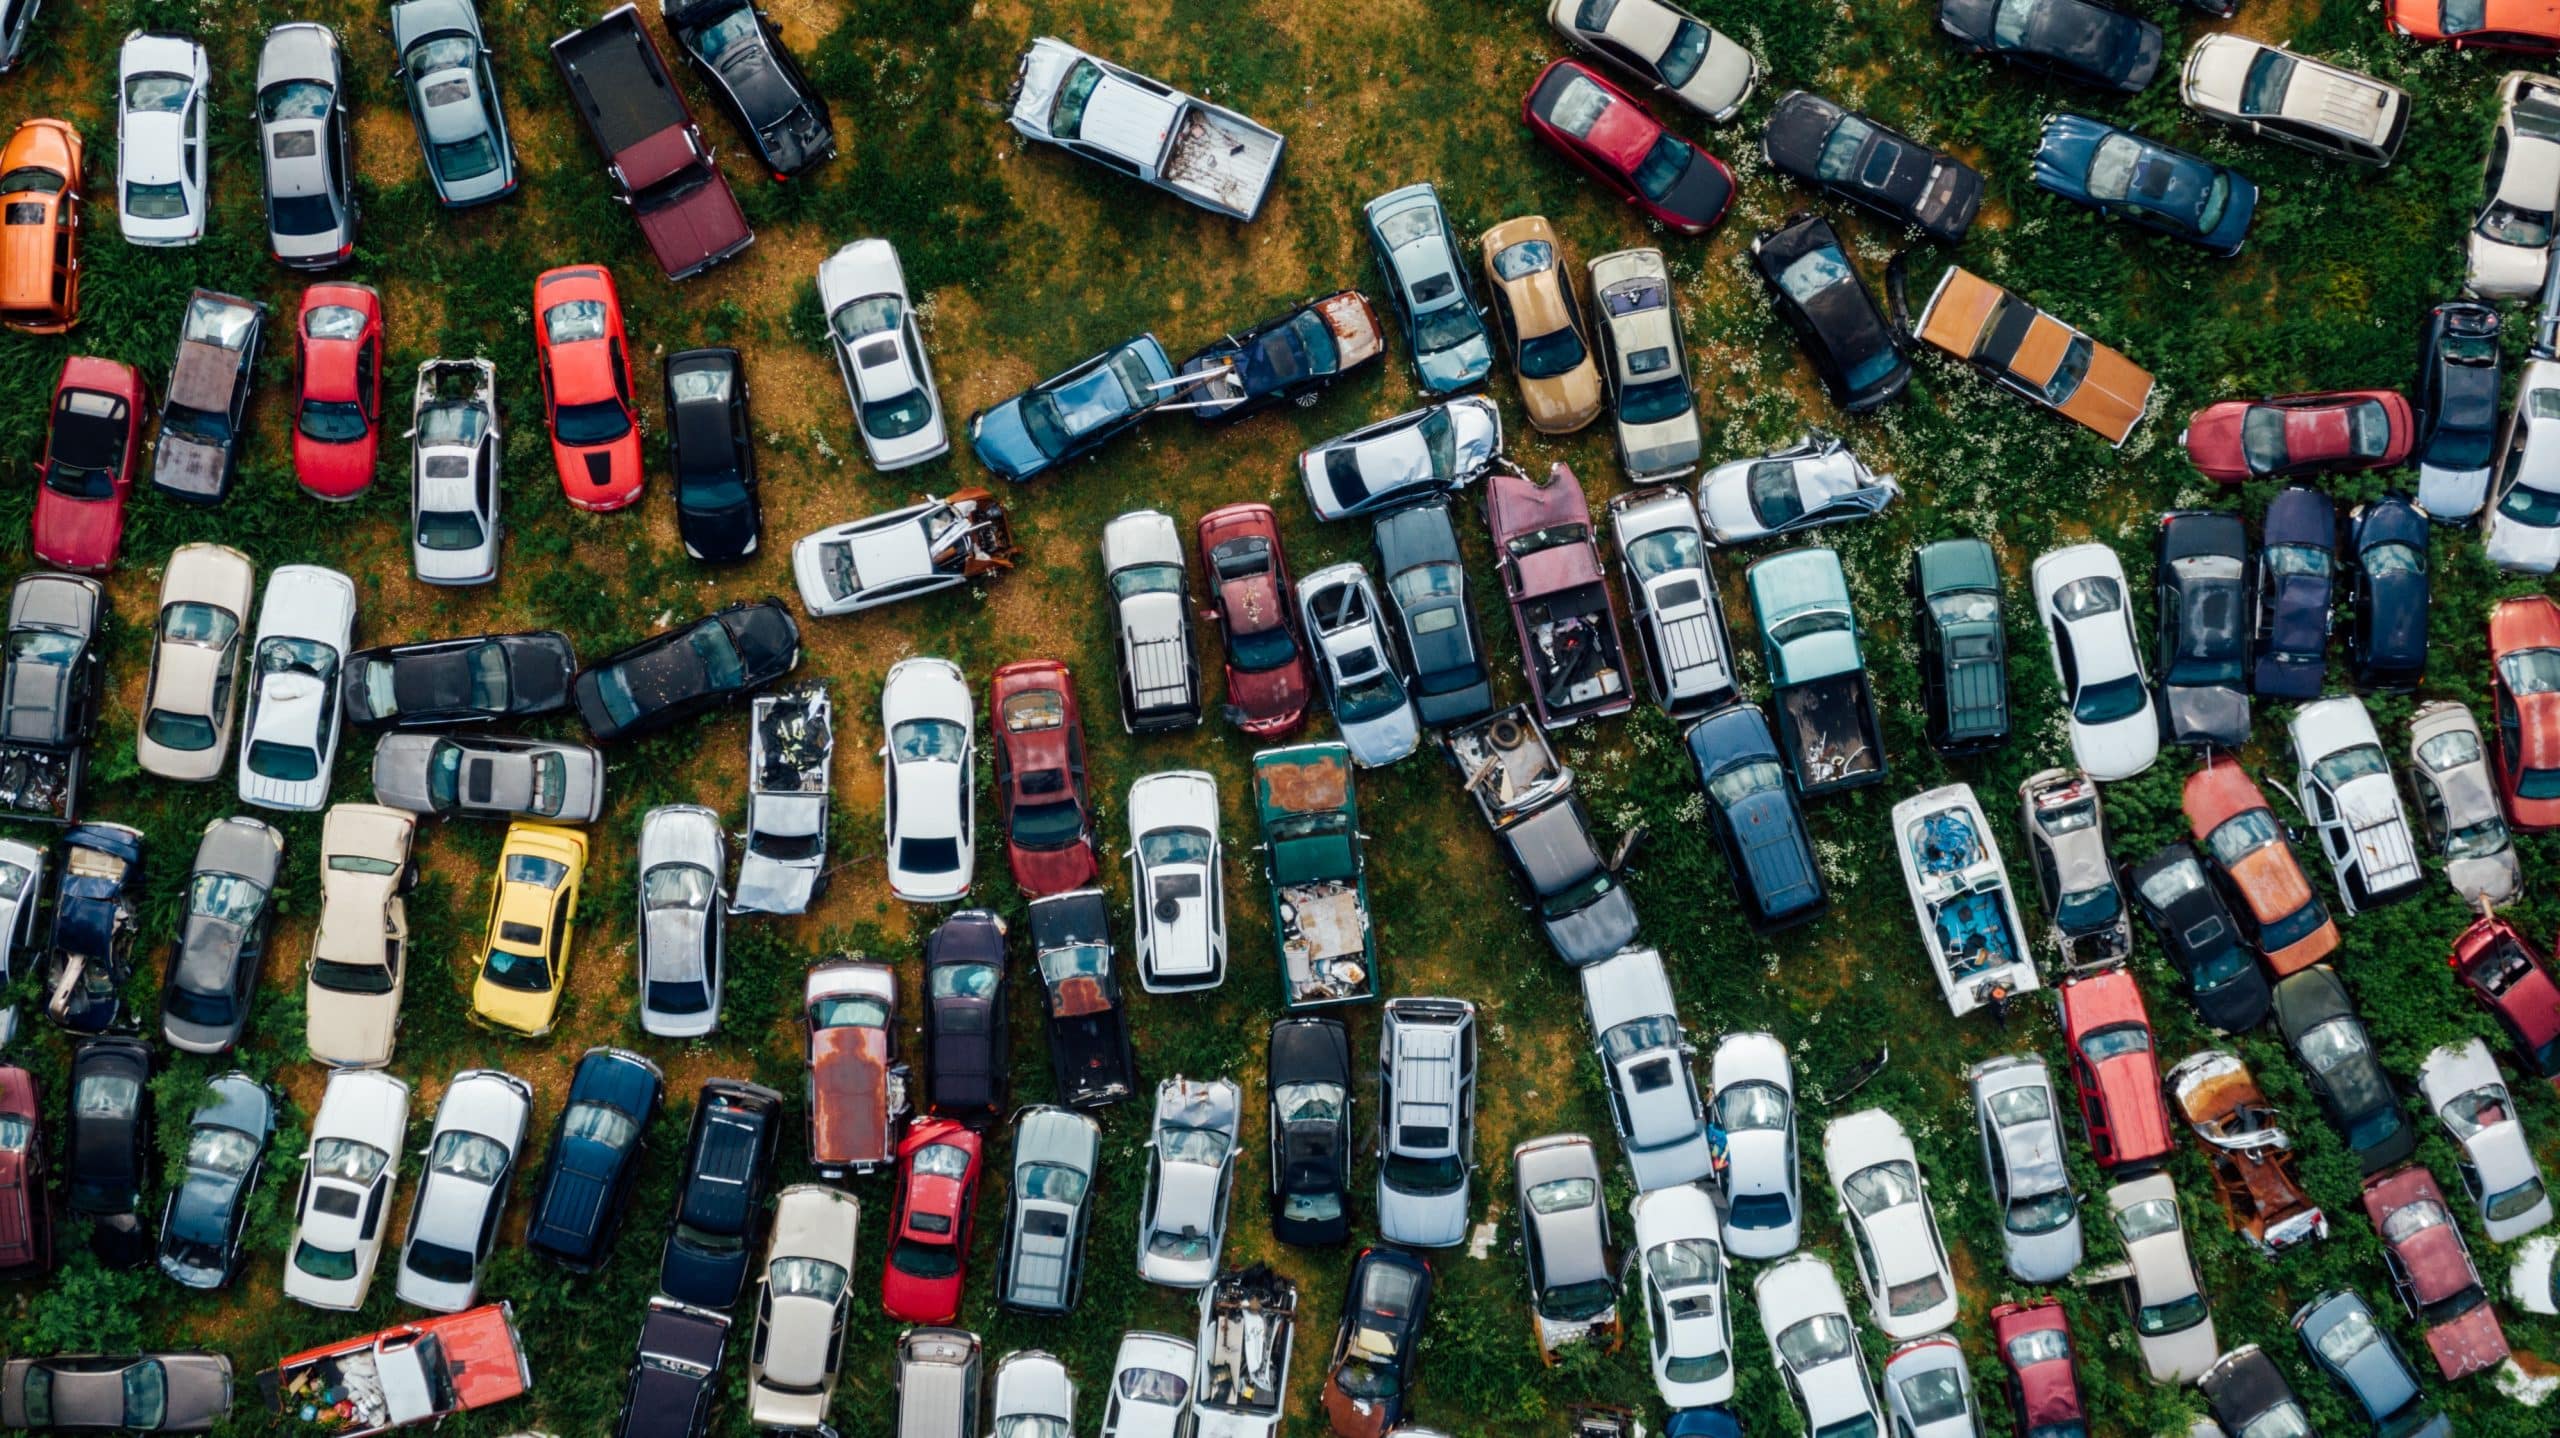
There is a common viral myth that manufacturers have “secret graveyards” where thousands of unsold cars are left to rot in giant fields. While photos of such lots exist, the context is usually misrepresented. These lots are typically temporary staging areas for vehicles awaiting parts (common during the semiconductor shortage), vehicles waiting for shipment to international markets, or vehicles involved in massive recalls (such as the Volkswagen “Dieselgate” scandal).
In the modern lean-manufacturing era, no company can afford to let a $40,000 asset rot. The cost of capital is too high. If cars are sitting in a field, it is almost always a temporary logistical bottleneck rather than a permanent solution for unsold stock.
The Pivot to Build-to-Order and Lean Inventory
The financial pain of unsold inventory during the 2008 financial crisis and the 2020 supply chain disruptions has led to a fundamental shift in how the automotive industry handles production.
Moving Away from the “Push” Model
Traditionally, the automotive industry operated on a “push” model: factories produced as many cars as possible and pushed them onto dealers, regardless of immediate demand. This led to the massive year-end clearances and the “unsold car” problem.
Today, many brands are moving toward a “pull” model or “Build-to-Order” (BTO). By encouraging consumers to order their vehicles online and wait for delivery, manufacturers can keep inventory levels low. For the dealer, this reduces floorplan interest expenses. For the manufacturer, it reduces the need for heavy discounting and rebates.

The Future of Automotive Retail Finance
The rise of electric vehicles (EVs) and direct-to-consumer sales models (pioneered by companies like Tesla) is further changing the landscape. Without a traditional dealer network to “push” inventory to, manufacturers must be even more precise with their production data.
Ultimately, what happens to an unsold car is a testament to the efficiency of modern capitalism. The vehicle will eventually find a home, but its journey from a premium showroom floor to a discounted fleet vehicle or an auction block is a calculated series of financial maneuvers designed to squeeze every possible cent of value out of a depreciating asset. In the world of high-stakes automotive finance, the only thing more expensive than a car is a car that isn’t moving.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.