
In the landscape of modern finance and wealth management, the metaphors we use to describe asset behavior often dictate the strategies we employ. To the casual observer, a date and a fig might appear similar—both are sweet, dried fruits often found in the same section of the market. However, for the sophisticated investor, these two fruits represent two diametrically opposed philosophies of capital growth, risk management, and wealth preservation.
Understanding the difference between a “Date” strategy and a “Fig” strategy is essential for anyone looking to navigate the complexities of personal finance and portfolio construction. While one offers the high-energy, immediate gratification of rapid turnover, the other provides the deep-rooted, structural stability of long-term compounding. This article explores these two distinct financial archetypes, helping you determine which model best aligns with your fiscal objectives.
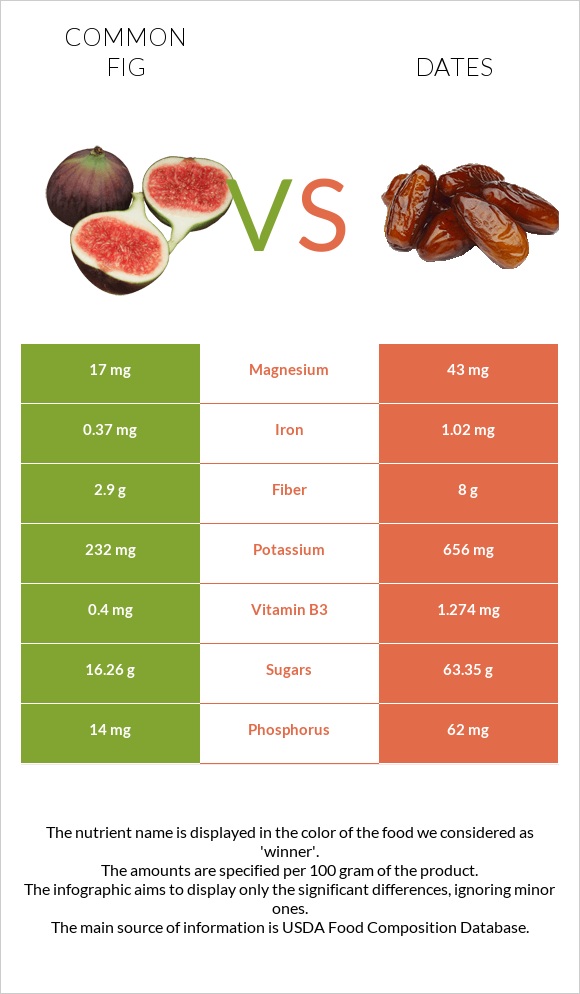
The Velocity of Value: Understanding the “Date” Asset Class
In the world of investing, the “Date” represents assets characterized by high energy, high density, and rapid maturity. Just as a date palm provides a concentrated burst of sugar and calories in a small package, Date-style investments are designed for speed and immediate utility. These are the instruments of the active trader, the high-yield seeker, and the liquidity-conscious professional.
High-Energy Yields and Liquidity
The primary characteristic of a Date asset is its concentration of value. In financial terms, this translates to high volatility paired with the potential for rapid price appreciation. Day trading, short-term options contracts, and high-frequency crypto-asset movements are the “Dates” of the financial world. They are compact, they mature quickly, and they provide the “sugar high” of immediate realized gains.
Liquidity is the hallmark of the Date strategy. Because these assets are often tied to specific “dates”—such as expiration dates, maturity dates, or earnings calls—they are designed to be consumed or rotated quickly. For an investor focused on cash flow or those operating in the “side hustle” economy, the Date model is attractive because it allows for the rapid recycling of capital. You enter a position, capture the spike in value, and exit before the asset loses its freshness or the market shifts.
The Risks of Short-Term Fermentation
However, the very sweetness that makes the Date strategy appealing also introduces significant risk. Just as a dried date has a specific shelf life before it loses its peak quality, short-term financial instruments are highly sensitive to timing. If you hold a “Date” asset too long, you risk the “fermentation” of your gains—where theta decay in options or a sudden market correction erodes the concentrated value you worked to build.
Furthermore, the Date strategy requires constant vigilance. It is a high-maintenance approach to money. Much like the intensive labor required to harvest dates from high palms, active trading and short-term debt management require a significant investment of time and intellectual capital. For many, the stress of managing a portfolio of “Dates” can lead to burnout, particularly when the market’s “harvest” doesn’t align with one’s personal financial needs.
The Architecture of Wealth: Investing in the “Fig” Model
If the Date is the asset of the moment, the “Fig” is the asset of the era. The fig tree is one of the most ancient cultivated species, known for its deep roots, complex internal flowering, and the ability to produce fruit for decades, if not centuries. In a financial context, the Fig strategy represents the “Buy and Hold” philosophy, value investing, and the construction of generational wealth.
Structural Growth and the Power of Compounding
The most fascinating aspect of the fig is its internal structure; the flowers are actually inside the fruit. Similarly, the value of a Fig-style investment is often hidden within its internal compounding mechanics. When you invest in a low-cost index fund, a piece of multi-family real estate, or a blue-chip dividend-growth stock, you aren’t looking for a quick sugar rush. You are investing in the “tree”—the underlying structure that produces value over time.
The Fig strategy relies on the eighth wonder of the world: compound interest. While a Date investor is focused on the price action of the day, the Fig investor is focused on the yield of the decade. The complexity of the “pollination” process for a fig (often involving a symbiotic relationship with specific wasps) mirrors the complex ecosystem of long-term wealth, which involves tax-advantaged accounts (like 401ks or IRAs), dividend reinvestment plans (DRIPs), and the steady appreciation of equity.
Resilience through Deep-Rooted Diversification
A fig tree can survive droughts and harsh conditions that would wither lesser plants because of its expansive root system. In your financial life, “Fig” assets serve as the bedrock of your portfolio. These are the assets that provide “fiber” to your financial diet—the stability that prevents your net worth from crashing during a market downturn.
Real estate is the quintessential Fig asset. It is illiquid, slow to mature, and requires patience, but it provides a physical foundation and a hedge against inflation that few “Date” assets can match. When the “sugar” of the tech market or the crypto-sphere runs dry, the Fig investor remains calm, knowing their roots reach deep into the tangible economy of housing, infrastructure, and established industry.
Strategic Synchronicity: Integrating Both Models for Maximum ROI
The most successful financial plans do not choose exclusively between the Date and the Fig; rather, they recognize the symbiotic relationship between the two. A diet consisting only of dates leads to a sugar crash; a diet consisting only of figs may lack the quick energy needed for immediate opportunities.
Portfolio Rebalancing and Seasonal Harvesting
A sophisticated approach to money management involves using the “Dates” to fund the “Figs.” For instance, a professional might use the high-yield profits from a successful side hustle or a short-term stock play (the Date) to pay down the principal on a rental property or to max out an index fund contribution (the Fig). This is the process of converting high-volatility energy into low-volatility structure.
Conversely, during periods of personal financial “winter” or early retirement, the “Fig” assets provide the sustenance needed when the “Date” market is too volatile to harvest. This balance ensures that you have the liquidity to capitalize on short-term market inefficiencies while maintaining a growing base of permanent wealth.
Identifying Your Financial Soil
The decision of how much of your portfolio to allocate to Dates versus Figs depends largely on your “soil”—your unique financial circumstances, age, and risk tolerance.
- The Early-Career Investor: Often has a “sandy” soil that can handle the heat of Date-style investing. With time on their side, they can afford the volatility of high-growth tech or active trading, using those quick wins to plant the first seeds of their Fig trees.
- The Mid-Career Professional: Requires a balanced grove. They need the “Dates” for current lifestyle expenses and “Figs” to ensure that their eventual exit from the workforce is funded by a mature, self-sustaining orchard.
- The Wealth Preserver: Focuses almost exclusively on the “Fig.” At this stage, the goal is not to find the next high-sugar spike but to ensure the trees continue to produce enough fruit to support the next generation.
Tax Implications and Fiscal Sustainability
A critical difference between the Date and the Fig lies in how the government views their harvest. In the realm of personal finance, “Dates” are often subject to short-term capital gains taxes, which can significantly eat into your net returns. Because the Date strategy involves frequent buying and selling, the “tax drag” can be substantial, requiring an even higher rate of return to justify the effort.
“Figs,” however, are the darlings of the tax code. Long-term capital gains rates are generally much lower than ordinary income rates. Furthermore, many Fig-style assets—like real estate or certain insurance products—offer depreciation benefits or tax-free growth. By holding an asset for the long term, you defer the “harvest tax,” allowing your wealth to compound on the government’s money. Understanding this distinction is often the difference between a high-income individual and a high-net-worth individual.
Navigating the Modern Market: Is Your Strategy a Date or a Fig?
As we move deeper into an era of digital assets and rapid market cycles, the lines between these two categories can sometimes blur. Is a high-growth SaaS stock a Date or a Fig? It depends on your horizon. If you are trading the earnings volatility, it’s a Date. If you believe in the fundamental shift of the global economy toward cloud computing and plan to hold for twenty years, it’s a Fig.
The danger in the modern market is “mis-categorization.” Many retail investors treat “Dates” as if they were “Figs,” holding onto speculative, high-volatility assets as they crash, under the mistaken belief that they are “investing for the long term.” Conversely, some treat “Figs” like “Dates,” panic-selling their index funds during a minor market correction and losing out on the very compounding that makes those assets valuable.
To master your money, you must be honest about what you are holding. Are you looking for the quick, concentrated energy of a Date? Or are you planting the complex, enduring legacy of a Fig? By recognizing the inherent differences in their maturity, risk profiles, and structural value, you can build a portfolio that is both sweet in the short term and nourishing for a lifetime. The difference isn’t just in the taste; it’s in the harvest.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.