
In the intersection of ethics, personal finance, and relational health, the concept of infidelity extends far beyond physical or emotional betrayal. When we examine the question of what a higher moral authority—often framed through the lens of stewardship and “God”—says about infidelity, we find a profound emphasis on the sanctity of covenants and the weight of transparency. In the world of money and personal finance, this manifests as “financial infidelity,” a breach of trust that can be just as devastating to a household’s economic stability as any other form of betrayal.
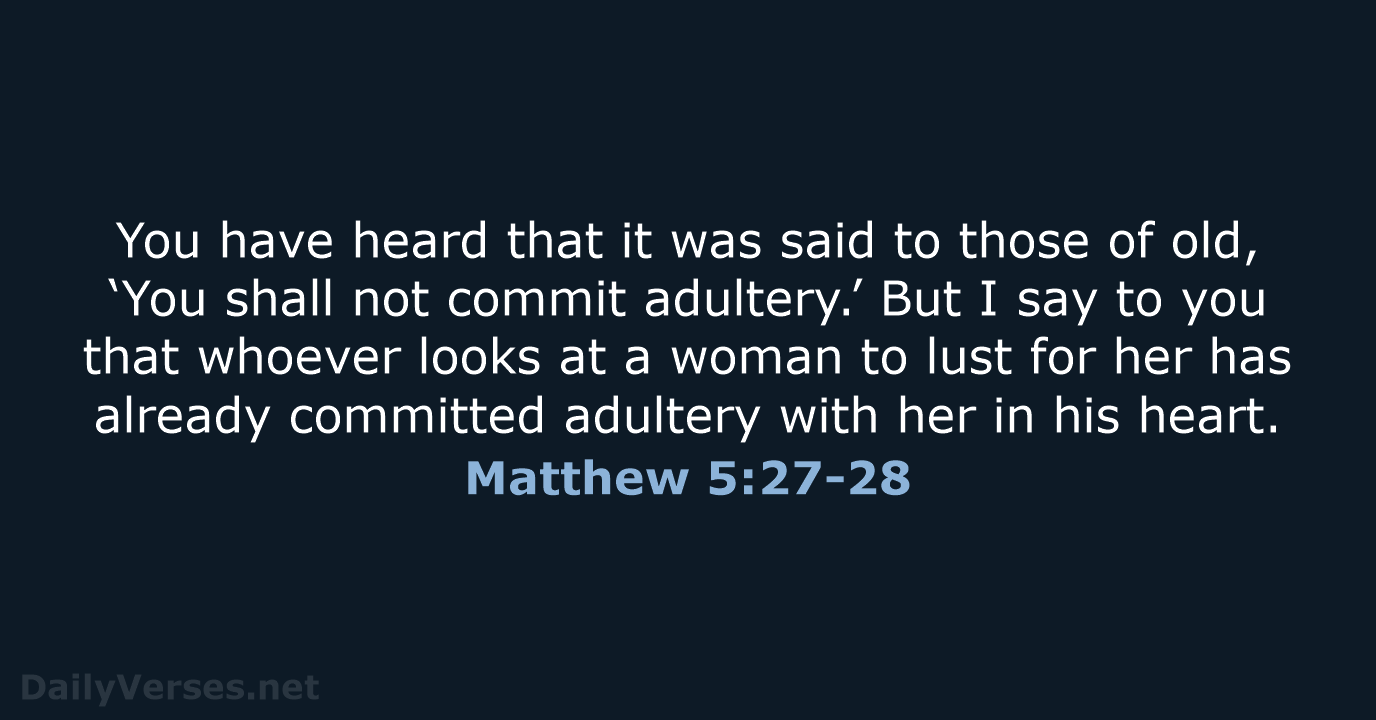
To understand the gravity of financial infidelity, one must look at money not merely as currency, but as a representation of a shared future and mutual commitment. Whether viewed through a theological lens of stewardship or a secular lens of fiduciary responsibility, infidelity in any form represents a fracture in the foundation of a partnership.
Understanding Financial Infidelity in the Modern Economy
Financial infidelity occurs when one partner in a committed relationship hides, lies about, or secretively manages money without the other’s knowledge. While it may start with a small, hidden purchase, it often escalates into secret credit cards, undisclosed debt, or even the siphoning of joint savings into private investments.
Defining the Breach of Trust
In the context of personal finance, trust is the ultimate asset. When we ask what moral frameworks suggest about infidelity, the answer is centered on the principle of truth. Financial infidelity is, at its core, a lie of omission. It violates the “unified front” required for effective wealth building and retirement planning. From an economic perspective, this lack of transparency introduces “information asymmetry” into a marriage or partnership, where one person makes decisions based on a false reality.
When a partner hides a side hustle or an online income stream, they are not just keeping cash; they are withholding the ability for the household to plan for contingencies. This behavior often mirrors the psychological patterns of traditional infidelity: secrecy, guilt, and a gradual distancing from the shared goals of the unit.
The Growing Trend of Secret Accounts
With the rise of digital banking and fintech apps, it has never been easier to commit financial infidelity. Digital wallets, cryptocurrency exchanges, and “buy now, pay later” services allow individuals to facilitate spending and investing away from the eyes of a spouse or partner. Studies indicate that nearly 40% of adults in committed relationships have committed some form of financial deception.
From a money management perspective, these secret accounts are “black holes” in a household budget. They prevent accurate tracking of the debt-to-income ratio and can lead to sudden, catastrophic realizations when a mortgage application is denied or a debt collector calls the home. The moral weight of this secrecy is heavy; it replaces a collaborative spirit with a competitive or defensive posture.
The Stewardship Principle: A Moral Perspective on Shared Assets
Many theological and ethical systems treat money as a tool for which we are held accountable. This is often referred to as “stewardship.” If we consider the moral guidance on infidelity, it often points toward the idea that we do not “own” our resources in a vacuum; rather, we manage them for the benefit of our families and our future. Infidelity, therefore, is a failure of stewardship.
Transparency as a Financial Virtue
In the realm of personal finance and investing, transparency is more than a moral choice; it is a strategic advantage. Couples who practice “radical transparency” regarding their bank accounts, investments, and side hustles often see higher rates of net worth growth. This is because shared knowledge allows for better risk management and the optimization of tax-advantaged accounts.
When one hides money, they are effectively betting against their partner. They are prioritizing individual security or pleasure over the collective health of the household. A moral approach to money suggests that “what belongs to one, belongs to both,” creating a system where every dollar is assigned a purpose that aligns with shared values.
The Consequences of Financial Secrecy
The repercussions of breaking this financial covenant are manifold. Beyond the emotional trauma, the economic fallout includes:
- Compounded Interest on Secret Debt: Hidden credit card balances often carry high interest rates that compound over time, eroding the couple’s total buying power.
- Missed Opportunity Costs: Money spent in secret is money that is not being invested in a 401(k), an Index Fund, or a college savings plan.
- Tax and Legal Liability: If a partner hides income or engages in unethical financial side hustles, the other partner may be held legally liable for back taxes or fraud penalties in a joint filing.
The Economic Cost of Relational Betrayal
Infidelity, whether romantic or financial, carries a steep price tag. When we look at the data surrounding divorce and separation, the leading cause is frequently cited as “money issues,” which is often a euphemism for a lack of transparency and a breach of trust.
Legal Ramifications and Divorce Settlements
When a relationship ends due to infidelity, the financial settling of accounts is rarely clean. In many jurisdictions, the discovery of hidden assets or “wasteful dissipation” of marital funds—where one partner spends significant joint money on an affair or a secret habit—can lead to an unequal distribution of assets during a divorce.
The cost of litigation to uncover hidden bank accounts or offshore investments can reach tens of thousands of dollars. Forensic accountants are often brought in to trace digital footprints and audit years of financial records. This process drains the very wealth that the couple spent years trying to build, leaving both parties in a significantly worse financial position than if they had remained faithful and transparent.
Rebuilding Credit and Capital After Infidelity
For the “betrayed” partner, the financial aftermath of infidelity often involves a period of intense repair. If a spouse has run up secret debt in joint names, the other spouse’s credit score may be decimated. Rebuilding this credit requires years of disciplined financial behavior and the use of specific financial tools like secured credit cards and credit-builder loans.
Furthermore, the loss of shared capital means that retirement timelines are often pushed back. The “divorce penalty” is a well-documented economic phenomenon where the split of a single household into two results in higher per-capita living expenses, reduced economies of scale, and a loss of tax efficiencies.
Strategies for Re-establishing Financial Faithfulness
If a partnership is to survive a breach of trust, it requires a complete overhaul of how money is handled. This transition from secrecy to transparency is the financial equivalent of a moral “redemption.”
Implementing Radical Transparency Tools
Modern technology, which once made hiding money easy, can now be used to enforce honesty. Couples recovering from financial infidelity often turn to shared financial apps and tools to rebuild trust:
- Consolidated Budgeting Apps: Using software like You Need A Budget (YNAB) or Monarch Money allows both partners to see every transaction in real-time.
- Credit Monitoring Services: Both partners can sign up for services like Credit Karma or Experian to provide mutual alerts on any new accounts opened in their names.
- Joint Investment Portfolios: Moving individual brokerage accounts into joint accounts ensures that all investment decisions—from stock picks to asset allocation—are made with mutual consent.
The Role of Financial Coaching in Recovery
Just as couples seek counseling for emotional infidelity, “financial therapy” or professional financial coaching is essential for recovering from money-related betrayals. A neutral third party can help the couple navigate the complex emotions of guilt and resentment while setting up a rigorous technical framework for money management.
This process involves setting clear boundaries for “fun money” (individual discretionary spending) versus “household money.” By creating a system where a small, agreed-upon amount of money is private, the urge to hide larger purchases is often mitigated. This honors the need for some individual autonomy while maintaining the integrity of the shared financial covenant.
Rebuilding Wealth Through Shared Goals
The final stage of moving past infidelity is the alignment of future financial goals. When a couple begins to invest together—whether in real estate, the stock market, or a joint business venture—they move from a state of “financial defense” to “financial offense.”
The wisdom found in moral teachings about faithfulness reminds us that a house divided cannot stand. In personal finance, this means that the most powerful tool for wealth creation is not a specific stock pick or a high-yield side hustle, but the unified strength of two people working toward a common vision. When transparency is restored, the “God-eye view” of one’s finances becomes one of pride and security rather than fear and concealment. Infidelity may break the foundation, but through rigorous honesty and the strategic use of financial tools, a more resilient and prosperous structure can be built.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.