
The moment the Powerball drawing concludes, millions of Americans instinctively reach for their tickets, checking each digit in hopes of a life-altering windfall. While the immediate search for “what was the Powerball winning numbers tonight” is driven by adrenaline and the dream of sudden wealth, the reality of the lottery is deeply rooted in the complex worlds of personal finance, probability, and wealth management. Whether you held the winning combination or are simply curious about the mechanics of the game, understanding the financial architecture behind those numbers is essential for anyone navigating the landscape of high-stakes windfalls.
Understanding the Financial Mechanics of the Powerball
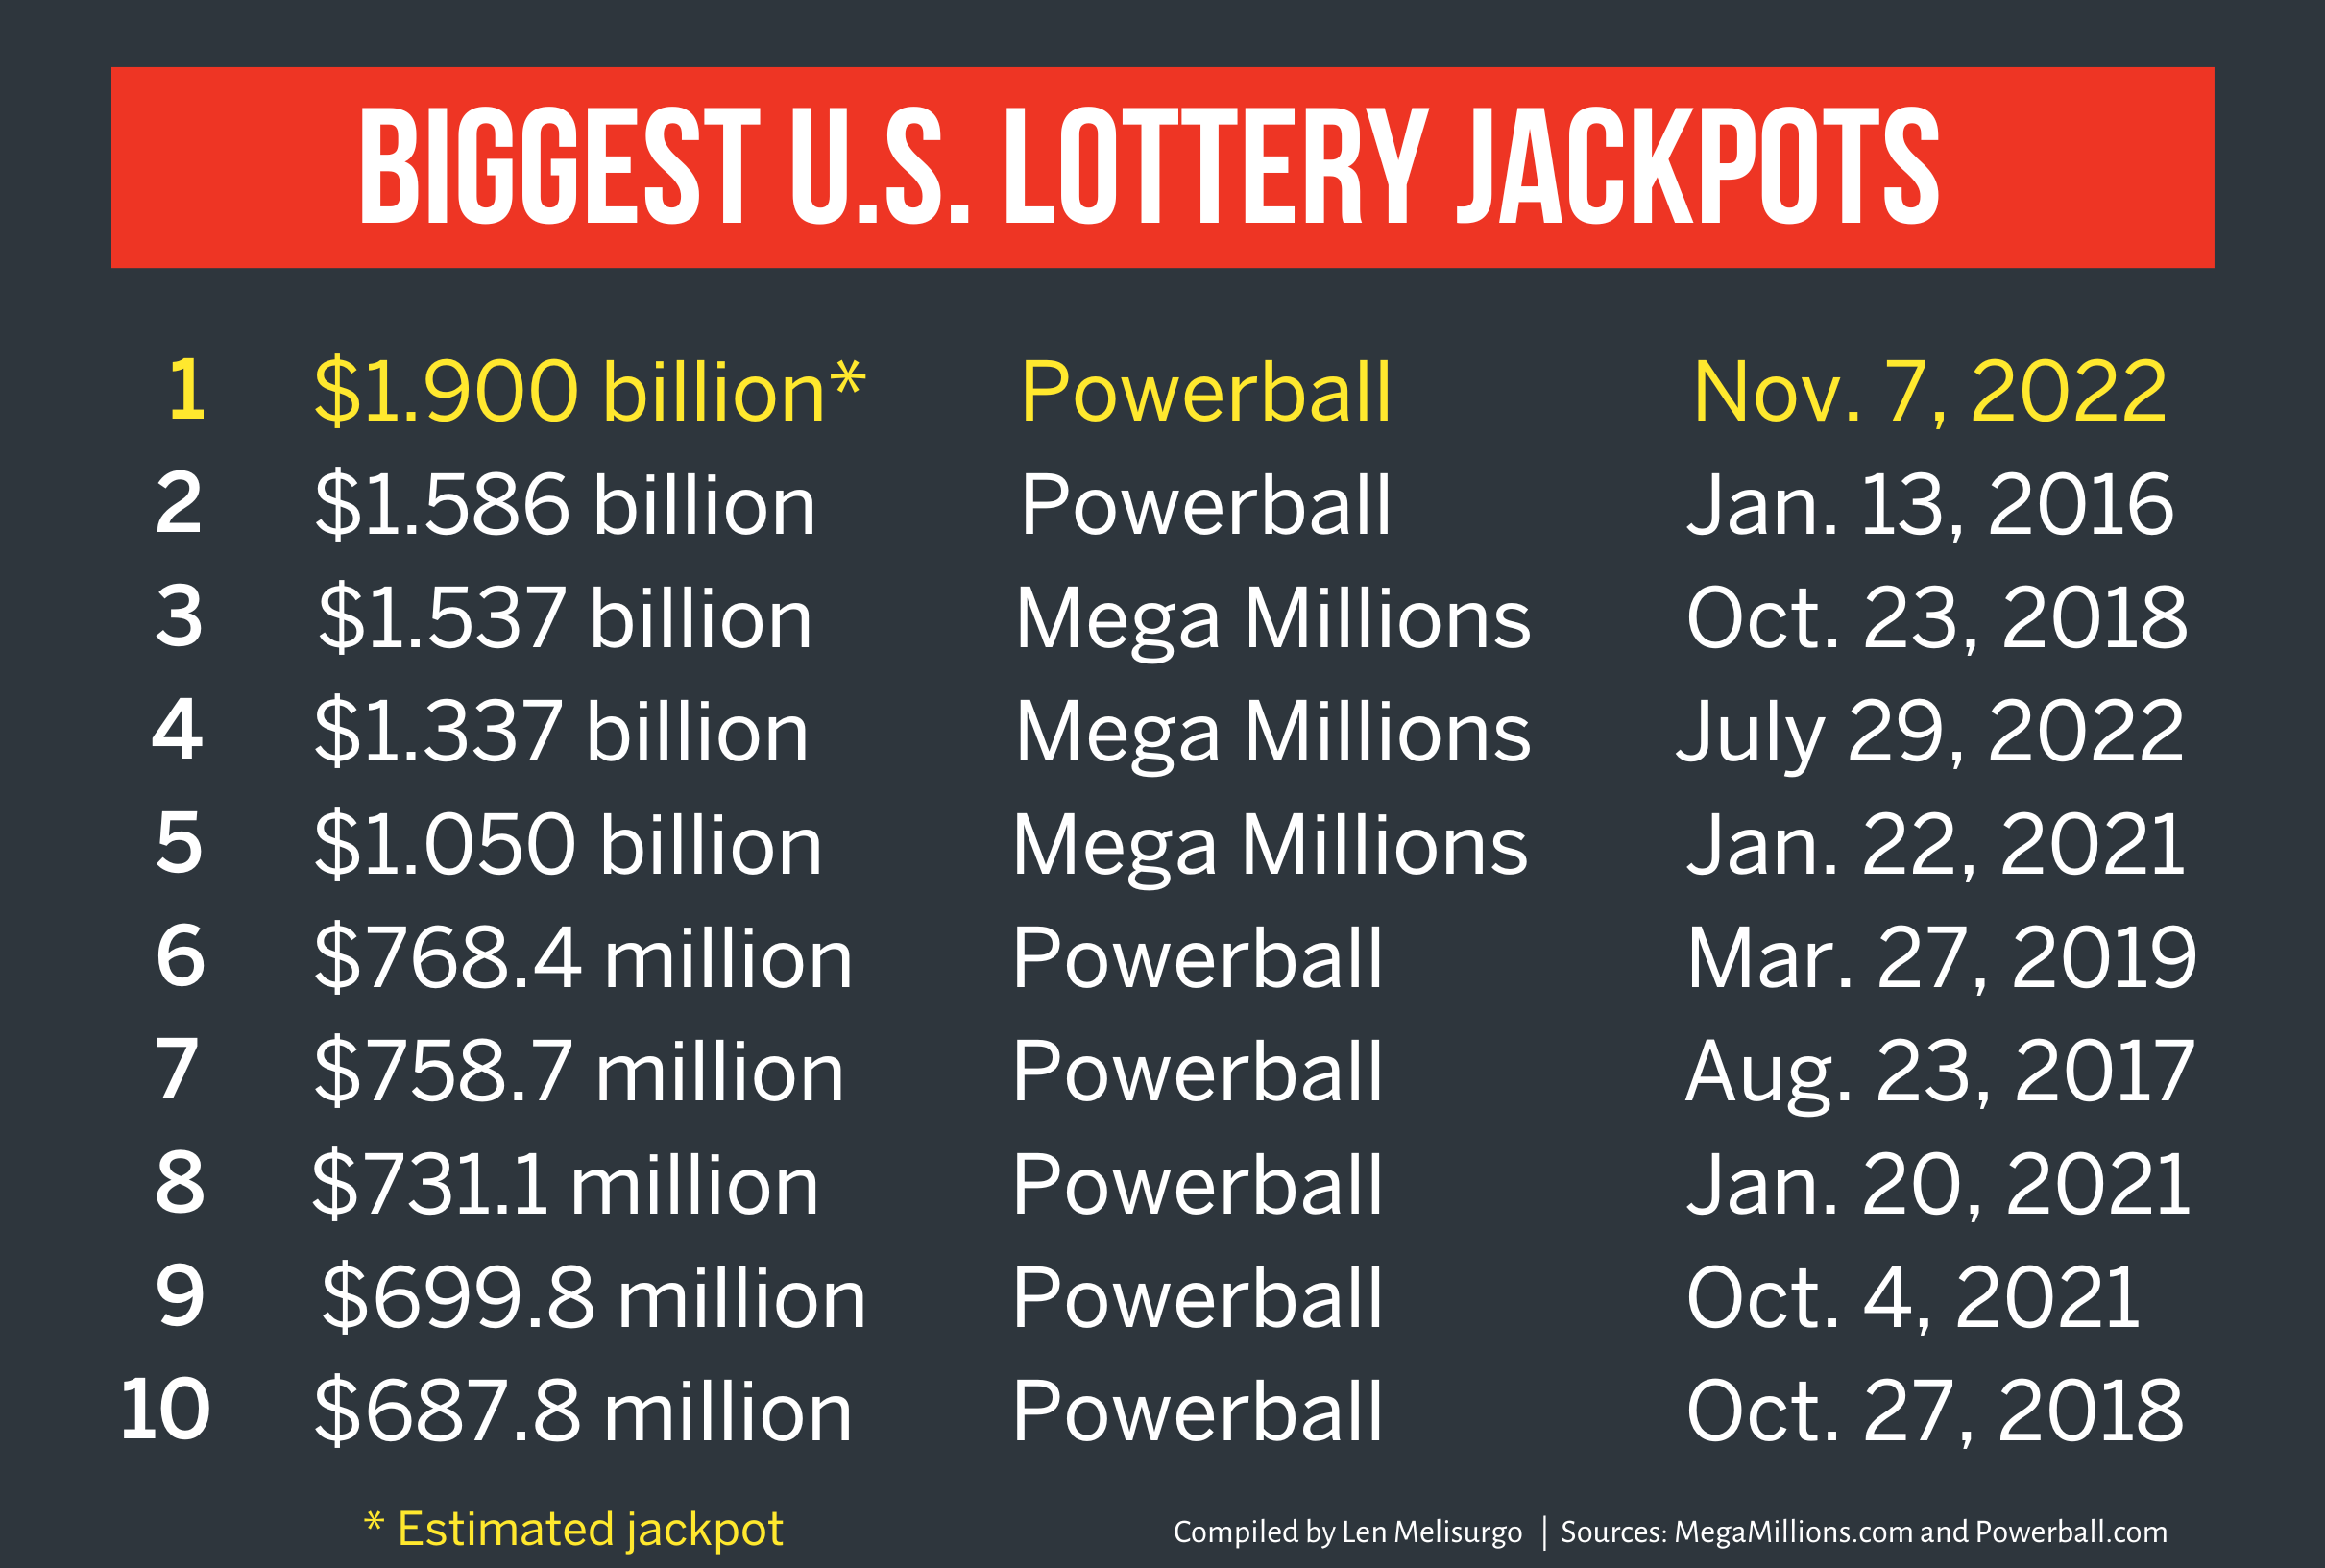
The Powerball is more than just a game of chance; it is a massive financial engine governed by strict mathematical laws and economic principles. When a player looks for the winning numbers, they are essentially looking for the key to a complex financial instrument. The jackpot often reaches hundreds of millions—and occasionally billions—of dollars, but the “sticker price” of the winning numbers is rarely what the winner takes home in liquid capital.
The Odds and the Mathematical Reality
To understand the value of the numbers drawn tonight, one must first respect the sheer improbability of the event. The odds of matching all five white balls and the red Powerball are approximately 1 in 292.2 million. From a personal finance perspective, playing the lottery is often criticized as a “tax on those who are bad at math,” but for many, it serves as a low-cost entry into a high-variance dream. However, the true financial professional looks at the Powerball through the lens of expected value. Because the odds are so long, the expected value of a $2 ticket typically remains negative unless the jackpot exceeds a certain threshold—often cited around $500 million—and even then, the potential for multiple winners splitting the prize can dilute that value significantly.
Cash Option vs. Annuity: The Wealth Preservation Debate
When those winning numbers align with your ticket, the first and most critical financial decision arises: the choice between the 30-year annuity and the one-time lump sum (cash option).
The annuity option provides the winner with 30 graduated payments over 29 years, with each payment increasing by 5% to account for inflation and cost-of-living adjustments. This is often the safer route for individuals without extensive financial management experience, as it prevents the “all-at-once” spending spree that has historically led many winners to bankruptcy.
Conversely, the cash option provides the net present value of the jackpot in a single payment. From an investment standpoint, the lump sum is often preferred by those who believe they can achieve a higher rate of return through diversified market investments than the internal rate of return offered by the lottery’s annuity structure. In the current economic climate, where interest rates and market volatility are high, the decision between these two options requires a deep dive into discounted cash flow analysis and tax trajectory projections.
Strategic Tax Planning for Sudden Wealth
Finding that your numbers match tonight’s drawing is only the beginning of a long journey with the Internal Revenue Service (IRS). The transition from a regular earner to a high-net-worth individual happens in the seconds it takes to verify those digits, and the tax implications are immediate and substantial.
Federal and State Tax Obligations
The moment a large lottery prize is claimed, the federal government takes a significant cut. Currently, the IRS requires a mandatory 24% federal withholding on gambling winnings of this magnitude. However, this is rarely the final tax bill. Since the top federal income tax bracket is 37%, a winner will likely owe an additional 13% when filing their year-end returns.
Furthermore, state taxes play a pivotal role in the actual take-home pay. States like Florida, Texas, and Washington do not tax lottery winnings at the state level, providing a massive financial advantage to residents. In contrast, winners in states like New York or New Jersey may face an additional 8% to 10% in state taxes. When checking the winning numbers, a resident of a high-tax state must mentally discount the jackpot by nearly half to arrive at a realistic figure for their personal balance sheet.
Building a Professional Financial Dream Team
No individual, regardless of their financial literacy, should navigate a Powerball win alone. The first step after confirming the winning numbers is not to sign the ticket (in some jurisdictions) or rush to the lottery office, but to assemble a “dream team” of advisors. This team typically includes:
- A Tax Attorney: To navigate the complex interplay between state and federal laws and to explore the possibility of claiming the prize through a trust to maintain anonymity.
- A Certified Public Accountant (CPA): To manage the immediate tax liabilities and plan for future filings.
- A Fee-Only Financial Planner: To create a long-term investment strategy that focuses on capital preservation rather than just growth.
- An Estate Lawyer: To update wills, establish trusts, and ensure that the wealth can be transferred to future generations without being decimated by estate taxes.
Managing a Windfall: Personal Finance Fundamentals
If the numbers tonight have made you a multi-millionaire, the rules of personal finance do not disappear; they simply scale. The management of a massive windfall requires more discipline than the management of a standard paycheck.
The Immediate Action Plan: Protecting Your Ticket
The physical or digital ticket containing the winning numbers is a “bearer instrument,” meaning that in many cases, whoever holds the ticket owns the prize. Financial experts recommend immediately making a copy of the ticket, placing the original in a safe deposit box, and consulting with legal counsel before even signing the back. In some states, signing the ticket prevents you from claiming it through a trust, which might be your only path to remaining anonymous and avoiding the inevitable influx of requests for money from “long-lost” relatives and predatory “investors.”
Debt Elimination and Asset Allocation
The first prudent move with any windfall is the elimination of high-interest debt. While a Powerball winner may have enough money to ignore a credit card balance, the psychological and financial freedom of being debt-free is a cornerstone of sound wealth management.
Once debt is cleared, the focus shifts to asset allocation. A standard “60/40” portfolio (60% stocks, 40% bonds) might be too aggressive or too conservative depending on the winner’s age and goals. For someone who has just won $100 million, the primary goal is often “not losing it” rather than “doubling it.” This involves diversifying into low-cost index funds, municipal bonds for tax-advantaged income, and perhaps institutional-grade real estate.
The Psychology of Money and the Lottery Effect
The search for the winning numbers is often a search for freedom, but without a firm grasp of behavioral finance, that freedom can be short-lived. The “lottery curse” is a well-documented phenomenon where winners return to their original financial state—or worse—within a few years.
Avoiding the “Lottery Curse”
Behavioral finance suggests that sudden wealth can lead to “lifestyle creep” on a massive scale. When the numbers tonight align in your favor, the brain’s reward system is flooded with dopamine, which can impair long-term decision-making. The most successful winners are those who implement a “cooling-off period”—a six-month to one-year window where they make no major purchases (no houses, no cars, no yachts) and no major life changes (quitting a job or getting a divorce). This allows the emotional volatility of the win to subside, enabling the winner to make decisions based on logic rather than impulse.
Sustainable Philanthropy and Legacy Building
For many, the ultimate goal of winning the Powerball is to help others. However, without a structured approach, charitable giving can quickly drain a fortune. Establishing a Donor-Advised Fund (DAF) or a private foundation allows a winner to manage their philanthropy professionally. These structures provide immediate tax deductions while allowing the principal to be invested and grown, ensuring that the impact of the winning numbers tonight can be felt for decades or even centuries.
In conclusion, while the immediate interest in the Powerball winning numbers tonight is a matter of curiosity and excitement, the implications of those numbers are a masterclass in high-level finance. From tax mitigation and legal structures to asset allocation and psychological resilience, managing a lottery win is a full-time job that requires a sophisticated understanding of how money works in the modern world. Whether you are a winner or a dreamer, the principles of wealth management remain the same: protect your capital, plan for the taxman, and always prioritize long-term stability over short-term gratification.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.