
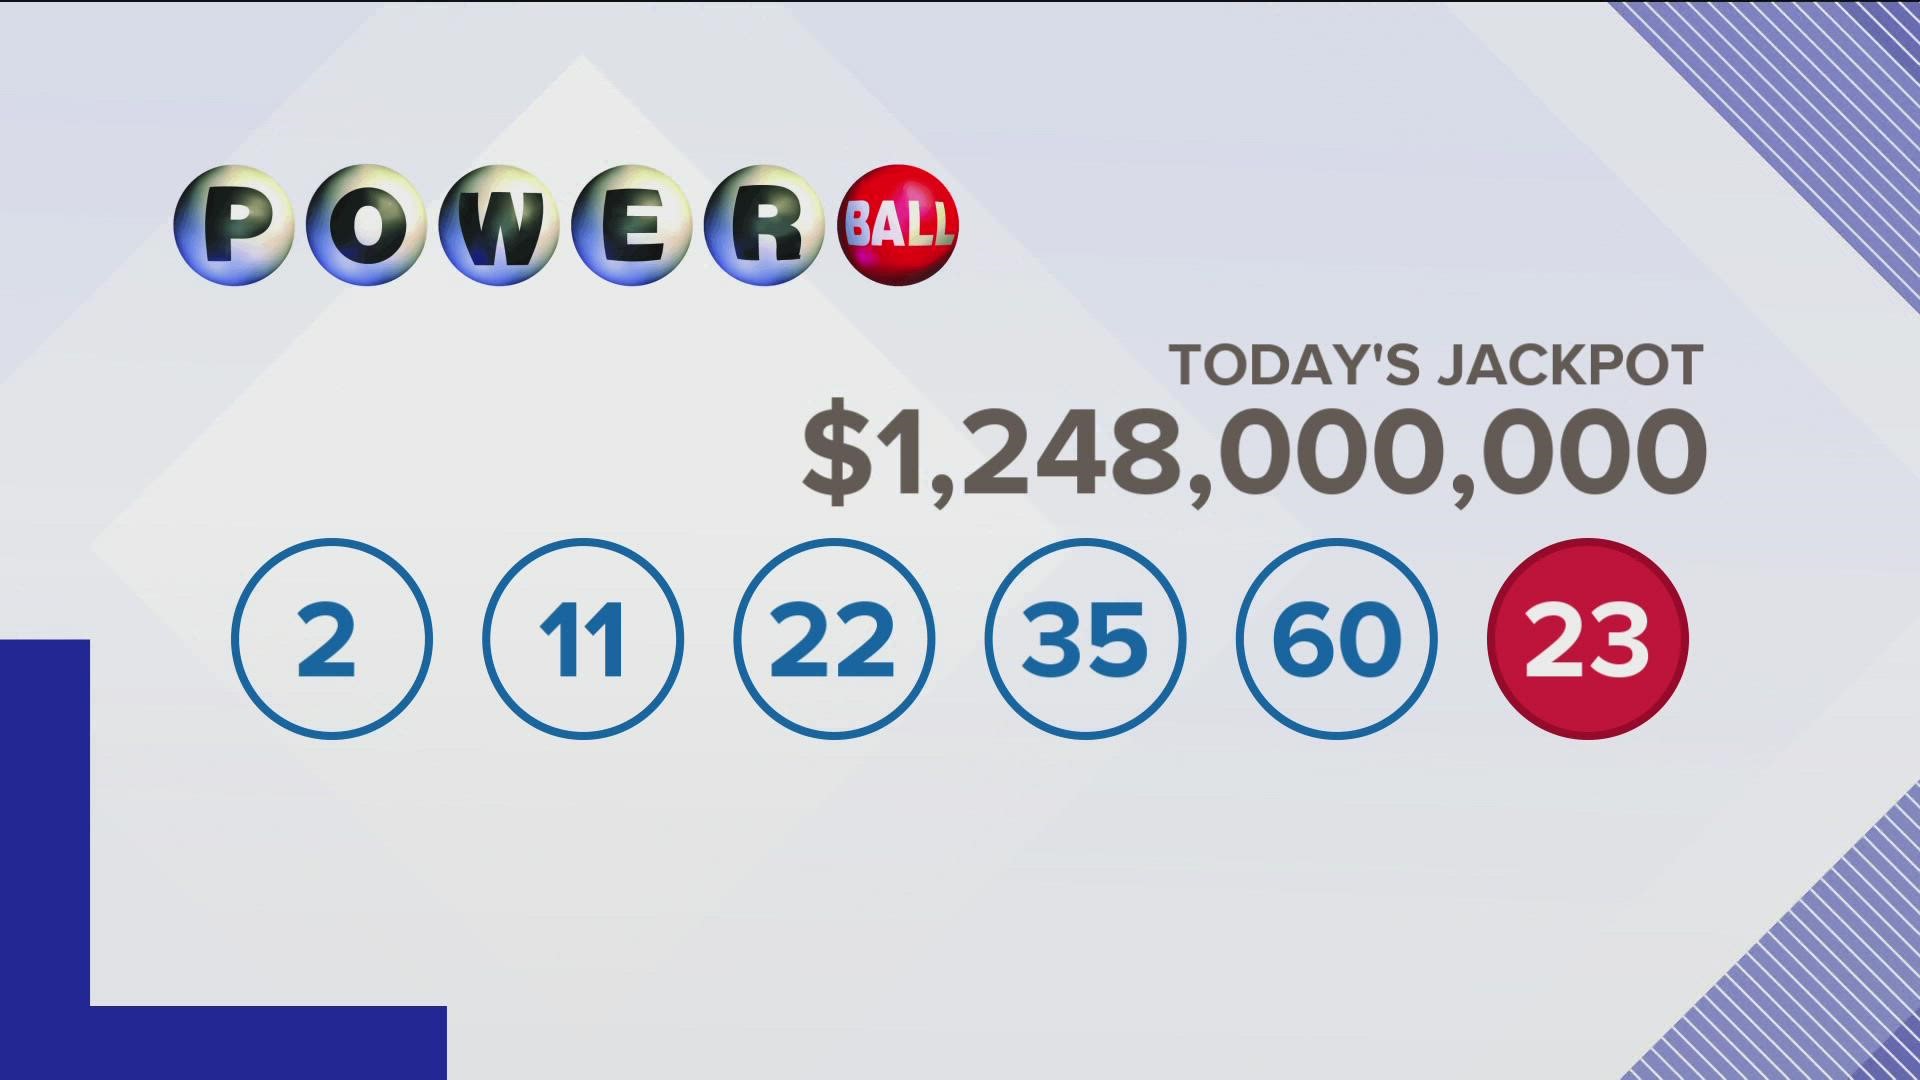
The ritual of checking the Powerball winning numbers is a cultural phenomenon that transcends socioeconomic boundaries. For millions of participants, the moment the numbers are drawn represents the thin line between a standard financial trajectory and an overnight transformation into the ultra-wealthy. However, the question of “what was the Powerball winning numbers tonight” is merely the beginning of a complex financial journey. In the world of high-stakes personal finance, a winning ticket is not just a stroke of luck; it is a massive liquidity event that requires sophisticated management, strategic tax planning, and a disciplined approach to wealth preservation.

To understand the true weight of those numbers, one must look past the immediate excitement and examine the structural realities of sudden wealth. Whether you are a casual player or a student of financial systems, the mechanics of the lottery offer a masterclass in the time value of money, taxation, and the psychology of asset management.
The Financial Mechanics of the Powerball: Understanding Odds and Payouts
When the winning numbers are announced, the headline figure is often a staggering nine or ten-figure sum. Yet, in the realm of professional finance, that number is rarely what it seems. The advertised jackpot represents the total payout if the winner chooses the annuity option over 30 years. For a person focused on capital growth and immediate liquidity, the “Cash Option” is the more relevant figure.
Cash Option vs. Annuity: The Time Value of Money
The choice between a lump sum and an annuity is a classic exercise in net present value (NPV). The annuity option provides 30 graduated payments that increase by 5% each year, intended to protect the winner from their own spending impulses and to provide a hedge against inflation. From a conservative personal finance perspective, the annuity is a “safety first” approach.
However, most financially savvy winners opt for the lump sum. The rationale is based on the opportunity cost of capital. By taking the cash value—which is typically around 50% to 60% of the headline jackpot—an investor can immediately deploy that capital into diversified portfolios, real estate, or private equity. If the historical average return of the S&P 500 (approximately 10% before inflation) exceeds the internal rate of return offered by the lottery’s annuity structure, the lump sum is mathematically superior. The risk, of course, is market volatility and the “human element” of mismanagement.
The Tax Impact: Federal and State Obligations
Before a single dollar reaches a winner’s bank account, the government takes its share. At the federal level, the IRS considers lottery winnings as ordinary income. The top marginal tax rate is currently 37%. Upon winning, the lottery commission typically withholds 24% automatically, but winners must be prepared to bridge the 13% gap during tax season.
State taxes add another layer of complexity. Depending on where the ticket was purchased, a winner might face an additional 0% to 10% in state income taxes. In a “Money” context, this means that a $500 million jackpot might dwindle to an actual take-home of roughly $180 million to $220 million after the cash-option reduction and tax withholdings. Understanding these “real numbers” is the first step in responsible wealth management.
Sudden Wealth Management: Protecting Your Windfall
The phenomenon of “Sudden Wealth Syndrome” is well-documented in financial planning circles. It refers to the stress, guilt, and decision paralysis that often accompany a massive, unexpected influx of capital. When the winning numbers match your ticket, your primary objective shifts from wealth accumulation to wealth preservation.
Assembling Your Financial Dream Team
A lottery winner should never navigate the financial landscape alone. The first move—before even claiming the prize in some jurisdictions—is to assemble a “Foundational Trio”:
- A Tax Attorney: Unlike a standard accountant, a tax attorney provides attorney-client privilege and can help structure your claim through trusts or LLCs (where state law allows) to maintain anonymity and minimize liability.
- A Certified Financial Planner (CFP) or Private Wealth Manager: You need someone with experience managing eight-figure portfolios. Their role is to create a “Safe Spend” rate that ensures the principal remains untouched while you live off the interest.
- A Certified Public Accountant (CPA): To manage the ongoing tax filings, quarterly estimated payments, and complex audit trails that come with high-net-worth status.

The Initial 90 Days: Why Silence is Golden
The most critical financial advice for any winner is to remain anonymous for as long as possible. In the world of personal finance, privacy is a form of asset protection. Once the public knows “what was the Powerball winning numbers tonight” and who holds the ticket, the winner becomes a target for frivolous lawsuits, predatory “investment opportunities,” and aggressive solicitations from distant relatives.
Establishing a “cooling-off period” allows the winner to process the emotional impact of the win without making impulsive purchases—like Ferraris or mansions—that carry high carrying costs (insurance, maintenance, property taxes) which can drain liquidity.
Investing for the Long Term: Turning a Win into a Legacy
Once the initial shock subsides and the legal structures are in place, the focus shifts to asset allocation. A lottery win of significant size moves an individual from the “growth” phase of life into the “preservation and legacy” phase.
Diversification Beyond the Lottery Ticket
A common mistake of the newly wealthy is keeping too much capital in cash or overly concentrated positions. Professional wealth management dictates a diversified approach:
- Equities and Fixed Income: A balanced portfolio of low-cost index funds and municipal bonds can provide a steady stream of tax-advantaged income.
- Real Estate: Investing in income-producing properties provides a hedge against inflation and offers significant tax depreciation benefits.
- Alternative Investments: For those with hundreds of millions, exposure to private equity or venture capital can provide higher returns, though with higher risk and lower liquidity.
Inflation and Purchasing Power
While $100 million seems like an infinite amount of money, inflation is the silent killer of wealth. At a 3% inflation rate, the purchasing power of money halves in about 24 years. This is why “parking the money in a savings account” is a poor financial strategy for a Powerball winner. The capital must be put to work in assets that appreciate at a rate higher than the Consumer Price Index (CPI) to ensure that the wealth lasts for multiple generations.
The Psychology of Money and the Lottery Lifestyle
Personal finance is 20% math and 80% behavior. This is never truer than in the aftermath of a massive windfall. The “lottery curse” is not a matter of bad luck; it is a matter of poor behavioral finance.
Avoiding the “Lottery Curse”
Many winners go bankrupt within five to ten years because they treat their windfall as income rather than capital. They spend the principal rather than the yield. To avoid this, financial advisors often recommend a “firewall” strategy: setting aside a small, fixed percentage (e.g., 1–2%) for “fun” purchases while the remaining 98% is locked away in irrevocable trusts or long-term investments. This satisfies the psychological urge to celebrate the win without compromising the financial foundation.
Strategic Philanthropy and Tax Deductions
For the high-net-worth individual, giving money away is not just a moral choice; it is a strategic financial one. Establishing a Donor-Advised Fund (DAF) or a private foundation allows a winner to claim immediate tax deductions, which can offset the massive income tax bill from the year the jackpot was won. This allows the winner to direct their wealth toward causes they care about while simultaneously optimizing their tax position.
Conclusion: Building Sustainable Wealth Regardless of the Numbers
The question “what was the Powerball winning numbers tonight” captures the imagination of the public, but the true story of wealth is written in the months and years following the draw. For the few who find themselves holding the winning combination, the challenge is to transition from a “lottery mindset” to a “stewardship mindset.”
Sustainable wealth is not built on a single lucky event; it is maintained through rigorous financial discipline, expert consultation, and a long-term perspective on capital. Whether you win the Powerball or build wealth through traditional investing and entrepreneurship, the principles remain the same: understand your tax obligations, respect the power of compound interest, and always prioritize the preservation of your financial independence. In the end, the numbers on the screen are just the start; what you do with them determines whether they are a blessing or a fleeting moment of financial history.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.