
Matka gambling, often referred to as Satta Matka, is a high-stakes lottery and numbers game that originated in India. While it began as a simple speculative venture based on the fluctuating prices of cotton on the New York Cotton Exchange, it has evolved into a massive, multi-billion-dollar underground economy. For those analyzing the intersection of personal finance and high-risk speculation, understanding Matka is crucial, as it represents one of the most persistent forms of unregulated financial activity in the world.
To the uninitiated, Matka may seem like a simple game of chance. However, from a financial perspective, it is a complex ecosystem with its own set of rules, market makers, and economic consequences. It operates outside the traditional banking sector, yet it influences the liquidity and financial health of millions of individuals. This article explores the origins, mechanics, and the modern digital transformation of Matka gambling, while examining the profound financial risks associated with this speculative practice.
The Historical Evolution of Matka: From Commodity Trading to Digital Betting
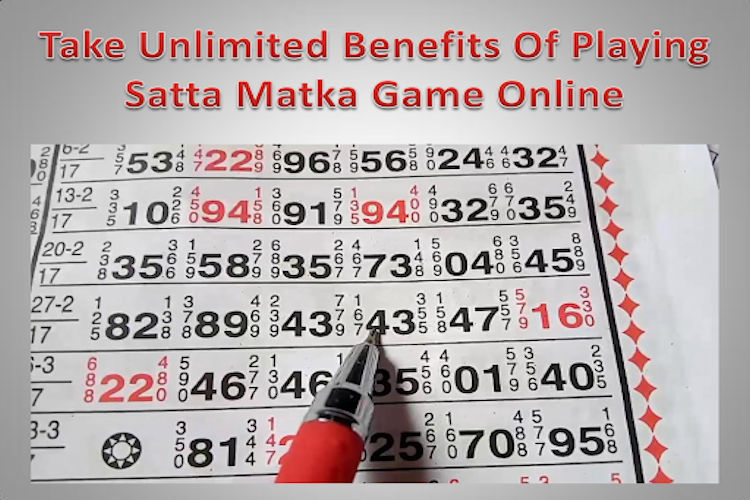
The roots of Matka gambling are deeply tied to the financial markets of the mid-20th century. In the 1960s, the game was known as “Ankada Jugar” (figures gambling). It involved betting on the opening and closing rates of cotton transmitted from the New York Cotton Exchange to the Bombay Cotton Exchange via teleprinters.
The Shift to Random Number Generation
In 1961, the New York Cotton Exchange stopped the practice, forcing the organizers to find a new way to keep the industry alive. Ratan Khatri, often cited as the “Matka King,” introduced the idea of declaring opening and closing rates based on imaginary numbers. Numbers were written on pieces of paper and put into a “Matka” (an earthen pot). A person would then draw a chit and declare the winning numbers. This shifted the game from a pseudo-commodity derivative to a pure numbers-based lottery.
The Rise of Market Figures
Two major players dominated the Matka landscape: Kalyanji Bhagat and Ratan Khatri. Bhagat started the Kalyan Matka in 1962, which ran every day of the week. Khatri introduced the New Main Matka in 1964, which operated only five days a week and became the preferred choice for many due to perceived fairness in how the numbers were drawn. These figures established the financial framework that still exists today, creating a decentralized network of “bookies” who act as the intermediaries between the players and the main “syndicate.”
The Financial Mechanics: How the Game Operates
To understand Matka from a financial or investment perspective, one must look at the “Anks” (numbers) and the payout structures. Unlike regulated stock markets or fixed-income instruments, Matka offers astronomical returns, which is what draws in individuals looking for rapid wealth accumulation. However, the mathematical probability is heavily skewed in favor of the house.
The Betting Process (The Ank and the Pana)
The game involves two sets of three numbers (ranging from 0-9) drawn twice a day—the “Open” and the “Close.”
- The Draw: Three numbers are selected. For example, 3, 5, and 6.
- The Sum: These numbers are added together (3+5+6 = 14).
- The Result: The last digit of the sum is taken. In this case, 4.
The final result for the first draw would be written as 3, 5, 6 *4. This process is repeated for the second draw.
Payout Ratios and the House Edge
The financial lure of Matka lies in its payout ratios, which vary depending on the type of bet placed:
- Single: Betting on one digit (0-9). The payout is typically 9 to 1.
- Jodi: Betting on the pair of numbers from the open and close draws. The payout is 90 to 1.
- Patti/Pana: Betting on the three digits drawn. These payouts can reach 600 to 1 or higher.
While a 90x return on a “Jodi” bet sounds lucrative, the statistical probability of winning is only 1%. This creates a massive “house edge,” ensuring that the organizers remain profitable while the majority of participants face total capital loss. In financial terms, Matka is a zero-sum game with extremely high friction costs (the bookie’s commission).
The Modern Transformation: Matka in the Digital Age
With the advent of the internet and mobile technology, Matka has transitioned from street-corner slips to sophisticated mobile applications. This digital migration has changed the financial profile of the game, making it more accessible but also more dangerous for the average participant’s personal finances.
The Rise of Online Matka Apps
Today, hundreds of websites and apps offer live results for “Kalyan Matka,” “Rajdhani Night,” and “Main Ratan.” These platforms act as digital “bookies,” allowing users to deposit money via UPI, digital wallets, or even cryptocurrency. The integration of fintech has streamlined the betting process, removing the physical barriers that once limited the game’s reach.
Cybersecurity and Financial Fraud
The transition to digital platforms has introduced new risks:
- Unregulated Platforms: Since Matka is illegal in most parts of India (under the Public Gambling Act of 1867), these apps operate in a legal gray area or through offshore servers. This means there is no consumer protection. If an app disappears with a user’s deposit, there is no legal recourse.
- Data Vulnerability: Users often share sensitive banking information with these unregulated apps, making them prime targets for identity theft and financial fraud.
- Algorithmic Manipulation: Unlike the physical earthen pot, digital draws are handled by algorithms. There is high potential for “house-side” manipulation to ensure the most heavily bet-on numbers do not win.
The Economic Impact: Personal Finance and Social Consequences
From a personal finance standpoint, Matka gambling is often viewed as a “poverty trap.” It preys on the hope of individuals in lower-income brackets who view the game as a legitimate “side hustle” or a way to escape financial hardship. However, the reality is a cycle of debt and wealth erosion.
The Fallacy of the “Side Hustle”
In the world of professional finance, a side hustle or an investment is expected to have an underlying asset or a value-producing mechanism. Matka has neither. It is purely speculative. Many participants fall into the trap of “chasing losses,” where they increase their bet sizes to recover previous capital. This often leads to the liquidation of actual assets, such as gold, property, or savings, to fund the next bet.
Black Money and the Shadow Economy
On a macro-economic scale, Matka is a primary driver of the “shadow economy.” Because the transactions are cash-based (or through untraceable digital channels), the government loses out on significant tax revenue. Furthermore, the profits from these syndicates are often funneled into other illegal activities, creating a broader systemic risk to the formal financial sector.
Impact on Credit and Financial Health
For individuals, participation in unregulated gambling can destroy creditworthiness. Even if a person isn’t borrowing from a bank to gamble, the drain on their liquidity often leads to defaults on formal loans, utility bills, and insurance premiums. The psychological toll also leads to decreased productivity in the formal workforce, creating a secondary economic loss.
Navigating the Legal and Ethical Landscape
The legal status of Matka in India is complex. While most forms of gambling are prohibited under the Public Gambling Act, individual states have the power to regulate their own laws. Some states have moved toward legalizing and taxing lotteries to curb the Matka syndicate’s power, but the underground market remains resilient due to the higher payout ratios it can offer by not paying taxes.
Investment vs. Speculation
A key takeaway for any financial enthusiast is the distinction between investment and speculation. Investing involves analyzing data, understanding market trends, and putting capital into assets that have the potential to grow over time. Matka is the antithesis of this. It relies on random chance and provides no value to the economy.
Financial Literacy as a Defense
The most effective way to combat the negative financial impact of Matka is through financial literacy. When individuals understand the “math of the game”—the statistical impossibility of long-term success—the allure of the high payout begins to fade. Promoting regulated investment vehicles, such as mutual funds or small-cap stocks, provides a safer (though still risky) outlet for those seeking higher-than-average returns.
In conclusion, while Matka gambling is a fascinating relic of India’s financial history, it remains a significant threat to personal financial stability in the modern era. Its evolution from cotton rates to digital apps shows the adaptability of the industry, but the underlying math remains the same: the house always wins. For anyone looking to build sustainable wealth, the Matka pot is one “investment” that is almost guaranteed to remain empty.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.