
For millions of Americans, the local retail center has evolved from a simple grocery and dry goods destination into a critical hub for personal finance. Walmart, as the world’s largest retailer, has positioned itself at the forefront of this shift by offering a suite of financial services that rival traditional banking institutions in terms of accessibility and cost-effectiveness. Among these services, check cashing remains one of the most utilized. However, navigating the logistics of these services—specifically the operating hours and procedural requirements—is essential for anyone relying on retail liquidity to manage their household budget or business cash flow.
Understanding Walmart’s Financial Ecosystem and Operating Hours
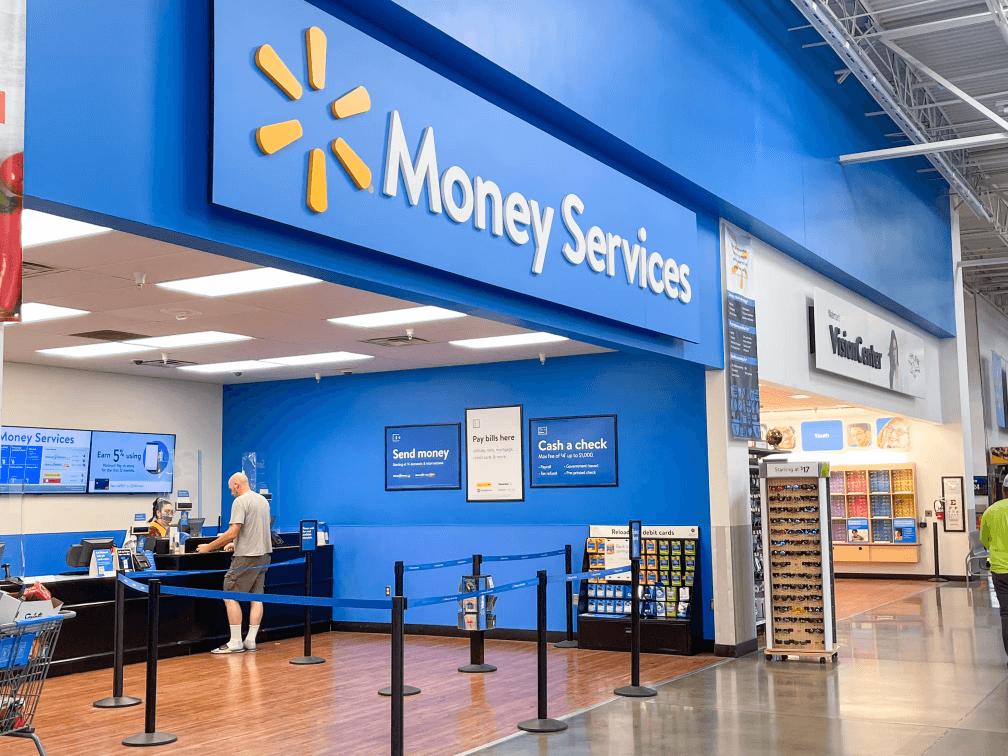
When asking what time check cashing closes at Walmart, the answer is not always a universal one-size-fits-all figure. Generally, most Walmart MoneyCenter locations operate between 8:00 AM and 8:00 PM Monday through Saturday, and 10:00 AM to 6:00 PM on Sundays. However, these hours can vary significantly based on the specific store’s location, staffing levels, and regional regulations.
In many Supercenters, if the dedicated MoneyCenter is closed, the Customer Service desk may be able to process check cashing transactions during the store’s general operating hours. However, this is increasingly rare as stores move toward centralized financial service hubs for security and compliance reasons. It is always advisable to use the Walmart Store Finder tool or the mobile app to check the specific “Services” hours for your local branch before making the trip.
The Distinction Between the MoneyCenter and Customer Service
It is a common misconception that as long as the store is open, the financial services are available. Most Walmart locations are no longer open 24 hours, and even those with extended hours typically limit financial transactions to a specific window. The MoneyCenter is a specialized department with trained associates who handle complex transactions, including money transfers, bill payments, and check cashing. When the MoneyCenter staff departs for the evening, the technical systems or the specialized cash drawers required for high-value check cashing are often locked down, even if the main checkout lanes remain active.
Impact of Holidays and Peak Seasons
During high-traffic periods, such as tax refund season (February through April) or the winter holidays, some stores may extend their MoneyCenter hours to accommodate the influx of customers. Conversely, on major holidays like Christmas or Thanksgiving, services will either be unavailable or significantly curtailed. For those managing a tight financial schedule, understanding these seasonal shifts is paramount to ensuring liquidity isn’t trapped behind a closed service window.
The Strategic Role of Retail Check Cashing in Personal Finance
The prevalence of retail check cashing services highlights a significant trend in modern personal finance: the rise of the “underbanked” and the “unbanked.” For individuals who do not have traditional bank accounts or who prefer not to deal with the holding periods and minimum balance requirements of major banks, Walmart offers a viable, immediate alternative.
Liquidity and the Underbanked
For many workers, particularly those in the gig economy or manual labor sectors, receiving a physical check is still a reality. Waiting three to five business days for a traditional bank to clear a large check can be a significant hurdle when bills are due immediately. Walmart provides near-instant liquidity. By paying a flat fee, the consumer gains access to their funds in minutes, which can then be used to pay utility bills, purchase groceries, or load onto a prepaid debit card—all within the same building.
Comparing Retail Services to Traditional Banks
Traditional banking institutions often require customers to maintain a specific balance to waive monthly fees, and their hours are notoriously restrictive, often closing by 5:00 PM on weekdays and remaining closed on Sundays. In contrast, Walmart’s extended evening and weekend hours provide a level of flexibility that caters to the working class and those with non-traditional schedules. From a financial strategy perspective, the convenience of a 7:00 PM check cashing window on a Saturday can outweigh the small fee associated with the service, especially if it prevents a late fee on a credit card or utility bill.
Side Hustles and Physical Checks
Even in an era of digital payments like Venmo and Stripe, many side hustles—such as freelance contracting, landscaping, or private tutoring—still involve payment via check. For the entrepreneur looking to separate their “side hustle” income from their primary household budget, cashing these checks at a retail location and loading the funds onto a separate Walmart MoneyCard can serve as a rudimentary but effective form of business accounting.
Check Types and Limits: Navigating the Rules
Not every check is treated equally at the MoneyCenter. Walmart has strict internal policies regarding the types of checks they will cash and the maximum amounts permitted. These policies are designed to mitigate the risk of fraud while maintaining a streamlined service for the consumer.
Accepted Check Types
Walmart generally accepts the following types of checks:
-
Payroll Checks: The most common type of check cashed.
-
Government Checks: Including Social Security benefits and stimulus payments.
-
Tax Refund Checks: Walmart is a major hub for cashing federal and state tax refunds.
-
Insurance Settlement Checks: Often cashed after a claim payout.
-
Cashier’s Checks: Though subject to more rigorous verification.
-
401(k) or Retirement Distribution Checks: Providing immediate access to retirement funds.

Crucially, most Walmart locations do not cash personal checks. This is due to the high risk of “bounced” checks or insufficient funds, which the retailer cannot easily verify in real-time.
Limits and Fee Structures
Walmart’s cashing limits are generally capped at $5,000 per check, although this limit is often increased to $7,500 during the peak tax season (January through April). The fee structure is designed to be competitive with standalone check-cashing storefronts, which often charge a percentage of the check’s value.
As of current standards, Walmart typically charges:
-
$4.00 for checks up to $1,000.
-
$8.00 for checks between $1,001 and $5,000.
-
Specialized rates for tax refund checks during certain promotions.
From a financial management standpoint, these flat fees are significantly more affordable than the 2% to 5% fees charged by specialized check-cashing outlets, which could cost a consumer $20 to $50 for a $1,000 check.
Preparation and Documentation: Maximizing Your Visit
To ensure a smooth transaction before the MoneyCenter closes, customers must come prepared with the necessary documentation. Retailers like Walmart are subject to federal “Know Your Customer” (KYC) and Anti-Money Laundering (AML) regulations, which require strict identity verification.
Identification Requirements
A valid, government-issued photo ID is non-negotiable. This can include:
-
A U.S. Driver’s License.
-
A State ID card.
-
A U.S. Passport.
-
A Military ID.
-
A Tribal ID.
If your ID is expired or the name does not exactly match the name on the check, the transaction will likely be declined.
The Verification Process
Walmart utilizes third-party verification systems, such as TeleCheck or Certegy, to validate the authenticity of the check and the history of the issuer. If the system flags a check—even if it is a legitimate payroll check—the associate cannot override the system. This underscores the importance of cashing checks during business hours when the issuing bank or the employer’s HR department might be available to answer questions if a verification issue arises.
Security and Safety
Cashing a large check at a retail location involves carrying a significant amount of cash in a public space. Financial experts recommend being discreet, utilizing the option to load funds directly onto a Walmart MoneyCard or another debit card, and avoiding counting cash in plain view of other shoppers.
Modern Alternatives and the Future of Instant Liquidity
While physical check cashing remains a staple, the landscape of personal finance is shifting toward digital-first solutions. Walmart has recognized this trend by integrating its physical services with digital tools.
The Walmart MoneyCard
The Walmart MoneyCard is a reloadable prepaid Visa or Mastercard that offers a bridge between cash and digital banking. Instead of taking cash from a cashed check, users can load the full amount onto the card. This card often features “Early Direct Deposit,” allowing users to access their paychecks up to two days early, effectively bypassing the need to visit the MoneyCenter altogether.
Mobile Check Deposit
Many modern financial apps and “neo-banks” now offer mobile check deposit. However, these still often involve a waiting period for the funds to clear. For those who need money now, the physical retail counter remains the fastest route. Walmart’s app also offers “Mobile Express Money Services,” which allows users to start their transaction on their phone to save time at the counter, ensuring they beat the closing time of the MoneyCenter.
Is Retail Cashing Still Relevant?
As the economy becomes increasingly digital, one might wonder if retail check cashing will become obsolete. For the foreseeable future, the answer is no. As long as employers issue physical checks and a portion of the population remains outside the traditional banking system, the Walmart MoneyCenter provides a vital service. It offers a level of transparency and affordability that is often missing from other “alternative” financial services, making it a cornerstone of financial stability for many households.
By understanding the hours of operation, the costs involved, and the documentation required, consumers can use Walmart’s financial services as a tool for better money management, ensuring that their hard-earned funds are accessible exactly when they are needed.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.