
Filing taxes independently has evolved from a seasonal chore into a strategic component of personal financial management. In an era where digital tools and streamlined IRS processes have lowered the barrier to entry, many taxpayers are moving away from costly professional preparers in favor of a self-directed approach. Taking control of your own tax filing not only saves on professional fees—which can range from hundreds to thousands of dollars depending on complexity—but also provides a profound understanding of your own financial health. By navigating the nuances of income reporting, deductions, and credits, you gain the insight necessary to make better fiscal decisions throughout the rest of the year.

This guide outlines the comprehensive steps required to file your taxes solo, ensuring accuracy, maximizing your return, and maintaining compliance with current tax laws.
Laying the Groundwork: Essential Documentation and Organization
The success of a self-filed tax return is determined long before you log into a software platform or put pen to paper. Preparation is the most critical phase of the process. For those in the “Money” niche, this means treating tax preparation as an audit of your annual cash flow and asset performance. To begin, you must aggregate every piece of financial data that influenced your net worth over the preceding twelve months.
Income Statements and Earning Records
The most common document is the W-2, provided by employers to detail wages and taxes withheld. However, the modern financial landscape often involves multiple income streams. If you are a freelancer or a participant in the “gig economy,” you must collect 1099-NEC and 1099-K forms. For those with diversified portfolios, 1099-INT (interest), 1099-DIV (dividends), and 1099-B (brokerage transactions) are essential. These documents represent the “inflow” portion of your tax equation and must be reported accurately to avoid discrepancies with IRS records.
Expense Tracking and Deduction Receipts
Once income is established, the focus shifts to minimizing taxable liability through deductions. If you plan to itemize rather than take the standard deduction, your documentation must be meticulous. This includes mortgage interest statements (Form 1098), records of charitable contributions, property tax receipts, and documentation of significant medical expenses. For the self-employed, organizing receipts for business-related expenses—such as home office costs, equipment, and travel—is vital. Utilizing digital expense trackers or dedicated business bank accounts throughout the year can significantly simplify this stage.
Adjustments to Income
Before arriving at your Adjusted Gross Income (AGI), you may be eligible for “above-the-line” deductions. These are particularly important for personal finance optimization because they are available regardless of whether you itemize. Key documents here include records of student loan interest payments, contributions to health savings accounts (HSAs), and contributions to traditional IRAs. Having these figures ready allows you to see an immediate reduction in your taxable income.
Selecting Your Filing Vehicle: Software vs. Manual Systems
The method you choose to file your taxes should align with the complexity of your financial situation. While the IRS still accepts paper returns, the vast majority of independent filers now use digital solutions to increase speed and reduce the likelihood of mathematical errors.
The Rise of IRS Free File and Direct File
For taxpayers with an AGI below a certain threshold (typically $79,000), the IRS Free File program provides access to name-brand tax software at no cost. This is an underutilized tool in personal finance that can save significant capital. Furthermore, the IRS has recently piloted “Direct File,” a government-run interview-based filing system. These tools are designed for straightforward returns and are an excellent entry point for those filing solo for the first time.
Commercial Tax Software Tiers
When your financial life includes rental properties, capital gains from crypto-currency, or complex business structures, premium software often becomes a necessary investment. Platforms like TurboTax, H&R Block, and FreeTaxUSA offer tiered services. When choosing a software, look for features such as “audit defense” or the ability to import data directly from your brokerage. From a financial perspective, the cost of the software is often offset by the peace of mind that comes from built-in error checking and the identification of obscure credits you might otherwise overlook.
The Manual Approach: Form 1040
For those who truly want to understand the mechanics of the tax system, filing manually using the IRS’s Free File Fillable Forms is an option. This requires a strong grasp of tax law and a high level of confidence in your calculations. While it offers the most transparency into how your money is being taxed, it lacks the automated “logic checks” provided by software. Most financial experts recommend this only for the most diligent individuals who wish to see exactly how each line item affects their final liability.
Strategic Deductions and Credits: Keeping More of Your Earnings
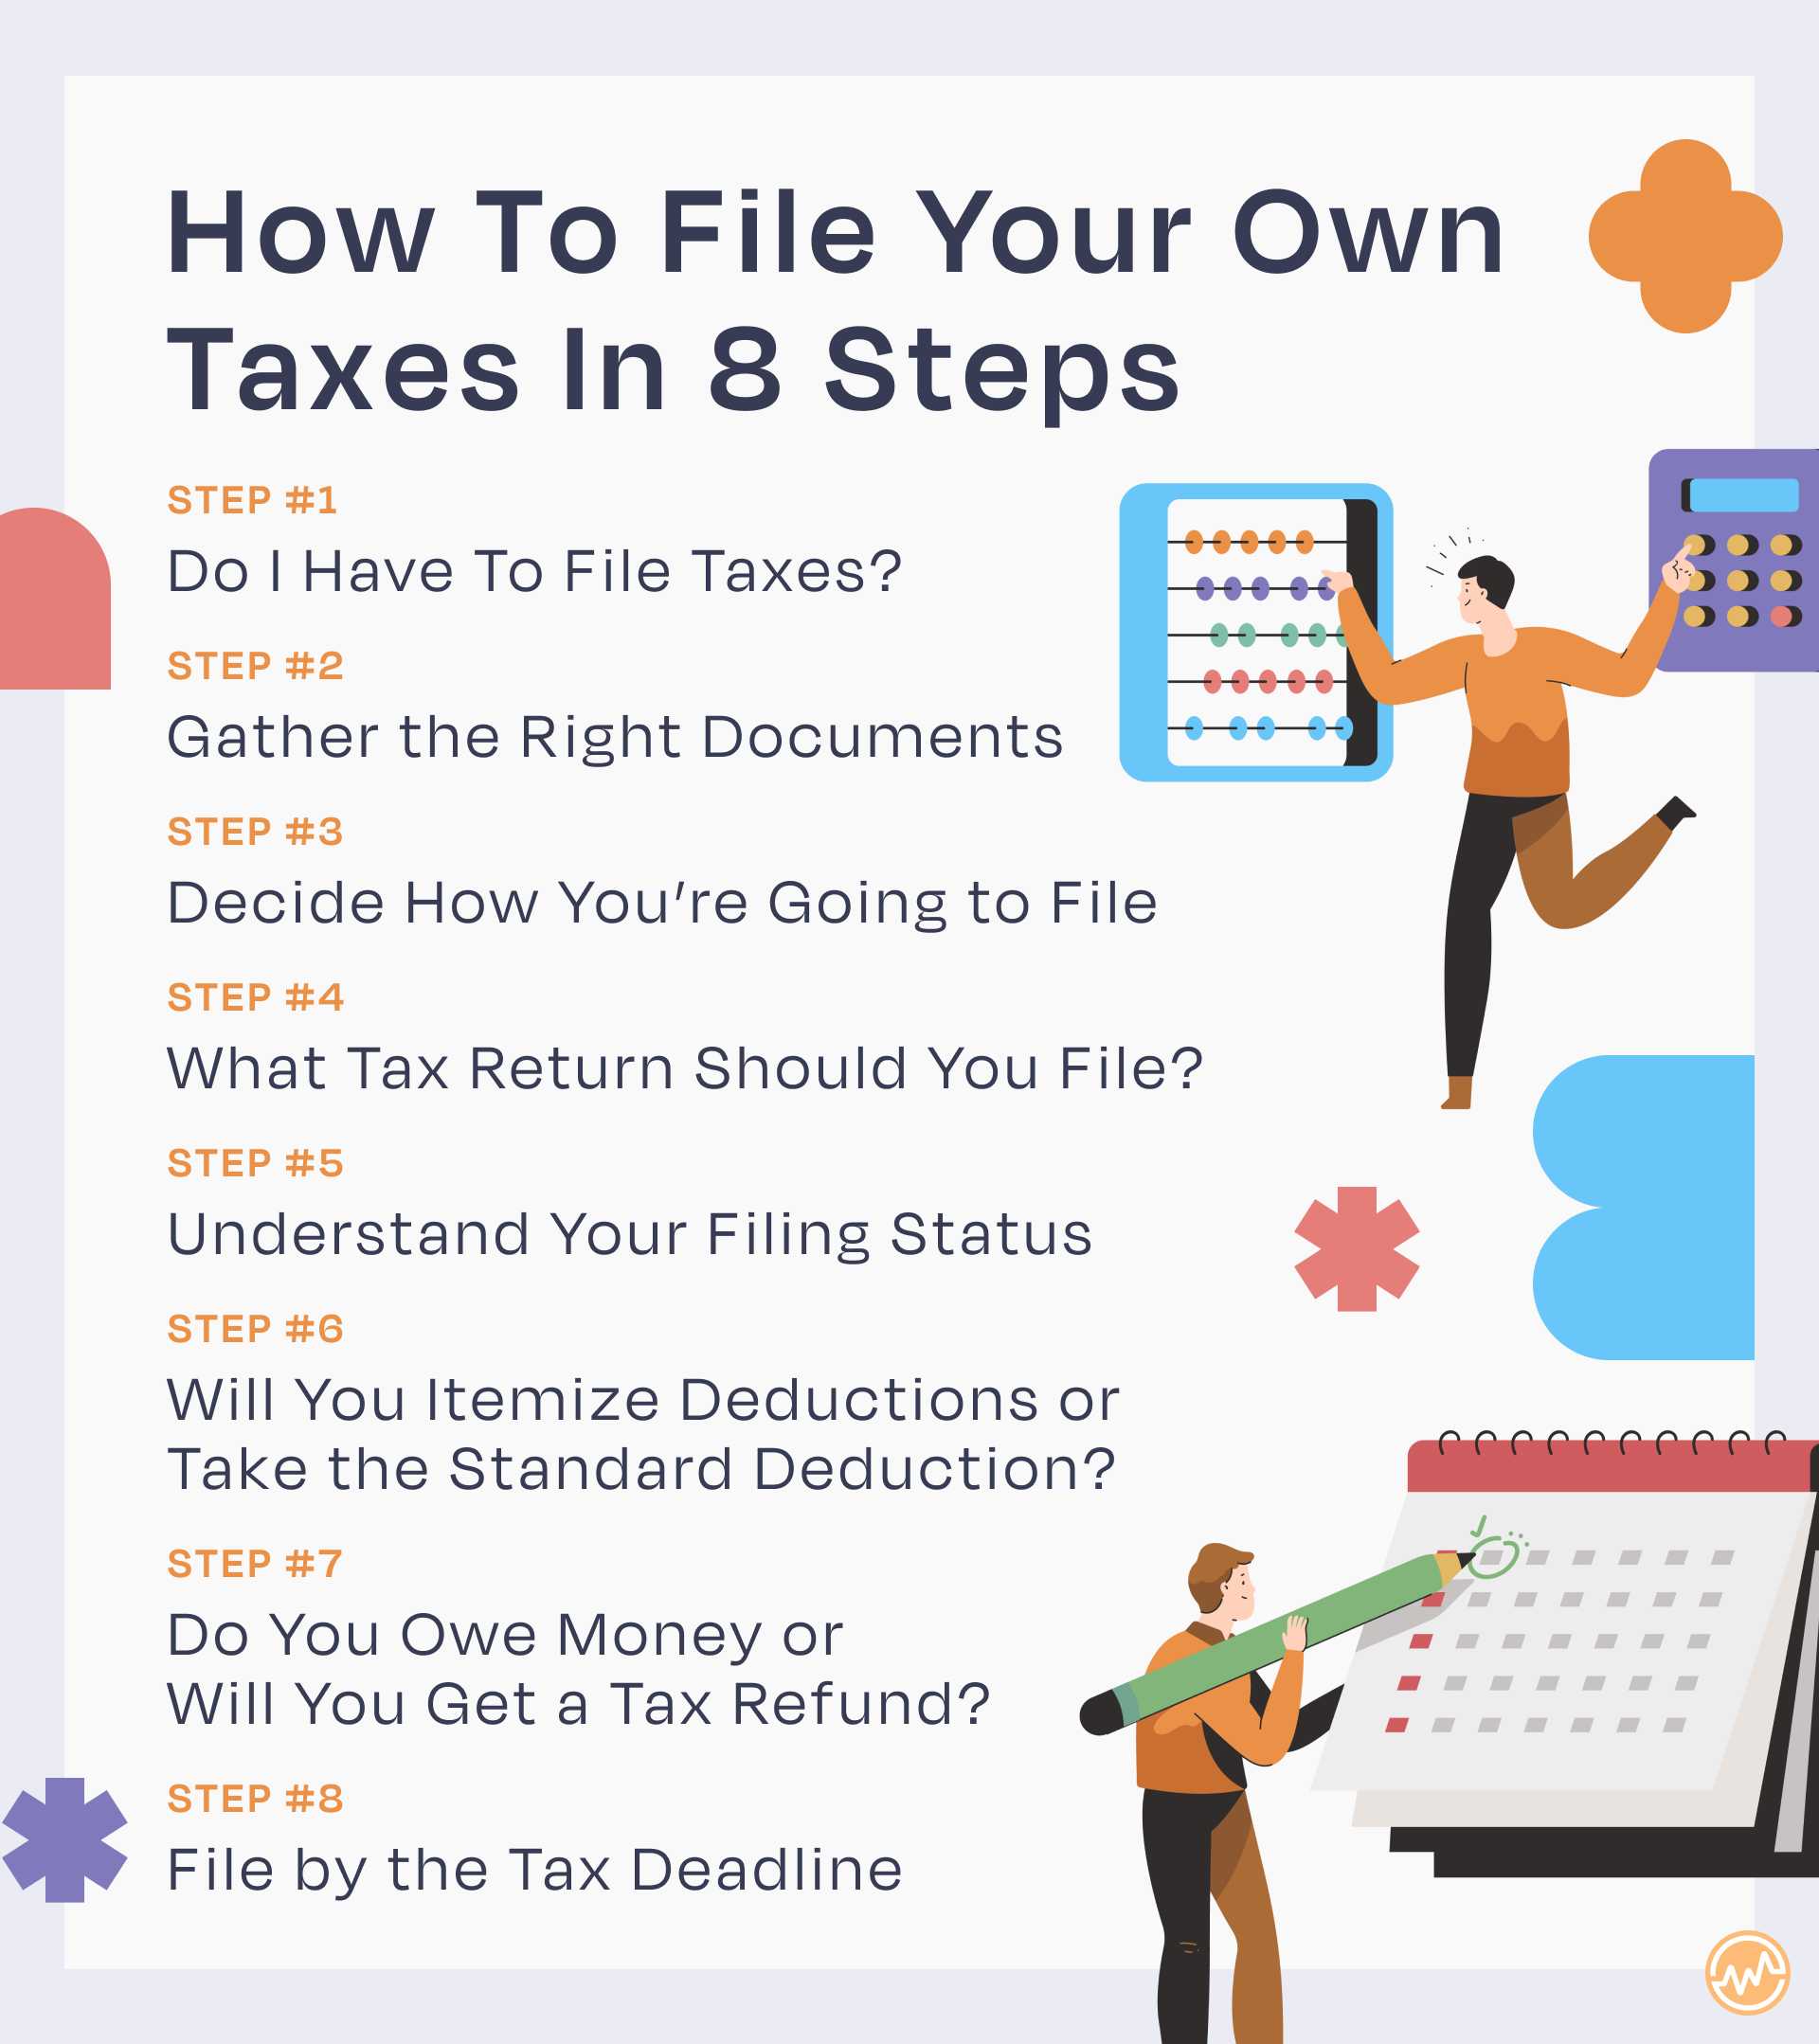
A primary goal of filing your own taxes is to maximize the amount of money you keep. This requires a nuanced understanding of the difference between deductions and credits. A deduction lowers the income you are taxed on, while a credit is a dollar-for-dollar reduction of the tax you owe. Mastering these can lead to significant wealth preservation.
The Standard Deduction vs. Itemizing
The most significant decision most filers face is whether to take the standard deduction or to itemize. Since the Tax Cuts and Jobs Act of 2017, the standard deduction has been high enough that it makes sense for the majority of Americans. However, if your deductible expenses (mortgage interest, state and local taxes up to $10,000, and charitable gifts) exceed the standard threshold, itemizing is the superior financial move. A savvy filer will run the numbers both ways before finalizing their return.
Leveraging Refundable and Non-Refundable Credits
Tax credits are the “holy grail” of tax filing. The Child Tax Credit (CTC) and the Earned Income Tax Credit (EITC) can provide substantial refunds even if you owe no tax. Additionally, education-related credits like the American Opportunity Tax Credit (AOTC) can help recover the costs of tuition and books. For the environmentally conscious investor, credits for residential energy improvements or the purchase of electric vehicles can result in thousands of dollars in savings. Understanding the eligibility requirements for these credits is a hallmark of sophisticated personal finance management.
The Self-Employment Advantage
If you operate a side hustle or small business, filing yourself allows you to leverage the Qualified Business Income (QBI) deduction. This allows many sole proprietors to deduct up to 20% of their qualified business income from their taxes. When combined with deductions for the employer-equivalent portion of self-employment tax and health insurance premiums, the tax burden on entrepreneurs can be managed effectively with proper filing techniques.
The Final Review: Mitigating Risks and Optimizing Cash Flow
Before hitting the “submit” button, a final audit of your return is necessary. This stage is where you transition from data entry to risk management. Errors on a tax return can lead to processing delays, missed refunds, or, in the worst-case scenario, an IRS audit.
Common Pitfalls and Double-Checking
The most frequent errors are often the simplest: transposed Social Security numbers, misspelled names, or incorrect bank routing numbers. Financial software catches many of these, but a manual review of the final PDF output is essential. Ensure that all income reported on your 1099s and W-2s matches exactly what you have entered. The IRS’s automated matching systems will flag even minor discrepancies, which can trigger a manual review and delay your refund by weeks or months.
Optimizing Refund Speed and Security
From a liquidity standpoint, the fastest way to receive your refund is through e-filing combined with direct deposit. Most electronic returns are processed within 21 days. For individuals who use their tax refund as a vehicle for annual investments—such as funding an IRA or paying down high-interest debt—the timing of this cash infusion is critical. Ensure your banking information is current and that you have opted for the most secure transmission methods available.
Digital Security and Identity Protection
Filing taxes involves handling your most sensitive financial information. When filing by yourself, ensure you are using a secure, private internet connection. Avoid public Wi-Fi. Many filing platforms now offer multi-factor authentication (MFA); this should be considered mandatory. Protecting your Social Security number and financial data is an integral part of maintaining your overall digital and financial security.
Long-Term Tax Planning and Fiscal Health
Filing your taxes shouldn’t be a one-off event that happens in April; it should be the conclusion of a year-long financial strategy. The insights gained while filing by yourself should inform your financial behavior for the upcoming year.
Adjusting Withholdings for Better Cash Flow
If you receive a massive refund, you have essentially given the government an interest-free loan for a year. From a wealth-building perspective, it is often better to adjust your W-4 withholdings so that you receive more money in each paycheck, which can then be invested in interest-bearing accounts or the stock market. Conversely, if you owe a significant amount, you may need to increase your withholdings or start making quarterly estimated payments to avoid underpayment penalties.
Retirement Contributions as a Tax Shield
The process of filing may reveal that your taxable income is higher than you’d like. This is the perfect time to evaluate your retirement strategy. Contributions to a 401(k) or a Traditional IRA directly reduce your taxable income. If you find yourself in a high tax bracket during your self-filing process, it serves as a powerful incentive to maximize these contributions in the following year, effectively moving money from a “taxable” column to a “wealth-building” column.
Record Retention for Future Audits
Once the filing is complete, your final task is the organization of records for the future. The IRS generally has three years to audit a return, though some circumstances can extend this window. Maintain a digital and physical file containing your submitted return and all supporting documentation. This level of organization is not just about compliance; it creates a financial history that can be invaluable when applying for mortgages, business loans, or planning an estate. By mastering the art of self-filing, you turn a complex legal requirement into a streamlined process for personal financial empowerment.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.