
Taxation is often viewed as an unavoidable burden, a fixed cost of living in a civilized society. However, for the financially savvy individual, taxes are not a static expense but a variable that can be managed through proactive planning and strategic decision-making. Saving on taxes is not about evasion; it is about tax avoidance—the legal utilization of the tax regime to your advantage to ensure you are not paying a penny more than what is legally required.
The difference between a haphazard approach to taxes and a structured strategy can result in hundreds of thousands of dollars in cumulative wealth over a lifetime. To master the art of tax saving, one must look beyond the annual filing deadline and integrate tax efficiency into every aspect of their financial life, from retirement planning to investment selection and charitable giving.
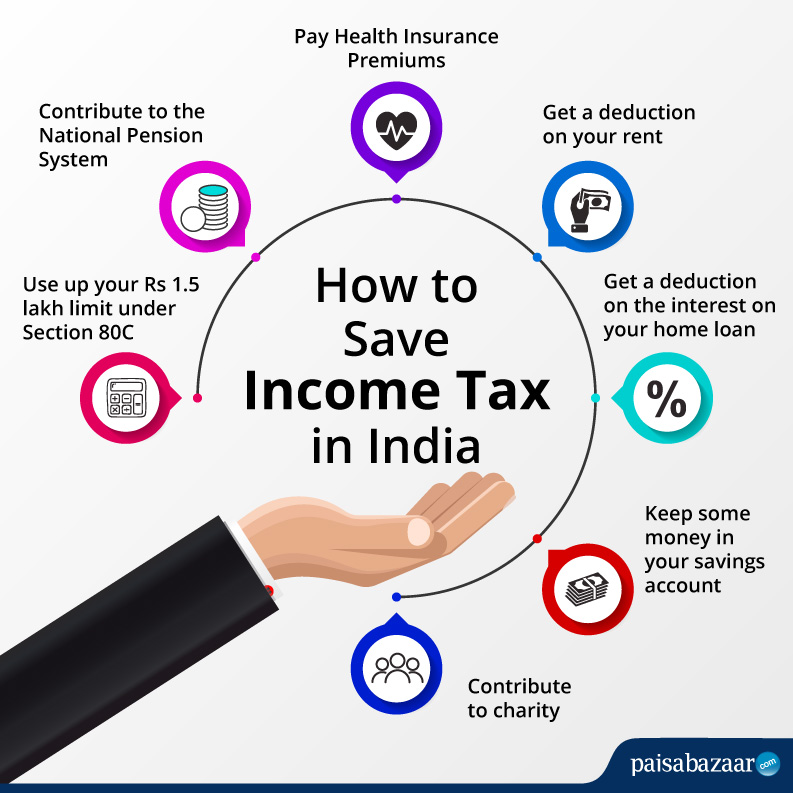
Understanding the Foundation of Tax Efficiency
The first step in reducing your tax liability is understanding the fundamental mechanics of how you are taxed. Most modern tax systems are progressive, meaning the more you earn, the higher the percentage you pay on those marginal dollars. Tax saving strategies generally fall into three categories: reducing your adjusted gross income (AGI), increasing your deductions, and utilizing tax credits.
The Power of Reducing Adjusted Gross Income
Your Adjusted Gross Income is the starting point for determining your tax bill. By lowering this number, you automatically lower the baseline from which your taxes are calculated. The most effective way to do this is through “above-the-line” deductions. These include contributions to employer-sponsored retirement plans like a 401(k) or 403(b). Because these contributions are often made with pre-tax dollars, they reduce your taxable income dollar-for-dollar. If you earn $100,000 and contribute $20,000 to a 401(k), the government only sees $80,000 of taxable income.
Tax Planning vs. Tax Compliance
Many people confuse tax compliance (filling out forms correctly and hitting deadlines) with tax planning. Tax planning is a year-round activity that involves making financial decisions based on their tax implications. This includes timing the sale of assets, choosing the right types of investment accounts, and structuring business entities. By the time you sit down to file your taxes in April, most of your opportunities to save for the previous year have already vanished. True tax savings are realized in the decisions made between January and December.
Leveraging Retirement and Health Accounts
The most accessible and powerful tools for the average taxpayer are specialized accounts designed by the government to encourage long-term saving. These accounts offer significant tax “carrots” to incentivize specific behaviors, such as saving for retirement or healthcare.
Retirement Vehicles: Traditional vs. Roth
One of the most frequent questions in personal finance is whether to use a Traditional or Roth account. In a Traditional 401(k) or IRA, you get a tax break today; your contributions are deductible, but you pay taxes when you withdraw the money in retirement. In a Roth account, you pay taxes on the money now, but your withdrawals in retirement—including all the growth—are entirely tax-free.
To save tax effectively, you must analyze your current tax bracket versus your expected bracket in retirement. If you are in a high bracket now, the Traditional route saves you more today. If you are early in your career and in a low bracket, the Roth route is a massive long-term tax play, as it shields decades of compound interest from future taxation.
The Triple-Tax Advantage of HSAs
For those with high-deductible health plans, the Health Savings Account (HSA) is arguably the single most efficient tax-saving tool in existence. It offers a “triple-tax advantage”:
-
Contributions are 100% tax-deductible (reducing your AGI).
-
The money grows tax-deferred within the account.
-
Withdrawals for qualified medical expenses are tax-free.
If you can afford to pay for current medical expenses out-of-pocket and leave the HSA funds to grow, you effectively create a secondary retirement account that is never taxed, provided the funds are eventually used for healthcare.
Strategic Investment and Capital Gains Management

Investing is essential for wealth building, but the way you invest can significantly impact how much of your gains you actually keep. The tax code treats different types of investment income differently, and understanding these nuances is key to saving tax.
Tax-Loss Harvesting
Tax-loss harvesting is the practice of selling an investment that is trading at a loss to offset the capital gains realized from winning investments. If you sold a stock for a $10,000 profit but have another stock that has dropped $10,000 in value, you can sell the loser to “harvest” the loss. This wipes out the taxable gain on the winner, bringing your capital gains tax for that transaction to zero.
Furthermore, if your losses exceed your gains, you can typically use up to $3,000 of those excess losses to offset your regular earned income. This is a sophisticated way to turn a portfolio “lemon” into tax-saving “lemonade.”
Long-Term vs. Short-Term Capital Gains
The duration for which you hold an asset changes how it is taxed. Assets held for less than a year are taxed at your ordinary income rate, which can be as high as 37% at the federal level. However, assets held for more than a year are taxed at long-term capital gains rates (typically 0%, 15%, or 20%). Simply waiting until day 366 to sell an appreciated asset can nearly cut your tax bill on that gain in half.
Asset Location Strategy
Not all investments belong in all accounts. “Asset location” refers to placing tax-inefficient investments (like high-dividend stocks or bond funds that pay regular interest) into tax-advantaged accounts like IRAs. Conversely, tax-efficient investments (like index funds with low turnover) are better suited for taxable brokerage accounts. By strategically placing assets, you minimize the “tax drag” on your portfolio, allowing your wealth to compound faster.
Maximizing Deductions and Credits
While the standard deduction has increased significantly in recent years, itemizing is still a viable strategy for many homeowners, high-earners, and business owners. Additionally, tax credits remain the “holy grail” of tax saving because they reduce your tax bill dollar-for-dollar, whereas deductions only reduce the income you are taxed on.
The Strategic Use of Itemized Deductions
If your total deductible expenses exceed the standard deduction, you should itemize. Key areas include:
-
Mortgage Interest: For many, the interest paid on a home loan is the largest single deduction.
-
State and Local Taxes (SALT): While currently capped, this allows you to deduct a portion of your state income and property taxes.
-
Charitable Contributions: Donating to qualified non-profits is a classic way to reduce your taxable income. For high-net-worth individuals, using a Donor-Advised Fund (DAF) allows you to take a large deduction in a high-income year while distributing the money to charities over several years.
Business Owner Advantages
If you are a freelancer, side-hustler, or business owner, the tax code is much more generous. Business owners can deduct “ordinary and necessary” expenses. This includes home office deductions, equipment (Section 179 depreciation), travel, and marketing. Furthermore, the Qualified Business Income (QBI) deduction allows many small business owners to deduct up to 20% of their qualified business income from their taxes, providing a massive incentive for entrepreneurship.
Education and Energy Credits
Tax credits are powerful. The American Opportunity Tax Credit (AOTC) and the Lifetime Learning Credit (LLC) can help offset the costs of higher education. On the environmental front, credits for solar panel installation or electric vehicles can shave thousands off your tax bill. Unlike a deduction, which might save you 24 cents on the dollar if you are in the 24% bracket, a $2,000 credit reduces your tax bill by exactly $2,000.
Building a Proactive Tax Culture
To truly save tax, you must move away from the “April scramble” and adopt a proactive financial lifestyle. This involves meticulous record-keeping and a willingness to consult with professionals when your financial situation gains complexity.
Documentation and Digital Record-Keeping
The IRS (and similar global authorities) operates on proof. You can only save tax on expenses you can document. Utilizing digital tools to track receipts, business mileage, and charitable donations throughout the year ensures that you don’t miss out on deductions because of a lost piece of paper. Modern apps that sync with your bank accounts can automatically categorize deductible expenses, making the year-end process seamless.
The Role of Professional Guidance
As your income grows, the return on investment (ROI) for a professional tax strategist or Certified Public Accountant (CPA) increases. A tax professional doesn’t just fill out your return; they provide structural advice. They can help you determine if you should incorporate as an S-Corp to save on self-employment taxes or help you navigate complex estate tax issues. In many cases, the amount a professional saves you in tax far exceeds the fee they charge for their services.

Conclusion
Saving tax is a marathon, not a sprint. It requires a fundamental shift in how you view your income and expenses. By maximizing retirement contributions, strategically managing your investment portfolio, and staying vigilant about available credits and deductions, you can significantly reduce your tax burden. Ultimately, every dollar saved in tax is an extra dollar that can be invested, saved, or spent on your personal priorities, accelerating your journey toward financial independence. Wealth preservation is just as important as wealth creation, and tax strategy is the most powerful tool in the preservation toolkit.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.