
United Services Automobile Association, widely known as USAA, represents one of the most prestigious and exclusive financial institutions in the United States. Unlike traditional commercial insurers that cater to the general public, USAA functions with a mission-driven focus, providing a suite of financial tools—ranging from auto insurance to investment portfolios—specifically designed for the military community and their families. For those navigating the complexities of personal finance, understanding who qualifies for USAA car insurance is the first step in accessing what is often cited as the gold standard in customer service and financial stability.
The exclusivity of USAA is not a marketing gimmick; it is rooted in its founding principles. Established in 1922 by a group of 25 Army officers who decided to insure each other when no one else would, the organization has evolved into a diversified financial services group. However, its gates remain guarded by specific eligibility requirements that ensure the company continues to serve its core demographic effectively while maintaining the competitive rates that make it a cornerstone of military financial planning.
Understanding the Exclusive Eligibility Criteria
The primary hurdle for any individual seeking USAA car insurance is the eligibility check. Because USAA is a member-owned association, its benefits are reserved for those who have a direct or indirect connection to the U.S. Uniformed Services. This exclusivity allows USAA to tailor its risk models to a specific population, often resulting in lower premiums and higher dividend payouts to its members.
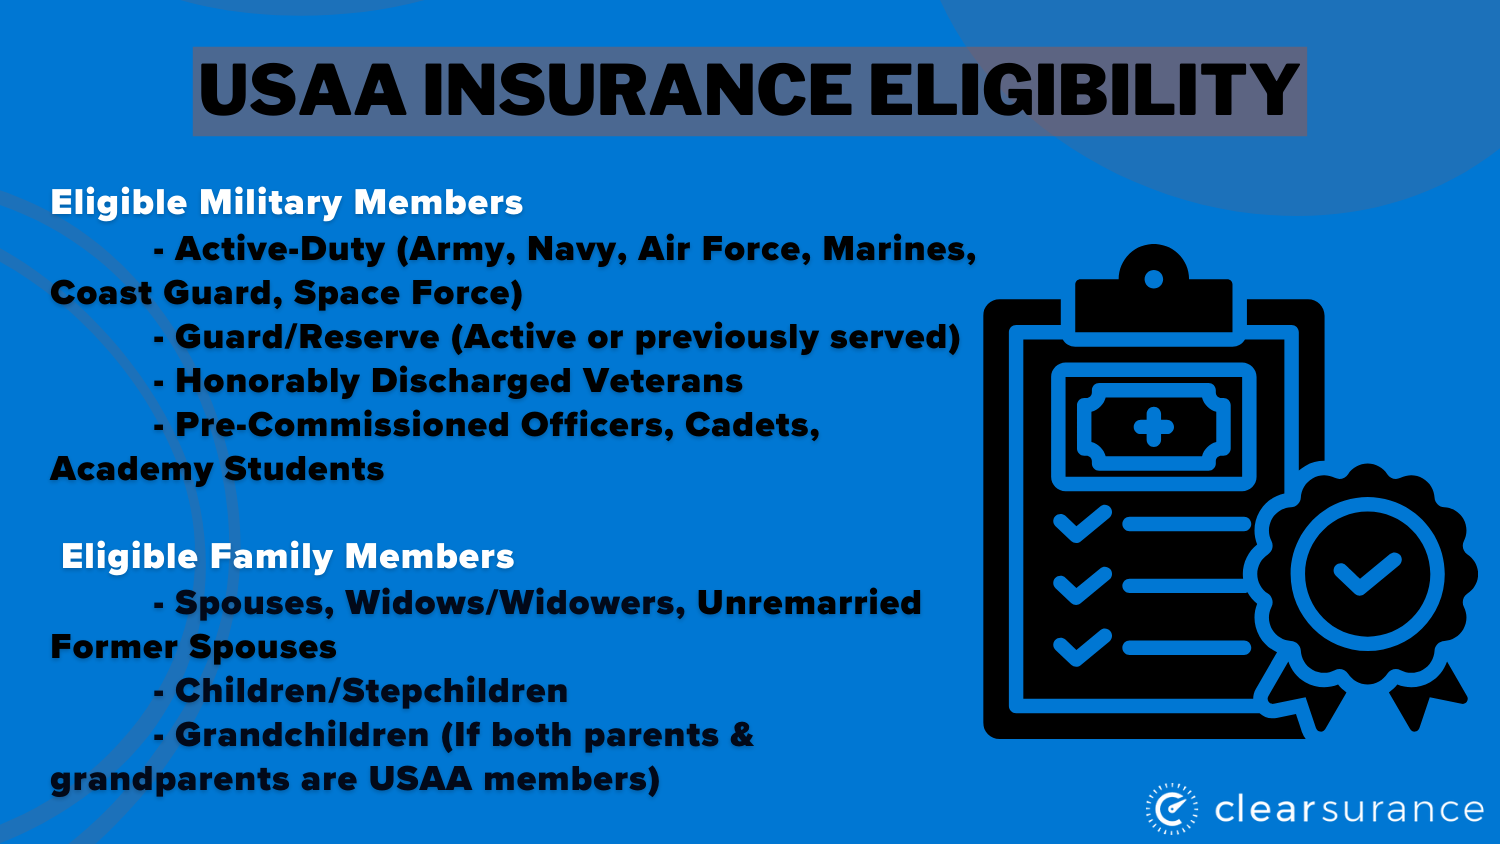
Active Duty and Retired Military Personnel
The most direct path to USAA membership is through active service. This includes individuals currently serving in the U.S. Air Force, Army, Coast Guard, Marine Corps, Navy, and Space Force. Furthermore, those serving in the National Guard and Reserves are fully eligible. For these individuals, USAA provides not just insurance but a comprehensive financial ecosystem that understands the unique challenges of military life, such as frequent relocations (PCS) and deployments.
Retirees also maintain full eligibility. Once an individual has served and retired from the military, they have earned a lifelong right to access USAA’s financial products. This is a critical component of post-service financial planning, as the transition to civilian life often involves a significant recalibration of insurance needs and budget management.
Veterans and Honorably Discharged Service Members
One common misconception is that you must be currently serving or retired to join. In reality, any veteran who has served honorably is eligible for USAA car insurance. This includes those who served their initial contract and transitioned back to the civilian workforce. The “Honorable Discharge” status is the key requirement here; it serves as a badge of eligibility that unlocks a lifetime of financial tools geared toward wealth protection and risk management.
Family Members: The Generational Legacy
USAA’s eligibility extends beyond the service member to their immediate family, creating a generational cycle of financial security. Spouses, widows, and widowers of USAA members (who joined while they were eligible) can maintain their own accounts. More importantly, the children of USAA members are eligible to join the association.
Once a parent becomes a USAA member and establishes an insurance profile, they effectively “pass down” the eligibility to their children. This allows the next generation to access the same competitive rates and financial stability, regardless of whether they choose to serve in the military themselves. This “legacy” aspect is one of the most powerful features of USAA, as it allows families to build a multi-generational financial foundation.
Cadets and Midshipmen
The final primary group includes those currently in the pipeline for military leadership. Cadets and midshipmen at U.S. service academies, as well as students in the Reserve Officers’ Training Corps (ROTC) who are under contract, are eligible for membership. By bringing future officers into the fold early, USAA helps these young professionals establish a credit and insurance history before they even receive their first commission.
The Financial Mechanics of USAA Membership
Joining USAA is more than just buying a policy; it is an entry into a sophisticated financial structure. As a member-owned organization, the “Money” aspect of USAA is unique compared to publicly traded companies like GEICO or Progressive. Understanding these mechanics is essential for any member looking to optimize their personal balance sheet.
The Mutual-Like Structure and Dividends
Unlike stock-based insurance companies that must answer to shareholders, USAA is organized as an inter-insurance exchange. In simple terms, this means the members are essentially the owners. When the company performs well financially—whether due to low claim years or successful investment strategies—it often returns a portion of the profits to its members.
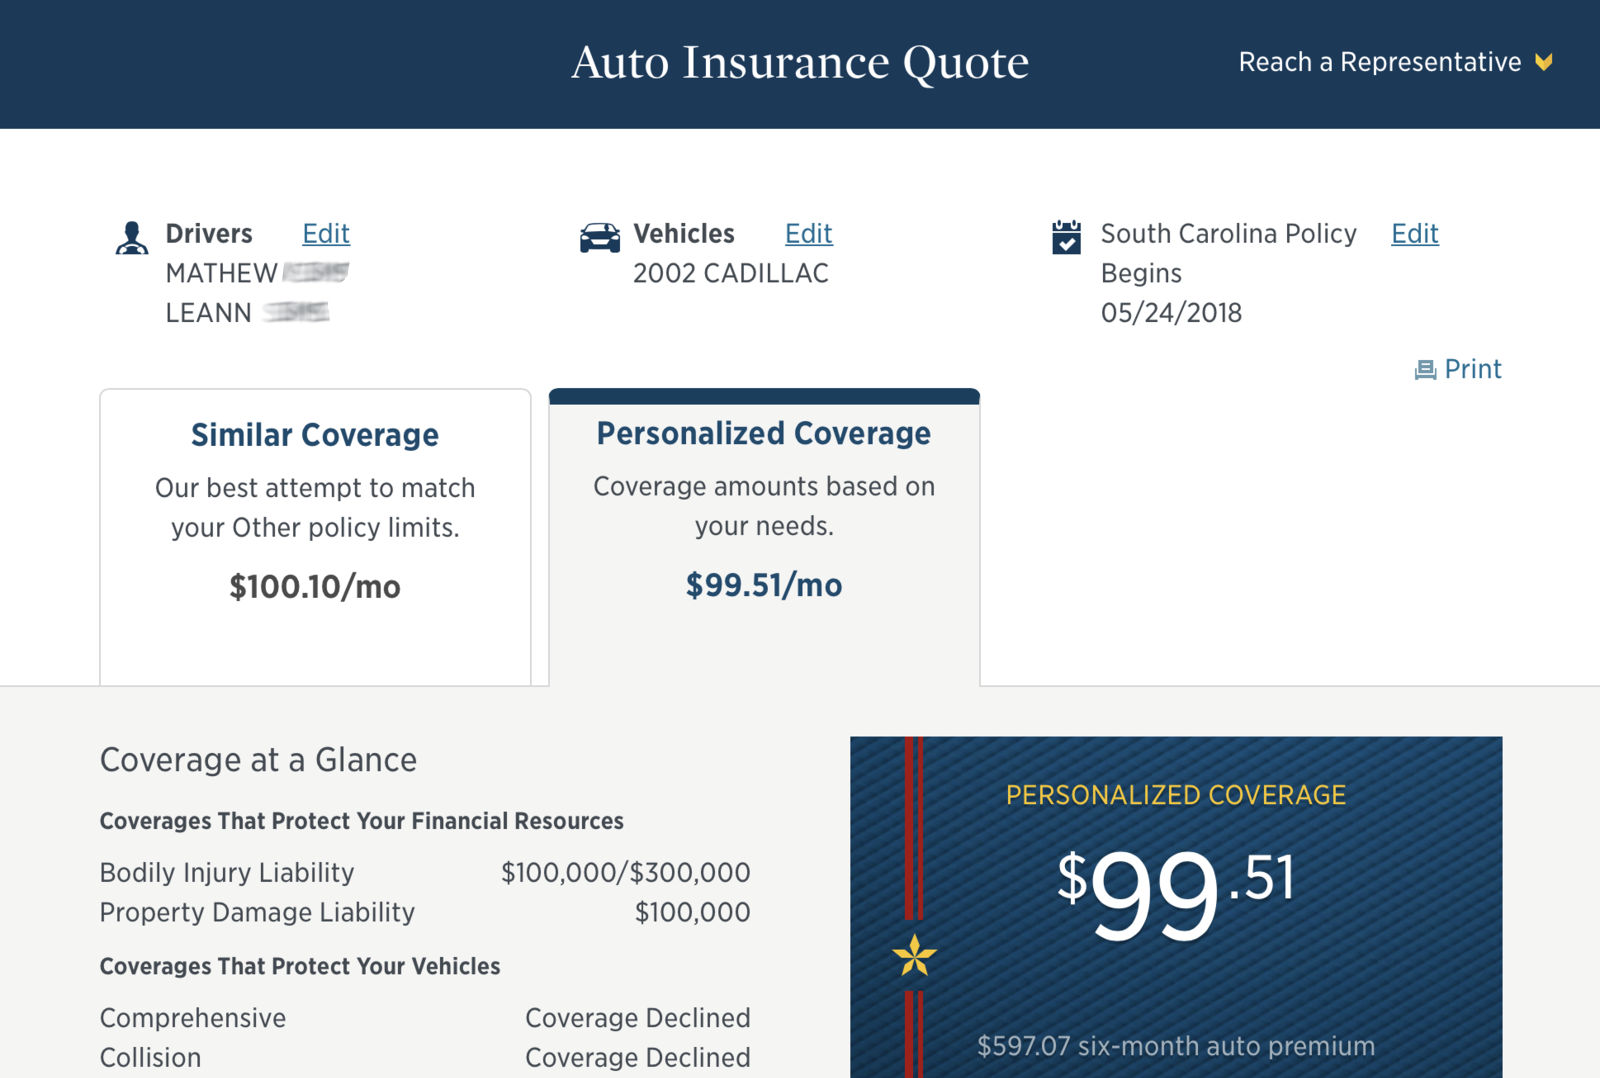
These distributions usually come in the form of dividends or credits toward future premiums. From a personal finance perspective, this reduces the “net cost” of insurance. While your monthly premium might look similar to a competitor’s, the year-end dividend can significantly lower your total annual expenditure, making it a superior long-term financial tool.
The Subscriber’s Savings Account (SSA)
One of the most distinctive financial features for certain USAA members (primarily officers and those who meet specific criteria) is the Subscriber’s Savings Account. This is not a traditional bank account but rather a portion of the company’s capital that is held in the member’s name.
Each year, a portion of USAA’s profit may be allocated to your SSA. While you cannot withdraw this money freely like a checking account, it earns interest and is paid out in full when you terminate your membership or after a certain period of senior membership. This acts as a “stealth” savings vehicle, accumulating wealth over decades of membership and providing a significant financial windfall later in life.
Integration with Banking and Investment Portfolios
For a USAA member, the car insurance policy is often the “anchor” product that leads to a wider array of financial services. USAA Bank offers competitive mortgage rates, personal loans, and credit cards with rewards programs tailored to military spending habits. By consolidating insurance and banking under one roof, members can simplify their cash flow management and often qualify for “bundle” discounts that further enhance their financial efficiency.
Maximizing Your Insurance Investment
Once eligibility is established, the focus shifts to strategic management of the policy. In the realm of personal finance, insurance is a defensive play—it protects your assets from catastrophic loss. However, at USAA, it can also be an offensive tool for saving money through various discount structures and policy optimizations.
Strategic Discount Stacking
USAA offers a variety of discounts that, when stacked correctly, can lead to substantial savings. These include:
-
Safe Driver Discounts: Rewarding those with clean records over a three-to-five-year period.
-
Vehicle Storage Discounts: A unique military-centric benefit where members can save up to 60% on premiums if they store their vehicle during a deployment.
-
Good Student Discounts: Extending the financial benefits to the younger generation by rewarding academic excellence.
-
Multi-Policy Discounts: Linking car insurance with homeowners or renters insurance to reduce the overall premium load.
Technology and Safety Features
As the automotive industry evolves, USAA has integrated technology-driven incentives. Members who drive vehicles equipped with the latest safety features—such as automatic emergency braking or lane-departure warnings—often see reduced premiums. Furthermore, USAA’s “SafePilot” program allows members to share their driving data via a mobile app in exchange for significant discounts. This is a classic example of using data to lower personal expenses, a core tenet of modern financial management.
Coverage Optimization for Wealth Protection
For high-net-worth individuals or those on the path to building wealth, standard liability limits are often insufficient. USAA allows members to easily scale their coverage and add Umbrella Insurance policies. From a financial planning perspective, this is vital. An umbrella policy provides an extra layer of protection that kicks in when your auto or home insurance limits are reached, shielding your investments and future earnings from legal judgments.
The Legacy of Financial Security
The true value of USAA car insurance lies in its long-term impact on a family’s financial health. It is not merely a monthly expense; it is an asset that provides peace of mind and financial continuity. Because membership is transferable to children, a parent’s service in the 1970s can still be providing financial benefits to a grandchild in the 2020s.
Transitioning from Military to Civilian Life
The transition period when leaving the military is often fraught with financial uncertainty. USAA acts as a stabilizing force during this time. They offer specialized guidance on how to adjust insurance coverage when moving from a base to a civilian neighborhood and how to manage the shift in income and benefits. This advisory role is part of what makes USAA a “Financial Tool” rather than just a vendor.
Longevity and Trust
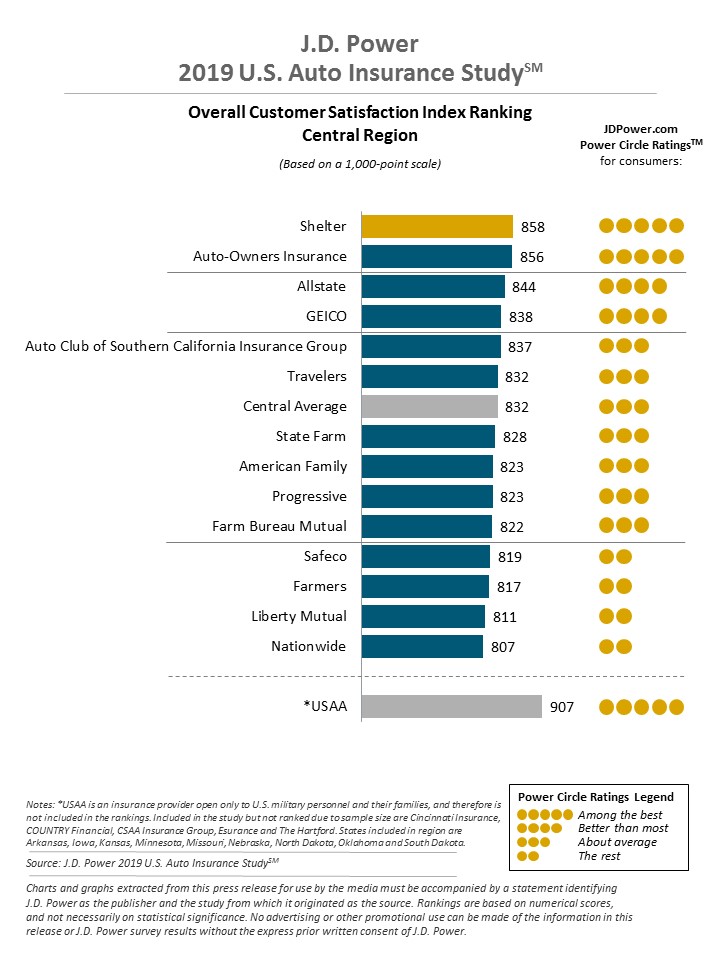
In a world where financial institutions often face scrutiny for their practices, USAA consistently ranks at the top of consumer satisfaction and trust indices. For the member, this trust translates into a more efficient claims process. In the event of an accident, a fast and fair payout is a critical component of financial recovery. A delayed or denied claim can derail a family’s budget, whereas USAA’s reputation for promptness helps maintain financial equilibrium during crises.
Conclusion: A Cornerstone of Military Personal Finance
Determining who can get USAA car insurance is more than checking a box on an application; it is about identifying whether you belong to a specific community entitled to a unique set of financial advantages. For those who qualify—active duty members, veterans, and their families—USAA represents a powerful ally in the quest for financial independence and security.
By leveraging the mutual structure of the organization, participating in specialized savings programs like the SSA, and utilizing the generational transfer of eligibility, members can ensure that their car insurance is not just a regulatory requirement, but a strategic component of their overall wealth-building strategy. In the landscape of personal finance, USAA remains a premier example of how focused, mission-driven financial services can provide unparalleled value to those who serve and have served.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.