
At first glance, the question “what is 2/3 + 1/4 in fraction form?” appears to be a straightforward mathematical problem, perhaps from a school textbook. The answer, arithmetically speaking, is simply 11/12. However, to confine our understanding to mere numbers would be to miss a profound opportunity. In the complex world of personal finance, business strategy, and investment, this simple equation serves as a powerful metaphor and a practical guide. It represents the art of combining disparate elements, finding common ground, and understanding how individual components contribute to a larger whole – lessons absolutely critical for anyone navigating the landscape of money.
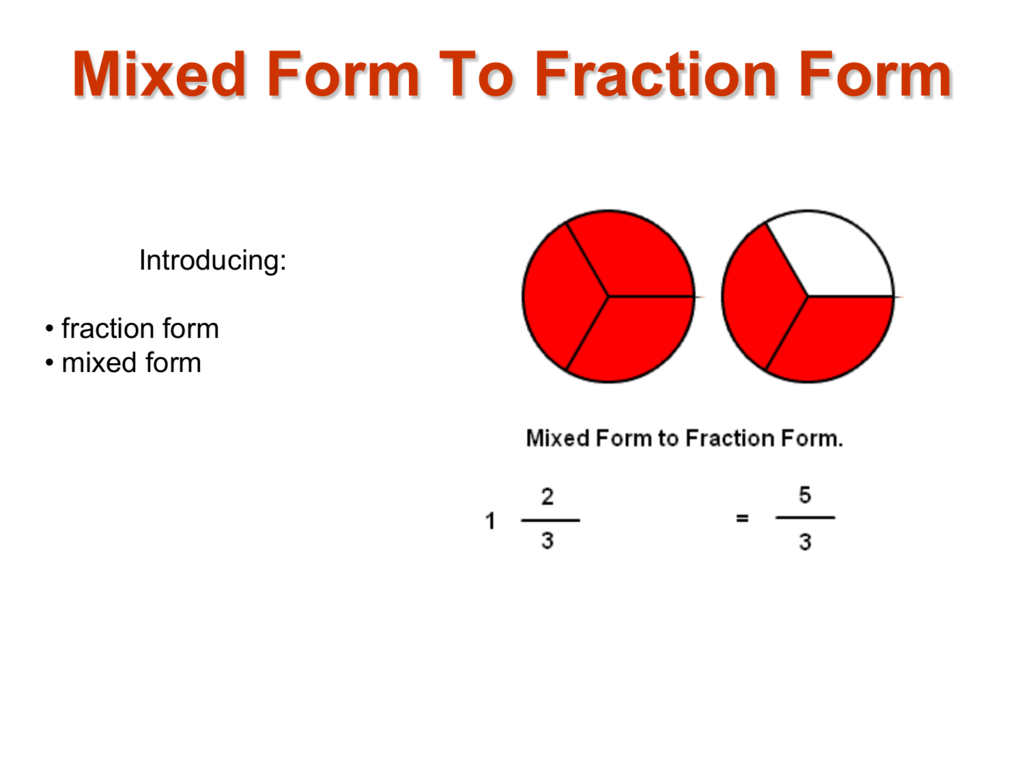
This article transcends the basic arithmetic to explore how the principles embedded in solving “2/3 + 1/4” are fundamental to building a robust financial future. From budgeting and income allocation to diversified investment strategies and wealth accumulation, understanding how different “fractions” of your financial life combine is the key to unlocking lasting financial success.
The Foundational Sum: Understanding Financial Proportions
Just as fractions represent parts of a whole, our financial lives are composed of various segments. Income is divided into expenses, savings, and investments. Assets are allocated across different classes. Businesses apportion capital to various departments and projects. The ability to understand and manage these proportions is the bedrock of sound financial health.
Deciphering the Numerator and Denominator of Your Finances
In mathematics, the numerator tells us how many parts we have, and the denominator tells us how many parts make up the whole. Financially, this translates to understanding both the absolute amounts (numerators) and their context within your total financial picture (denominators). For instance, knowing you spend $2,000 on rent is one thing; understanding that this represents 1/3 (or 2/6) of your $6,000 monthly income puts it into critical perspective.
Every financial decision involves fractions:
-
Income as a Whole: Your entire income is the ‘whole’. Each expense, saving, or investment is a ‘fraction’ of that whole.
-
Assets as a Whole: Your total net worth is the ‘whole’. Your home equity, retirement accounts, and liquid savings are ‘fractions’ of that net worth.
-
Time as a Whole: In the context of earning money, your productive hours are the ‘whole’. Time spent on a side hustle, professional development, or your primary job are ‘fractions’.
To effectively manage money, you must be able to articulate these financial fractions. Are you spending 1/2 of your income on housing? Are 3/4 of your investments tied up in a single stock? Knowing these proportions is the first step towards informed financial decision-making.
The Common Denominator: Unifying Financial Goals
The mathematical problem 2/3 + 1/4 cannot be solved directly without finding a common denominator. This step is crucial because it allows us to compare and combine unlike fractions on an equal footing. In finance, the “common denominator” represents your overarching financial goals and values. Without a clear financial vision, your efforts can become fragmented and inefficient.
Imagine you have two financial goals: saving 2/3 of a down payment for a house and setting aside 1/4 of your income for retirement. These seem like separate endeavors, but to efficiently pursue both, you need a unifying strategy – a common denominator. This might involve:
-
Prioritization: Deciding which goal takes precedence or how much capital to allocate to each based on urgency and long-term impact.
-
Integrated Planning: Using financial tools and strategies (like an automated savings plan or a balanced investment portfolio) that can serve multiple objectives simultaneously.
-
Time Horizon: Aligning the timelines for achieving different goals to create a cohesive roadmap.
A common financial denominator could be “financial independence,” “early retirement,” or “wealth preservation.” Whatever it is, it acts as the unifying principle that allows you to add up all your financial efforts and ensure they are moving you towards a single, overarching objective. Without this, your financial actions might be pulling you in different directions, much like trying to add 2/3 and 1/4 without converting them to a common base. By finding the least common multiple (LCM) – which is 12 for 3 and 4 – we transform 2/3 into 8/12 and 1/4 into 3/12, making them comparable and summable. This process mirrors the strategic thinking required to align diverse financial aspirations.
Budgeting Fractions: Allocating Your Income
One of the most immediate and impactful applications of fractional thinking in finance is budgeting. A budget is, at its core, an allocation of your total income into various categories, each representing a fraction of the whole. The popular 50/30/20 rule, for instance, is a fractional budget: 1/2 for needs, 3/10 for wants, and 1/5 for savings/debt repayment.
The 2/3 Slice: Essential Expenses and Fixed Costs
Let’s consider the “2/3” in our equation as the significant portion of your income that often goes towards essential living expenses and fixed costs. For many individuals and families, 2/3 of their take-home pay might cover:
-
Housing: Rent or mortgage payments, property taxes, home insurance.
-
Utilities: Electricity, gas, water, internet.
-
Groceries: Essential food items for daily living.
-
Transportation: Car payments, fuel, public transport, insurance.
-
Healthcare: Insurance premiums, recurring medical expenses.
Managing this substantial fraction is crucial for financial stability. If this portion consumes too much of your income (e.g., more than 2/3 or even 1/2), it can leave very little for other critical areas like savings and discretionary spending. Strategies for optimizing this “2/3 slice” include:
-
Cost Reduction: Actively seeking lower housing costs, negotiating utility bills, or optimizing grocery spending.
-
Needs vs. Wants: Rigorously distinguishing between essential needs and discretionary wants to prevent budget creep.
-
Automation: Setting up automatic payments for fixed costs to ensure they are always covered without oversight.
The goal isn’t necessarily to reduce this fraction to zero, as these are necessities, but to ensure it is managed efficiently so it doesn’t overwhelm your financial capacity.
The 1/4 Contribution: Savings, Investments, and Future Growth
The “1/4” portion of our equation represents the vital contribution towards your future financial security and growth. This is the fraction of your income that, when consistently allocated, builds wealth and provides a safety net. This 1/4 might be directed towards:
-
Emergency Fund: Building a cash reserve to cover unexpected expenses.
-
Retirement Savings: Contributions to 401(k)s, IRAs, or other pension plans.
-
Investment Portfolio: Allocations to stocks, bonds, mutual funds, or real estate for long-term growth.
-
Debt Repayment (beyond minimums): Accelerating the payoff of high-interest debts like credit cards or personal loans.
-
Future Goals: Saving for a down payment, child’s education, or a significant purchase.
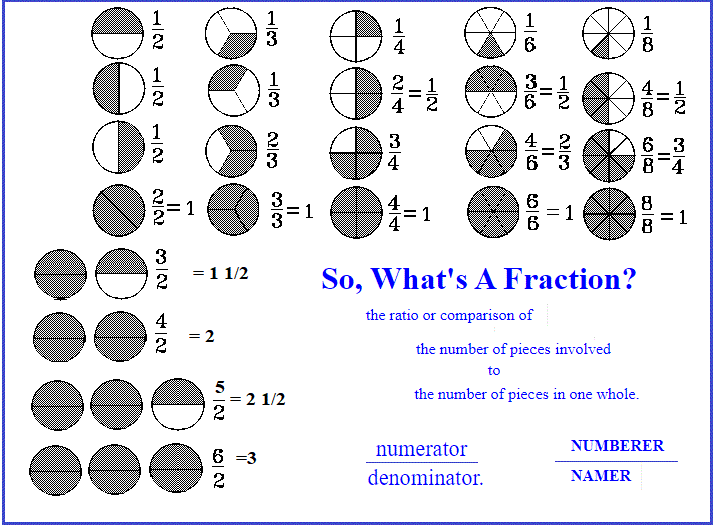
Consistently dedicating a significant fraction like 1/4 (or more, if possible) to these areas is a hallmark of strong financial discipline. Compound interest works wonders over time, but it requires a consistent principal contribution. The power of compounding means that even small, consistent fractional contributions can grow into substantial sums over time. Automating these savings and investment contributions is often the most effective way to ensure this vital fraction is consistently put to work.
The Remaining Fraction: Discretionary Spending and Lifestyle Choices
After allocating 2/3 to essential expenses and 1/4 to savings/investments, what remains?
2/3 + 1/4 = 8/12 + 3/12 = 11/12.
This leaves 1/12 of your income (1 – 11/12) for discretionary spending. This smaller fraction covers “wants” – dining out, entertainment, hobbies, travel, personal care, and non-essential purchases.
While often seen as “fun money,” this 1/12 fraction plays a critical role in quality of life and preventing financial burnout. However, it’s also the most flexible and often the first to be cut or expanded. Smart management of this fraction involves:
-
Mindful Spending: Enjoying your money without letting it erode your savings or essential funds.
-
Flexibility: Being prepared to reduce this fraction if unforeseen expenses arise or if you need to accelerate progress on a financial goal.
-
Alignment with Values: Ensuring your discretionary spending aligns with what truly brings you joy and value.
Understanding all three of these fractions – the essential 2/3, the growth-oriented 1/4, and the discretionary 1/12 – provides a complete picture of your income allocation and empowers you to make intentional choices that balance current needs with future aspirations.
Investment Portfolios: Diversification in Fractions
Beyond budgeting, the concept of fractions is central to investment strategy, particularly in diversification. A well-constructed investment portfolio is a mosaic of different asset classes, each representing a specific fraction of the total investment capital.
Weighting Your Assets: Stocks, Bonds, and Alternatives
Just as we combine 2/3 and 1/4, investors combine different asset types, each contributing to the overall portfolio’s risk and return profile. Common portfolio fractions include:
-
Stocks (Equities): Often a larger fraction for younger investors due to their higher growth potential and tolerance for volatility. For example, 2/3 of a portfolio might be in stocks.
-
Bonds (Fixed Income): A smaller, stabilizing fraction, often 1/4, providing income and reducing overall portfolio risk.
-
Alternative Investments: Commodities, real estate, or private equity might represent a smaller fraction (e.g., the remaining 1/12) for further diversification or specific market exposure.
The specific fractions allocated to each asset class depend on an individual’s age, risk tolerance, financial goals, and time horizon. A common rule of thumb for aggressive investors might be “100 minus your age” in stocks, with the remainder in bonds. For instance, a 30-year-old might have 70% (7/10) in stocks and 30% (3/10) in bonds. The beauty of fractional thinking here is that it emphasizes proportions rather than absolute dollar amounts, making the strategy scalable regardless of portfolio size.
Rebalancing and Risk Management: Adjusting Your Financial Fractions
Over time, market fluctuations will cause the initial fractions of your investment portfolio to shift. If stocks perform exceptionally well, their fraction of your total portfolio might grow from an intended 2/3 to, say, 3/4. This is where “rebalancing” comes in – an active adjustment of these fractions to bring them back to their target allocations.
Rebalancing means selling a portion of the asset class that has grown to a larger fraction (e.g., selling some stocks) and using those proceeds to buy more of the asset class that has shrunk (e.g., buying more bonds or alternative assets). This ensures that your portfolio’s risk profile remains aligned with your comfort level and financial goals. It’s akin to ensuring that 2/3 + 1/4 always equals 11/12 in terms of strategic allocation, even if market movements temporarily skew the individual components. This disciplined approach prevents any single asset class from dominating the portfolio and helps manage overall risk, ensuring your financial “sum” remains stable and aligned with your objectives.
The Sum of All Parts: Achieving Financial Wholeness
Ultimately, the act of adding 2/3 and 1/4 to get 11/12 is a journey from understanding individual components to appreciating their collective power. In finance, this translates to synthesizing all your discrete financial actions into a coherent strategy that leads to comprehensive financial well-being.
From Fragmented Goals to a Unified Financial Vision
When we manage our money without a clear framework, our financial goals can feel fragmented. We save a bit here, invest a bit there, and spend without a clear purpose. But by applying the principles of fractional thinking – understanding each component’s proportion, finding common denominators in our goals, and strategically combining our efforts – we move from financial fragmentation to a unified vision.
The “sum” of all your careful allocations, diligent savings, and intelligent investments isn’t just a larger number in your bank account; it’s the realization of financial freedom, the achievement of life goals, and the peace of mind that comes from knowing you are in control of your financial destiny. It’s about seeing your entire financial life not as a series of isolated transactions, but as a meticulously constructed equation where every fraction contributes to a powerful whole.

Continuous Calculation: Adapting Your Financial Equation Over Time
Just as a student rechecks their math, financial planning is not a one-time calculation but an ongoing process of assessment and adjustment. Life changes – incomes fluctuate, expenses shift, goals evolve, and market conditions vary. Your financial “fractions” will need continuous recalculation and re-evaluation.
-
Life Events: Marriage, children, job changes, or health issues may necessitate altering your budgeting fractions (e.g., increasing the “2/3” for needs or adjusting the “1/4” for savings).
-
Market Performance: As discussed with rebalancing, investment fractions need regular attention to stay aligned with your risk tolerance and goals.
-
Goal Shifting: As you achieve one financial goal, a new one might emerge, requiring a reallocation of your saving and investment fractions.
The constant is the process of thinking in fractions – understanding parts relative to the whole, finding common ground, and actively combining them for the best outcome. It’s about regularly asking, “Are my current financial fractions still adding up to the future I envision?”
In conclusion, while “what is 2/3 + 1/4 in fraction form?” yields the simple answer of 11/12, its true value extends far beyond basic arithmetic. In the realm of money, this humble equation provides a profound framework for understanding, managing, and optimizing our financial lives. By embracing fractional thinking, we can skillfully allocate our resources, diversify our investments, and unify our financial goals, ultimately summing up to a future of prosperity and financial empowerment.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.