
In the often-complex world of finance, where numbers and strategies can quickly become overwhelming, simplicity often holds the key to profound understanding and lasting success. The seemingly straightforward phrase “what is 1/3 1/3” might initially appear to be a mathematical query. However, when viewed through a financial lens, it transcends a mere fraction, evolving into a powerful guiding principle for proportional allocation – a cornerstone of sound money management, whether for individuals, investors, or businesses.
This principle, at its core, advocates for a deliberate, balanced distribution of resources. It invites us to consider how our income, capital, or operational budget can be optimally divided into significant, actionable segments, implying a strategy of three equally weighted parts, or perhaps two major parts with a third implicit or recurring focus. Embracing such a structured approach provides clarity, reduces financial anxiety, and lays a robust foundation for achieving diverse financial goals. By deconstructing this proportional thinking, we unlock insights into more effective budgeting, strategic investing, and sustainable wealth creation.
The Foundation of Proportional Finance: Deconstructing the “1/3 1/3” Principle
At first glance, “1/3 1/3” might seem like a simple mathematical redundancy, or perhaps a hint at two distinct one-third allocations. In the realm of money, however, its repetition underscores a critical emphasis on significant, equally weighted distribution, often implying a three-part division or a strong focus on two major areas each receiving a substantial slice of the pie. It’s more than just arithmetic; it’s a philosophical stance on how we approach our financial resources, championing balance, structure, and intentionality.
More Than Just a Fraction: A Philosophy of Balance
When we talk about “1/3 1/3” in finance, we’re not just performing a calculation; we’re adopting a mindset. It represents an intuitive, accessible way to conceptualize the division of a whole. In financial planning, the idea of splitting resources into roughly equal thirds suggests a powerful commitment to balance across key areas. This could manifest as dedicating one-third to immediate needs, another third to discretionary spending, and the final third to future savings and debt reduction. The beauty of the “1/3 1/3” principle lies in its elegant simplicity, making complex financial decisions more manageable and less daunting. It offers a clear, actionable framework that demystifies budgeting and resource allocation, enabling individuals and organizations to gain a stronger grip on their financial destiny. This proportional thinking helps prevent over-concentration in one area while neglecting others, fostering an equilibrium essential for long-term financial health.
Why Proportional Allocation Matters
The adoption of a proportional allocation strategy, like the “1/3 1/3” rule, is vital for several compelling reasons. Firstly, it significantly reduces financial stress. By assigning clear roles to different portions of your income or capital, you eliminate the guesswork and anxiety associated with discretionary spending or saving. You know precisely where every dollar should go, fostering a sense of control and predictability. Secondly, it promotes goal achievement. Whether your aim is to build an emergency fund, save for a down payment, invest for retirement, or grow your business, a structured allocation ensures that funds are consistently directed towards these objectives. This disciplined approach transforms aspirational goals into tangible realities. Thirdly, proportional allocation creates clarity and control over your money. It provides a transparent overview of your financial landscape, highlighting where your money comes from and, more importantly, where it’s truly going. Finally, it prevents overspending or under-investment in critical areas. Without a clear allocation, it’s easy for discretionary spending to creep up, or for vital savings and investments to be neglected. The “1/3 1/3” principle acts as a powerful preventative measure, safeguarding your financial future by ensuring all essential areas receive their due.
Applying the “1/3” Rule in Personal Finance: Budgeting and Savings Strategies
The “1/3 1/3” principle finds one of its most potent applications in personal finance, providing a straightforward, yet incredibly effective, framework for managing income, expenditures, and savings. This approach transforms abstract financial goals into concrete, actionable steps, making the journey to financial well-being accessible to everyone.
The “1/3, 1/3, 1/3” Budgeting Framework
A common and highly effective interpretation of the “1/3 1/3” rule for personal finance is the “1/3 Needs, 1/3 Wants, 1/3 Savings & Debt Reduction” budgeting framework. This balanced approach ensures that essential living costs are covered, personal desires are satisfied, and future financial security is actively pursued.
-
Needs (1/3 of Net Income): This category encompasses all non-negotiable expenses required for basic living. This includes housing (rent or mortgage payments), utilities (electricity, water, internet), groceries, transportation, insurance premiums, and minimum debt payments. The goal here is to keep these essential costs within one-third of your after-tax income, challenging you to live within your means.
-
Wants (1/3 of Net Income): This portion of your income is dedicated to discretionary spending – items and experiences that enhance your quality of life but are not strictly necessary. Examples include dining out, entertainment, hobbies, subscription services, new gadgets, vacations, and shopping for non-essential items. Allocating a specific third to wants allows for enjoyment and prevents feelings of deprivation, which can often derail budgeting efforts.
-
Savings & Debt Reduction (1/3 of Net Income): This crucial third is dedicated to building your financial future and reducing your liabilities. It includes contributions to an emergency fund, retirement accounts (401(k), IRA), investment portfolios, and any additional payments beyond the minimums on high-interest debts like credit cards or personal loans. This aggressive allocation ensures consistent progress towards financial independence and freedom from debt.
While similar to the popular 50/30/20 rule, the “1/3, 1/3, 1/3” framework offers a more aggressive stance on savings and debt reduction, making it particularly appealing for those aiming to accelerate their financial growth or overcome significant debt burdens.
Asset Allocation for Individual Investors
Beyond budgeting, the “1/3” principle can be a powerful tool for diversifying investment portfolios. For many investors, a balanced approach might involve allocating roughly one-third of their investment capital to different asset classes to manage risk and optimize returns. For instance, a common strategy could be:
-
1/3 Growth-Oriented Assets: Such as stocks (equities), focusing on companies with high growth potential.
-
1/3 Income-Generating Assets: Like bonds, real estate investment trusts (REITs), or dividend stocks, providing regular income streams.
-
1/3 Stability/Alternative Assets: Potentially including precious metals, cash equivalents, or other uncorrelated assets that can act as a hedge during market volatility.
This proportional distribution helps to spread risk, ensuring that a downturn in one market segment does not devastate the entire portfolio. The specific percentages will, of course, need to be tailored to an individual’s risk tolerance, age, and financial goals, but the underlying principle of balanced allocation remains universally valuable.
Debt Management with a Proportional Approach
The “1/3” rule can also be strategically applied to tackle debt. For those with multiple debts, allocating a significant portion – say, one-third of their available “savings & debt reduction” budget – specifically towards accelerating debt repayment can be transformative. This dedicated funding allows for focused efforts, whether employing the “debt snowball” or “debt avalanche” method, leading to faster debt eradication and significant savings on interest payments. The principle ensures that debt repayment is not an afterthought but a central pillar of financial planning, preventing it from spiraling out of control.
Strategic Resource Allocation in Business and Entrepreneurship
The power of proportional thinking extends far beyond personal finance, finding critical applications in the strategic management of businesses, from startups to established enterprises. The “1/3 1/3” principle, adapted for a commercial context, offers a robust framework for budgeting, equity distribution, and project management, driving efficiency and sustainable growth.
Budgeting for Business Growth and Stability
In the entrepreneurial landscape, effective budget allocation is paramount for survival and scalability. Businesses can interpret the “1/3 1/3” principle as a guide for dividing their operational budget across three critical functions to ensure balanced investment:
-
1/3 Operations & Administration: This segment covers the day-to-day costs of running the business, including salaries, rent, utilities, software subscriptions, and administrative overhead. Efficient management of this third ensures smooth functioning without excessive burn.
-
1/3 Marketing & Sales: Dedicated to customer acquisition, brand building, and revenue generation. This includes advertising, sales team commissions, public relations, and content marketing efforts. Under-investing here can stifle growth, while over-investing without adequate returns can be unsustainable.
-
1/3 Research & Development (R&D) / Innovation / Profit: This crucial third fuels future growth, product development, market expansion, and healthy profit margins. For a startup, it might be heavily weighted towards R&D to build out their offering. For an established company, it might be about strategic profit retention for reinvestment or shareholder returns. A balanced approach ensures the business not only sustains itself but also innovates and generates returns.
This proportional budgeting helps prevent common pitfalls like neglecting marketing for product development, or overspending on operations at the expense of innovation.
Equity Distribution and Profit Sharing
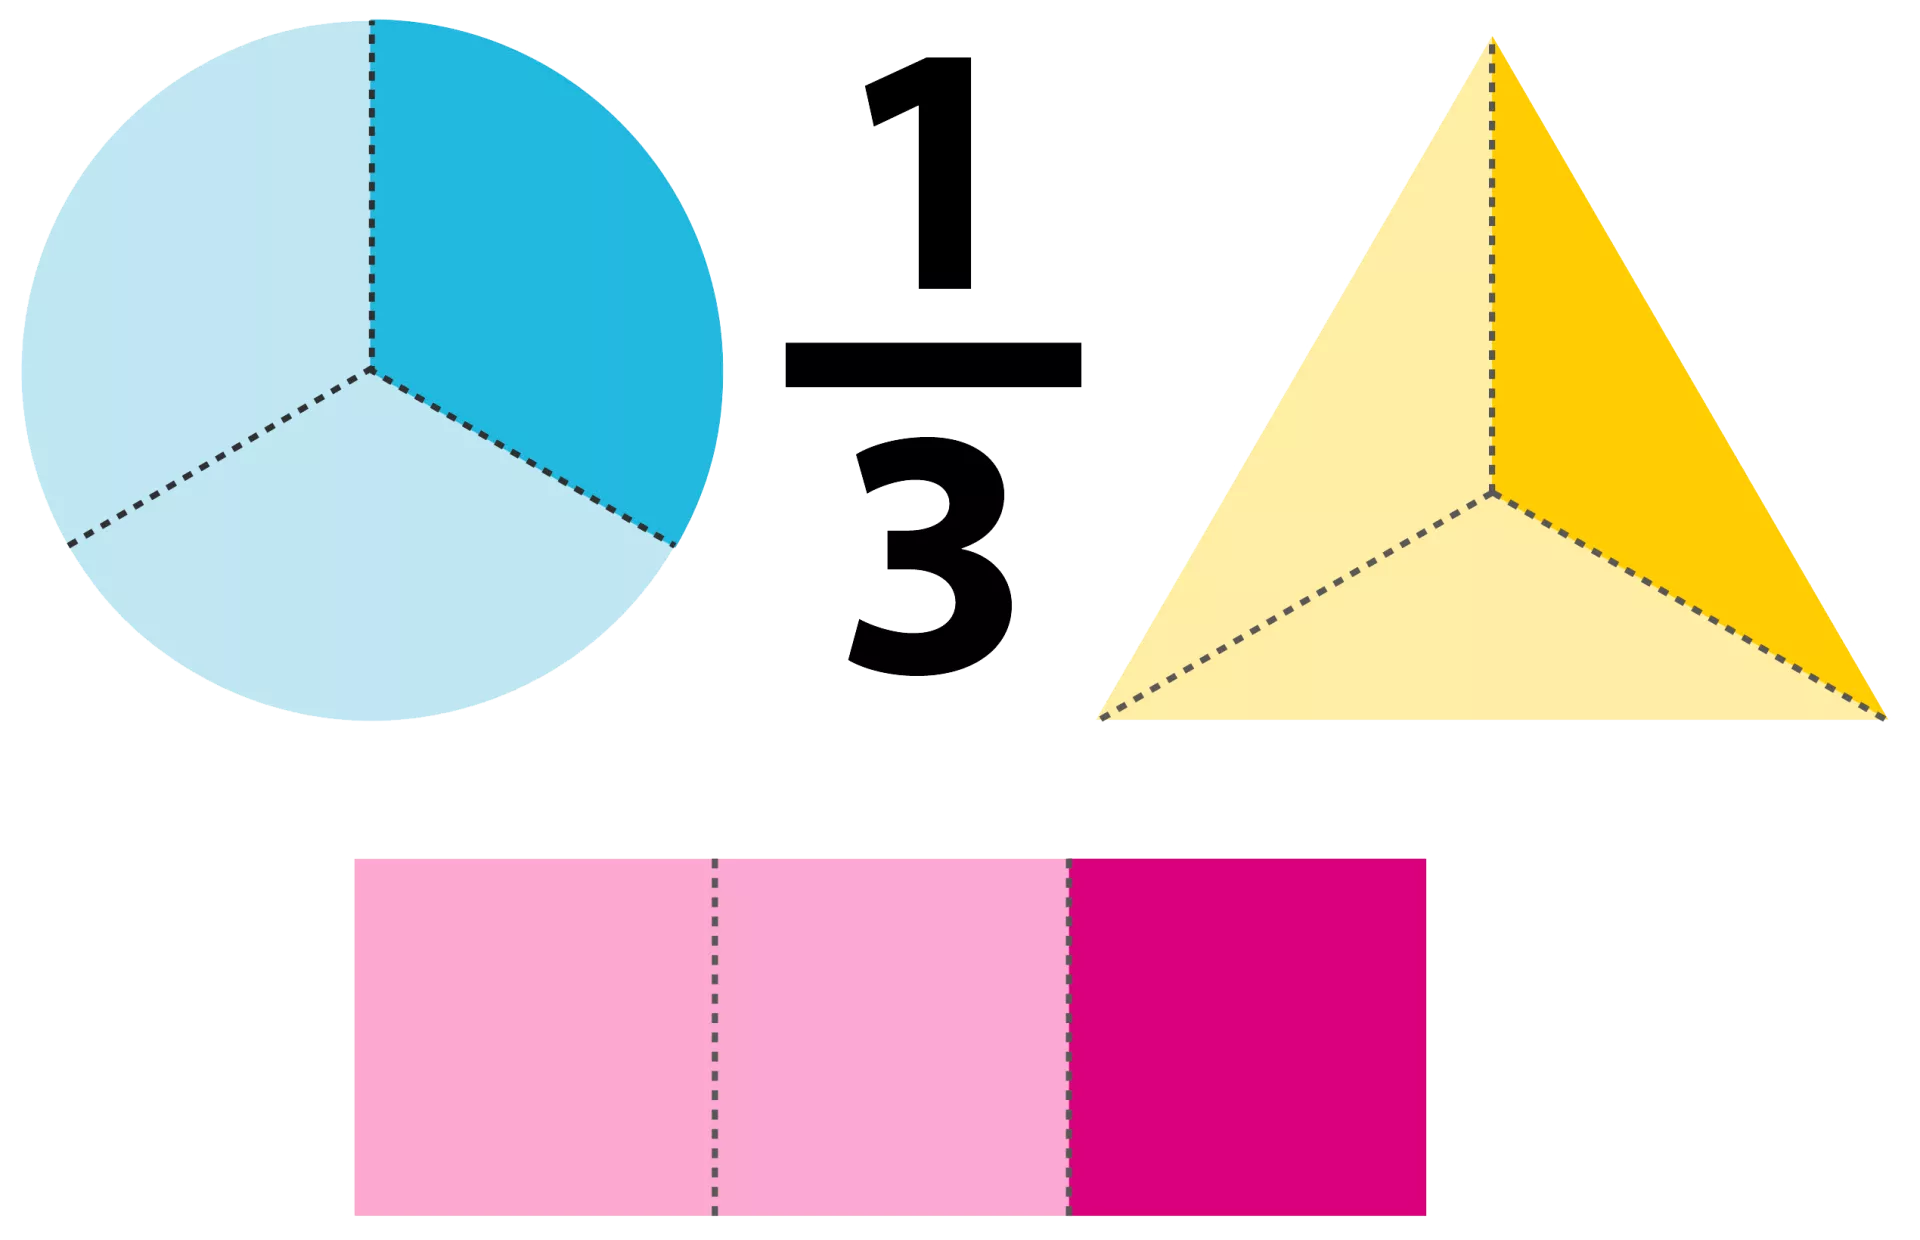
For startups and small businesses, the “1/3 1/3” principle can also influence how ownership or profits are divided, particularly among founders or key stakeholders. While exact equity splits are often more nuanced, the idea of significant, near-equal shares (e.g., three co-founders each holding roughly 1/3 of the equity initially) fosters a sense of shared ownership and commitment. Similarly, in profit-sharing schemes, a transparent proportional allocation can motivate teams and ensure fairness, recognizing the contributions of different departments or individuals. This approach promotes transparency and aligns interests, crucial for harmonious business relationships and shared success.
Project Resource Allocation
Within a larger business, individual projects can also benefit from proportional allocation of resources. Whether it’s time, budget, or personnel, dividing these resources into phases can enhance project success. For example, a major project might allocate:
-
1/3 Planning & Design: Ensuring a solid blueprint before execution.
-
1/3 Execution & Implementation: The core work of bringing the project to life.
-
1/3 Review, Testing & Iteration: Critical for quality assurance, learning, and future improvements.
This systematic approach prevents rushing into execution without proper planning or neglecting post-launch analysis, leading to more robust and successful project outcomes. The “1/3” principle encourages a comprehensive view, ensuring all stages of a business initiative receive adequate attention and resources.
Beyond the Fraction: Adaptability and Customization of Financial Rules
While the “1/3 1/3” principle offers a robust framework for financial allocation, it’s crucial to understand that it serves as a guideline, not an immutable law. The dynamic nature of life, income, and aspirations necessitates flexibility and personalization. True financial mastery lies not in rigid adherence to any single rule, but in the intelligent adaptation of principles to suit individual circumstances.
The Dynamic Nature of Your Financial Journey
Life is rarely static, and neither should your financial plan be. Major life events such as marriage, starting a family, career changes, unexpected medical expenses, or economic shifts can dramatically alter your financial landscape. A budgeting strategy that works perfectly for a single individual might be unfeasible for a family of four, just as investment allocations should shift as one approaches retirement.
The “1/3, 1/3, 1/3” rule, like any financial guideline, is a snapshot of an ideal scenario. It provides an excellent starting point and a powerful mental model for balanced resource distribution. However, recognizing that your needs, wants, and savings capacity will evolve over time is paramount. A rigid application without considering these changes can lead to frustration and ultimately undermine your financial goals.
Tailoring the Proportions to Your Goals
The beauty of proportional thinking is its inherent adaptability. While “1/3” offers a balanced baseline, you have the power to tailor these proportions to align more closely with your specific, short-term, and long-term financial goals.
-
Aggressive Savings: If you’re intensely focused on a major financial goal, such as buying a house, starting a business, or retiring early, you might choose to allocate a larger percentage – perhaps 40% or even 50% – of your income towards savings and investments, temporarily reducing the “wants” category.
-
Debt Eradication: Conversely, if you’re burdened by high-interest debt, you might temporarily increase the portion allocated to debt repayment, potentially drawing from your “wants” or even optimizing your “needs” to free up more capital.
-
Lower Income: For those with lower incomes, the “needs” category might naturally consume more than one-third of their budget, making a strict “1/3, 1/3, 1/3” split challenging. In such cases, the principle still applies by striving for the most balanced allocation possible, perhaps by minimizing “wants” and dedicating a smaller, consistent percentage to savings, even if it’s less than a full third.
-
High Income: Individuals with higher incomes might find it easier to allocate significant portions to savings and investments while still comfortably covering needs and wants, allowing them to accelerate wealth accumulation.
The key is to use the “1/3” rule as an informed starting point for a conversation with yourself about your priorities. It’s about intentionality: consciously deciding where your money goes, rather than letting it happen by default.
Regular Review and Adjustment
Financial planning is not a one-time event; it’s an ongoing process. Therefore, the “1/3 1/3” allocation, once established, should be periodically reviewed and adjusted.
-
Monthly/Quarterly Check-ins: At a minimum, review your budget and financial statements monthly or quarterly to ensure your spending aligns with your allocations. This helps catch any deviations early.
-
Annual Reassessment: Conduct a more comprehensive review annually. This is the time to consider any changes in income, expenses, major life events, or shifts in your financial goals. Perhaps your income has increased, allowing you to boost your savings. Or maybe a new car purchase means a temporary increase in “needs” (loan payment, insurance) that requires adjusting other categories.
-
Leverage Financial Tools: Utilize budgeting apps, personal finance software, or even simple spreadsheets to track your income and expenses, making it easier to monitor your adherence to the “1/3” principle and identify areas for adjustment. Automation of transfers to savings and investment accounts can also help maintain discipline effortlessly.
By embracing this dynamic and personalized approach, the “1/3 1/3” principle evolves from a static rule into a living, breathing component of your financial strategy, continuously optimized to serve your evolving aspirations.
The Psychological Impact and Long-Term Benefits of Structured Allocation
Beyond the immediate numerical advantages, adopting a structured financial allocation strategy like the “1/3 1/3” rule profoundly impacts our psychological well-being and lays the groundwork for sustainable long-term wealth creation. It transforms our relationship with money, moving it from a source of stress to a tool for empowerment.
Reducing Financial Anxiety and Decision Fatigue
One of the most immediate benefits of proportional allocation is the significant reduction in financial anxiety. When every dollar has a purpose and a designated category, the constant worry about overspending, not saving enough, or simply not knowing where your money goes dissipates. This clarity instills a sense of calm and control. Furthermore, a predefined allocation system minimizes decision fatigue. Instead of constantly debating whether to spend on a “want” or save, the decision is largely pre-made. Your budget becomes a clear roadmap, simplifying daily financial choices and freeing up mental energy for other aspects of your life. Automating transfers to savings, investment, and debt repayment accounts further reinforces this by making disciplined action effortless.
Building Discipline and Wealth Over Time
Consistency is the bedrock of wealth building, and structured allocation is its chief enabler. The “1/3 1/3” principle inherently builds financial discipline by establishing clear boundaries and promoting regular saving and investing habits. When a consistent portion of your income is dedicated to future growth, the magic of compound interest truly takes hold. Even seemingly small, consistent contributions, over time, can grow into substantial sums, thanks to the power of earning returns on your returns. This steady, disciplined approach, rather than sporadic, high-risk endeavors, is the most reliable path to accumulating significant wealth. It cultivates patience, foresight, and the invaluable habit of prioritizing future security over immediate gratification.

Achieving Financial Freedom Through Balanced Growth
Ultimately, the goal of any robust financial strategy is to achieve a degree of financial freedom – the ability to make life choices without being constrained by money. The “1/3 1/3” principle, through its emphasis on balanced growth, is a powerful accelerant towards this freedom. By ensuring that “needs” are covered, “wants” are enjoyed responsibly, and a substantial portion is consistently directed towards “savings and debt reduction,” it creates a self-reinforcing cycle of financial health.
This balanced approach prevents any single area from dominating and derailing your progress. It ensures you’re not just surviving, but thriving; not just saving, but also living; and not just accumulating, but also securing your future. The peace of mind that comes from knowing your money is intentionally working for you across different critical areas is an invaluable return on the investment of your time and discipline. It empowers you to live a richer, more intentional life, paving the way for true financial independence and lasting security.
In conclusion, “what is 1/3 1/3” transcends a mere mathematical curiosity; it represents a powerful, adaptable framework for achieving financial well-being. Whether applied to personal budgeting, investment portfolios, or business resource allocation, this principle champions balance, intentionality, and disciplined action. By embracing proportional thinking and customizing it to your unique circumstances, you gain not only greater control over your finances but also the peace of mind and clarity essential for building sustainable wealth and ultimately, realizing financial freedom. It is a testament to the idea that simplicity, when applied with purpose, can unlock profound and lasting financial success.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.