
In the world of mathematics, the answer to “what is 1/3 of 1/4” is a straightforward calculation: 1/12. By multiplying the numerators (1 x 1) and the denominators (3 x 4), we arrive at a figure that represents approximately 8.33% of a whole. While this might seem like a simple classroom exercise, the concept of a “fraction of a fraction” is one of the most powerful and often misunderstood principles in personal finance and sophisticated investing.
In the landscape of money management, understanding these small slices—the 1/12ths of the world—is the difference between passive wealth erosion and aggressive capital growth. Whether it is the impact of an expense ratio on a mutual fund, the dilution of equity in a startup, or the mechanics of fractional share investing, the ability to conceptualize and manipulate small fractions is a core competency for any serious investor.
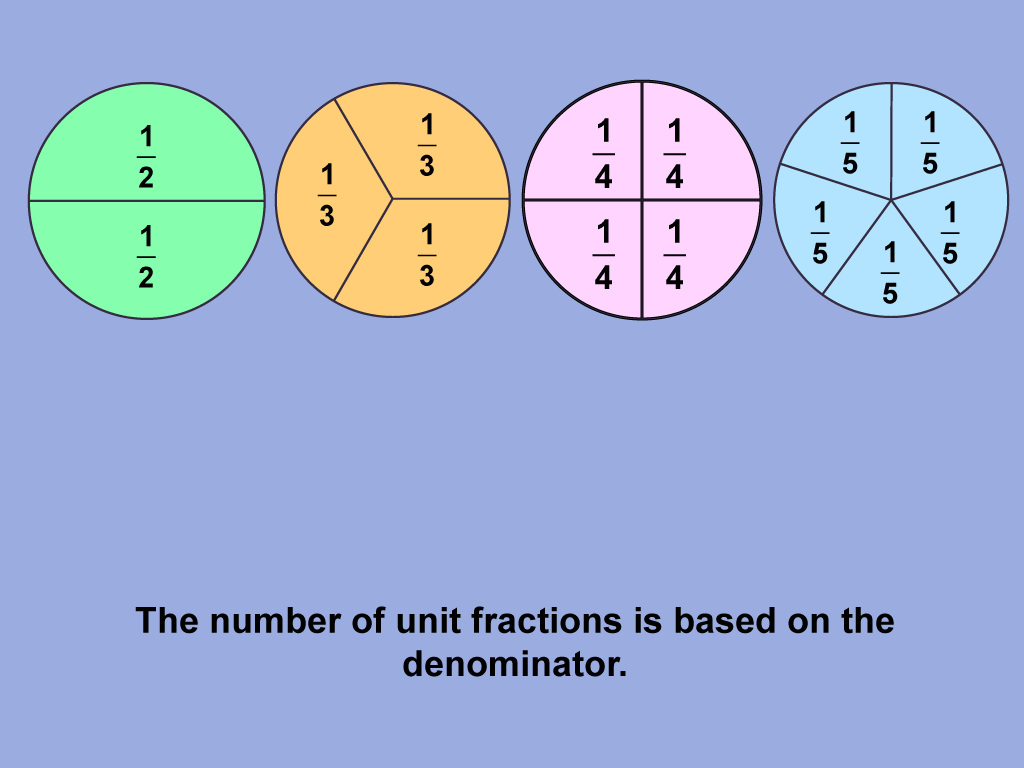
The Mathematical Foundation of Financial Slices
To understand the financial implications of 1/3 of 1/4, we must first look at what these numbers represent in a portfolio. If 1/4 represents a 25% allocation to a specific asset class—perhaps emerging markets or high-yield bonds—and that asset class undergoes a 1/3 reduction in value, your total portfolio hasn’t just dipped; it has lost 1/12 of its total value.
The Compound Effect of Small Ratios
The power of 1/12 is most evident when discussed in the context of annual versus monthly growth. Most financial targets are set annually, yet the execution happens monthly. One-twelfth of a year is a month. If an investor seeks a 10% annual return, they are essentially looking for a consistent performance that averages out to slightly less than 1% per month. When we start breaking down large financial goals into these “fractions of fractions,” the psychological barrier to investing lowers.
Why the Denominator Matters in Finance
In the fraction 1/12, the denominator (12) represents the number of parts required to make a whole. In finance, the denominator often represents the “pool.” When a company issues more shares, the denominator grows, and your “fraction” of the company shrinks. This is known as dilution. If you own 1/4 of a private company and the founders decide to issue new shares to an investor that represents 1/3 of the existing pool, your slice of the pie is fundamentally altered. Understanding the movement between these fractions allows an investor to calculate their “cost of participation” in any given venture.
Fractional Shares: The Democratization of the Market
For decades, the stock market was a game of “whole numbers.” If a single share of a high-performing tech company cost $3,000, an investor with only $500 was effectively locked out. However, the rise of fintech and brokerage innovations has turned the “1/3 of 1/4” logic into a functional investment tool: fractional shares.
Breaking Down the Barriers to Entry
Fractional share investing allows an individual to buy 1/12, 1/50, or even 1/1000 of a single share. This shift is significant because it allows for “dollar-cost averaging” regardless of share price. If you have $100 to invest monthly and want to diversify across four stocks (1/4 each), but one stock costs $300, you are forced to buy a fraction. In this scenario, you are literally buying 1/3 of a $300 share to satisfy your 1/4 allocation of your $100 budget. This mathematical flexibility ensures that your capital is always working for you, rather than sitting in a low-interest cash account waiting for a “whole” opportunity.
Precision Portfolio Rebalancing
Professional fund managers use fractional logic to maintain strict risk parameters. If a portfolio’s strategy dictates that no more than 1/4 of the assets should be in volatile sectors, and a particular stock grows to exceed that limit, the manager must sell off a fraction. By understanding the exact weight of 1/12 of a position, an investor can rebalance with surgical precision, ensuring that the risk-to-reward ratio remains optimized.
The Stealth Impact of Management Fees
If 1/3 of 1/4 (1/12) represents a gain, it is a cause for celebration. However, in the world of expense ratios and management fees, these small fractions are often the “silent killers” of long-term wealth. Many investors overlook a 1% fee, thinking it is a negligible fraction. But when viewed through the lens of your total returns, the math becomes alarming.
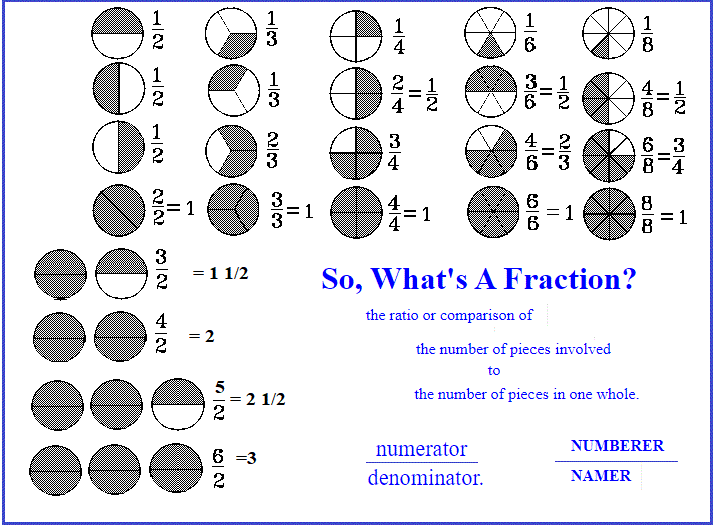
The Ratio of Fees to Returns
Imagine your portfolio earns an average of 8% per year (roughly 1/12 of your principal over time). If your advisor or the fund takes a 1% management fee, they aren’t just taking 1% of your money; they are taking 1/8 of your annual earnings. Over a 30-year horizon, that “small fraction” can result in the loss of hundreds of thousands of dollars due to the lost opportunity of compounding.
Analyzing the “Expense Slice”
When evaluating an investment, you must ask: “What fraction of my growth is being diverted?” If a fund has an expense ratio that represents 1/3 of the projected dividend yield (which might be 1/4 of the total expected return), you are effectively losing 1/12 of your potential upside before you even factor in taxes. High-net-worth individuals and institutional investors obsess over these fractions because they know that in a world of competitive markets, the person who keeps the largest fraction of their returns wins.
Asset Allocation and the 1/12 Mindset
Strategic asset allocation is the practice of dividing a portfolio into different categories to balance risk and reward. The “1/3 of 1/4” calculation is a masterclass in sub-allocation.
Diversification within Segments
A common strategy is to allocate 25% (1/4) of a portfolio to “Alternative Investments.” Within that 1/4, a savvy investor might further diversify by placing 1/3 of that specific allocation into gold, 1/3 into real estate, and 1/3 into private equity. This results in each sub-category holding 1/12 of the total portfolio value.
-
Risk Mitigation: If the real estate market crashes (the 1/12 slice), the other 11/12 of the portfolio remains intact.
-
Targeted Exposure: This allows for exposure to high-upside assets without risking the “whole” or even a “large fraction” of the total capital.
The Monthly Contribution Framework
For the average earner, wealth is built through the “1/12 rule”—investing a fraction of every monthly paycheck. If you aim to save 25% (1/4) of your income annually, but you only look at your finances once a year, you are likely to fail. By breaking that goal down into monthly increments (1/12 of the year), the task becomes an automated habit. The math of 1/12 is the math of consistency.
The Psychology of Micro-Gains and Losses
Human beings are wired to think in whole numbers. We celebrate a $1,000 gain more than a 1% increase, even if that 1% increase on a large portfolio represents $10,000. Understanding that 1/3 of 1/4 is 1/12 helps bridge the gap between abstract percentages and concrete financial reality.
Overcoming the “Too Small to Matter” Fallacy
Many people refuse to invest small amounts because they believe a small fraction of a small starting balance won’t change their lives. However, the math of compounding thrives on these small fractions. A 1/12 return (8.33%) that is reinvested every year for 25 years will result in a total that is many multiples of the original investment. In finance, no fraction is too small to be ignored.
Calculating Real Returns
To find your “real” return, you often have to subtract several fractions from your “nominal” return.
-
Nominal Return: Let’s say 12% (The whole).
-
Taxes: If you are in a high bracket, you might lose 1/4 of that to the government.
-
Inflation: You might lose another 1/3 of the remaining value to the rising cost of goods.
What is left is your real purchasing power—a fraction of the original “whole” that seemed so large at the start. Mastering the ability to calculate 1/3 of 1/4 allows you to see through the marketing fluff of financial products and understand exactly what will land in your pocket.

Strategic Conclusion: Mastering the Fractions
The question “what is 1/3 of 1/4 in a fraction” is more than a math problem; it is a fundamental lesson in financial literacy. In the quest for financial independence, the “whole” is built by the accumulation of many small parts.
By understanding that 1/12 represents a significant monthly milestone, a manageable fee threshold, or a precise slice of an asset class, investors can move away from emotional decision-making and toward mathematical certainty. In wealth building, as in mathematics, the integrity of the whole depends entirely on the management of its smallest fractions. Whether you are rebalancing a multi-million dollar fund or setting up your first $50 recurring investment, remember that the power of 1/12 is the silent engine of the financial world. Every great fortune is simply a collection of correctly managed fractions.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.