
Understanding what fractions equal 1/2 might seem like a basic mathematical concept, often revisited in grade school. Yet, its implications stretch far beyond the classroom, forming a foundational pillar for comprehensive financial literacy. Grasping the essence of equivalency – that different numerical representations can signify the exact same proportion – is not merely about arithmetic; it’s about making smarter financial decisions, optimizing your resources, and navigating the complexities of the monetary world with confidence. In the realm of personal finance, investing, business operations, and online income, the concept of “half” and its various fractional forms acts as a crucial mental model for allocation, valuation, and strategic planning.
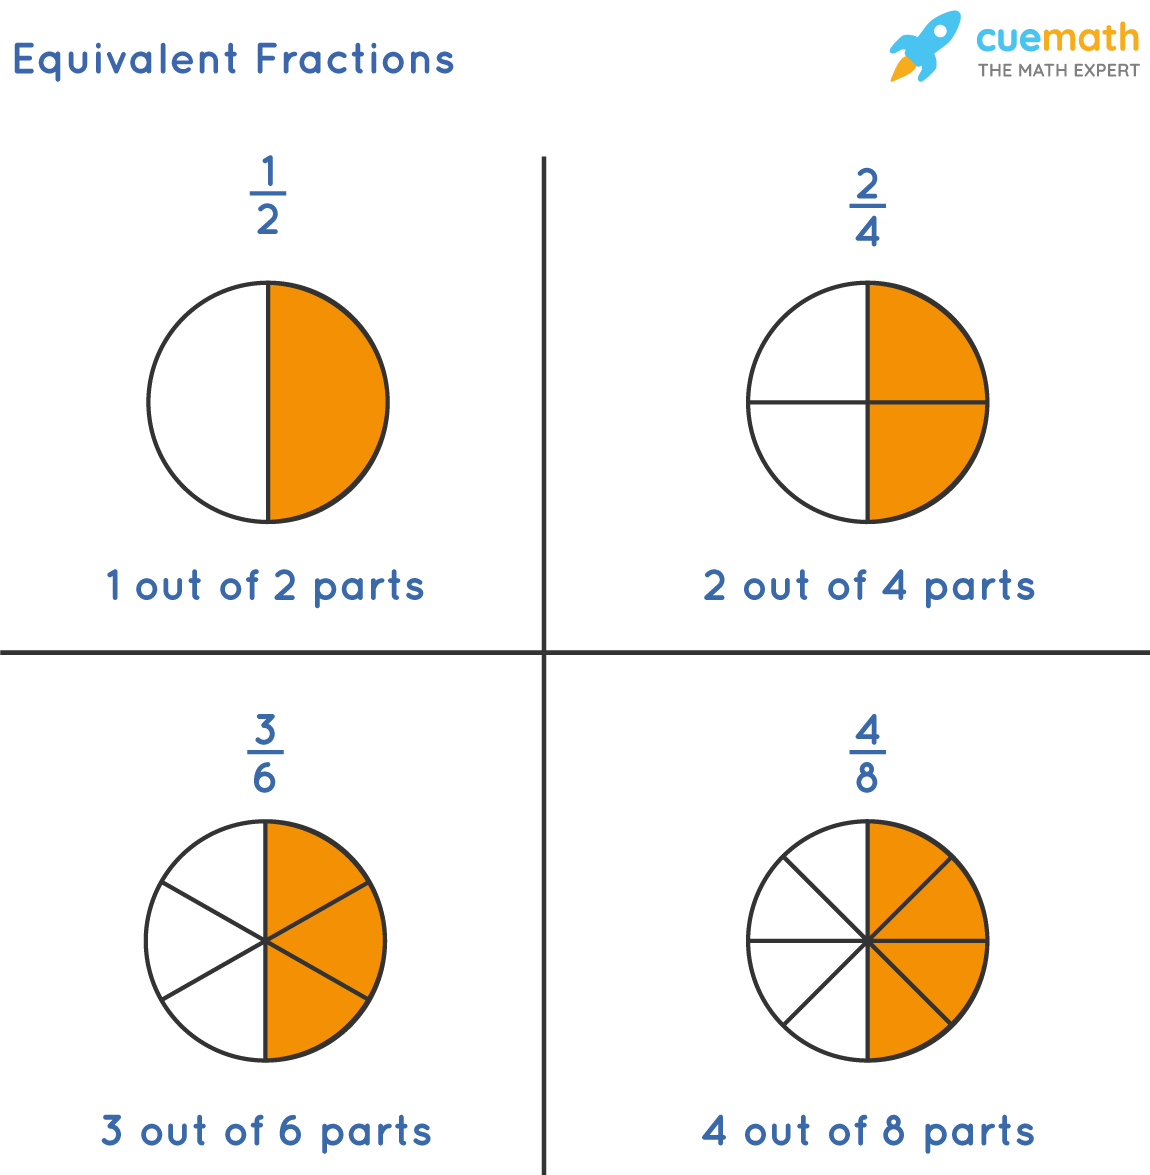
This article delves into the critical role that a deep understanding of equivalent fractions, particularly those equaling 1/2, plays in enhancing financial acumen. We will explore how this seemingly simple mathematical principle underpins budgeting, investment diversification, profit sharing, and the effective use of modern financial tools, empowering you to better manage and grow your wealth.
The Foundational Role of Fractions in Financial Literacy
At its core, financial literacy is about understanding how money works, how to manage it, and how to make it work for you. Fractions, particularly the concept of equivalency, are indispensable tools in this journey. The idea that 1/2 can also be expressed as 2/4, 3/6, 5/10, or 50/100 (which is 50%) is not just a mathematical curiosity; it’s a direct analogue to how we perceive and divide financial resources.
Beyond Simple Halves: Why Equivalency Matters for Your Wallet
The simplest way to define “what fractions equal 1/2” is any fraction where the numerator is exactly half of the denominator. Examples include 2/4, 3/6, 4/8, 50/100, and so on. In each case, if you divide the numerator by the denominator, the result is 0.5. This equivalency is vital in finance because financial realities are rarely presented in their simplest “1/2” form.
Consider a scenario where you’re evaluating a financial product that promises “half of the returns over 12 months” or a business deal offering “50% equity.” These are straightforward. But what if a mutual fund’s expense ratio is described as “1/200th of assets annually,” or a partnership offers “25/50ths of the profits”? Without understanding fractional equivalency, these numbers might seem disparate or more complex than they are. Recognizing that 25/50 is equivalent to 1/2 immediately simplifies the understanding of the profit share. This ability to translate different fractional expressions into a common understanding is paramount for clear financial analysis and decision-making. It enables you to compare terms, calculate costs, and assess value accurately, preventing misunderstandings that could lead to significant financial missteps.
Building Blocks for Budgeting and Saving
Every budget, at its heart, is an exercise in fractional allocation. You divide your total income (the whole) into various categories: housing, food, transportation, savings, debt repayment, and discretionary spending. The concept of 1/2 becomes a fundamental mental marker for significant portions. When financial experts suggest dedicating “half” of your income to needs, or saving “half” of a bonus, they are directly invoking this principle. Understanding equivalent fractions allows for more flexible and nuanced budgeting. If your rent takes up 1/4 of your income, and you realize 1/4 is equivalent to 2/8 or 25%, you can then easily calculate the remaining 3/4 or 75% for other expenses and savings. This foundational understanding empowers individuals to construct and adhere to realistic budgets, ensuring that critical financial goals, such as saving for a down payment or retirement, are consistently met.
Applying “Half” Concepts to Personal Finance
Personal finance is replete with scenarios where understanding fractions, especially the concept of 1/2, is incredibly useful. From structuring your monthly spending to strategizing for long-term goals, knowing how to interpret and apply fractional divisions is a cornerstone of effective money management.
Budgeting the 50/30/20 Rule: A Practical Application of Halves
One of the most popular budgeting frameworks, the 50/30/20 rule, directly leverages fractional understanding. This rule suggests allocating 50% of your after-tax income to “needs,” 30% to “wants,” and 20% to “savings and debt repayment.” The “50%” is, of course, a direct representation of 1/2. But the rule relies on the implicit understanding of how fractions divide a whole. If you earn $4,000 net income, 1/2 (or 50%) means $2,000 goes to needs. Understanding that 30% is 3/10 and 20% is 1/5 means you can quickly calculate $1,200 for wants and $800 for savings/debt. This fractional breakdown provides a clear, actionable roadmap for managing your cash flow, ensuring that essential expenses are covered while also prioritizing financial growth and flexibility.
Saving Strategies: Dividing Your Income for Future Growth
Saving is fundamentally about setting aside a fraction of your current income for future use. Whether it’s a general savings account, an emergency fund, or a retirement fund, you’re constantly dividing your financial pie. Many financial advisors recommend saving at least 10-15% of your income. However, some ambitious goals might require saving a larger fraction, perhaps even 1/4 or 1/3, or even 1/2 if you’re pursuing early retirement. The concept of equivalent fractions becomes useful when you break down larger savings goals. If you aim to save 1/2 of your next bonus, and that bonus is $10,000, you immediately know you’re targeting $5,000. For longer-term goals, understanding how smaller, consistent fractions add up over time is crucial. For instance, saving 1/10 (10%) of your income each month for 10 years can yield substantial results, illustrating the power of consistent fractional contributions.
Understanding Debt Repayment: The Impact of Half Measures
Debt management also benefits immensely from fractional understanding. When you make a payment, a fraction of it goes towards the principal and a fraction towards interest. Understanding “half measures” in debt can be critical. Paying only half of your minimum payment, or falling behind by half a payment, can have compounding negative effects due to interest accrual. Conversely, understanding that paying an extra half of your minimum payment consistently can significantly reduce the overall interest paid and the repayment timeline. For example, if your minimum payment is $200, consistently paying an extra $100 (which is 1/2 of the minimum) can shave years off your mortgage or credit card debt, saving you thousands. This demonstrates how even small fractional adjustments in repayment strategies can have profound long-term financial impacts.
Fractions in Investing and Wealth Building
Investing is arguably where fractional understanding transitions from helpful to absolutely essential. From structuring a diversified portfolio to comprehending market mechanics and calculating returns, fractions are the language of investment.
Portfolio Allocation: Splitting Investments for Diversification
A cornerstone of sound investment strategy is diversification, which involves spreading your investments across various asset classes to mitigate risk. This is inherently a fractional exercise. A common recommendation is the “60/40 portfolio,” meaning 60% of your assets in stocks and 40% in bonds. Here, “60%” is equivalent to 3/5, and “40%” to 2/5. Understanding that these fractions comprise the whole of your investment capital is vital. Some investors might choose a “50/50” split, or even a more aggressive “75/25” (3/4 stocks, 1/4 bonds) depending on their risk tolerance and time horizon. The ability to interpret and apply these fractional allocations allows investors to construct a balanced portfolio that aligns with their financial goals, ensuring that no single investment constitutes an overly risky or disproportionate “half” of their total holdings.

Stock Splits and Fractional Shares: Demystifying Market Mechanics
The stock market frequently uses fractional concepts. A “stock split,” for example, might be a “2-for-1” split, meaning for every one share you own, you now own two. The value of your total holding remains the same, but the price per share is effectively halved. Understanding that 1 share becomes 2, effectively making each new share represent 1/2 of the original share’s value, is crucial for not misinterpreting such events as a loss or gain.
Furthermore, the advent of fractional share investing has democratized access to high-priced stocks. Instead of needing to buy a full share of a $1,000 stock, you can invest $100 and own 1/10 (or 10%) of that share. This directly applies the concept of “what fractions equal 1/2” by allowing investors to own smaller, precise portions of companies, aligning their investment amount with their budget, rather than being dictated by the full share price.
Interest Rates and Returns: Calculating Your Share of the Pie
Interest rates and investment returns are almost always expressed as percentages, which are essentially fractions out of 100. An annual interest rate of 4.5% means you earn 4.5/100 of your principal each year. Understanding that this 4.5% is approximately 1/20 (since 100/4.5 is roughly 22) gives you a quick mental model of the proportional return. When evaluating investment products, comparing a “half-percentage point” difference in interest rates might seem small, but understanding its cumulative fractional impact over years can reveal significant differences in total earnings or debt costs. For example, an extra 0.5% (or 1/200th) on a large mortgage can amount to tens of thousands of dollars over the loan’s lifetime.
Business and Online Income: Sharing the Financial Pie
In the world of business, entrepreneurship, and online ventures, fractions dictate partnerships, profit distribution, and revenue models. The ability to precisely understand and negotiate fractional shares is critical for financial success and equitable agreements.
Profit Sharing and Commission Structures: Earning Your Half (or More!)
Many business models involve profit sharing. In a partnership, two individuals might agree to a 50/50 split of the profits, meaning each partner receives 1/2 of the net earnings. For sales professionals, commission structures often involve a fraction of the sale price. Earning “half of the commission” from a referral or “a 1/4 share” of a large project’s revenue directly translates to these fractional calculations. A clear understanding of these fractions ensures that all parties know their rightful share and can accurately forecast their income. Misinterpreting a “one-eighth” share as a “half” could lead to severe financial disappointment or conflict.
Cost Analysis and Margin Calculation: The Half that Matters for Profit
Businesses constantly deal with costs and revenues, and the difference between them determines profit margins. Understanding that cost of goods sold (COGS) might consume “half” of your revenue, leaving the other “half” to cover operating expenses and profit, is fundamental. If your gross profit margin is 50% (1/2), it means for every dollar of revenue, 50 cents is left after COGS. Knowing that 1/2 of your revenue disappears before you even pay your staff or rent emphasizes the importance of controlling costs and optimizing pricing. For online businesses, this might translate to understanding that payment processing fees take a small but significant fraction (e.g., 2.9% + $0.30 per transaction), which can accumulate to a substantial “half” of the profit on smaller sales.
Revenue Splits in Partnerships and Ventures
Online content creators, app developers, and various digital entrepreneurs often engage in revenue-sharing agreements with platforms or collaborators. A common scenario involves a 70/30 split, where the creator gets 70% (7/10) and the platform gets 30% (3/10). Some may offer a 50/50 split, especially in joint ventures or affiliate marketing. Understanding what fractions equal 1/2, and how these larger fractions (like 7/10 or 3/10) relate to it, allows business owners to evaluate the fairness and profitability of different platform deals or collaborations. It enables them to predict their actual take-home earnings, which is critical for business sustainability and growth.
Leveraging Fractional Understanding with Financial Tools
Modern financial technology (fintech) has simplified many complex calculations, but the underlying logic often relies on fractional understanding. Being able to interpret the data presented by these tools requires a grasp of the basic principles discussed.
How Budgeting Apps Use Fractional Logic
Budgeting apps like Mint, YNAB, or Rocket Money automatically categorize your spending and display your financial health using pie charts, bar graphs, and percentages. These visual representations are direct applications of fractional thinking. When an app shows that “50%” of your income went to housing this month, it’s explicitly stating that 1/2 of your money was allocated there. Understanding that 50% is 1/2 helps you quickly assess if you’re overspending on certain categories according to your budget goals (e.g., if your housing budget was only 1/3 of your income). These tools make fractional management intuitive, but your ability to act on the insights comes from understanding the underlying mathematical relationships.
Investment Platforms and Fractional Calculations
Online brokerage platforms provide detailed breakdowns of portfolio performance, asset allocation, and individual stock/fund performance. They display percentages for gains/losses, expense ratios for funds, and the composition of your portfolio. When a platform indicates that “1/2 of your portfolio is in tech stocks,” or that a particular fund has an expense ratio of “0.75%,” a strong fractional understanding allows for immediate comprehension of the financial implications. The ability to quickly grasp that 0.75% is less than 1% but still represents 3/400th of your investment value annually, empowers you to make informed decisions about fees and diversification presented by these sophisticated tools.
Demystifying Financial Reports and Statements
Whether it’s a personal credit card statement, a bank statement, or a business’s profit and loss (P&L) statement, these documents are filled with numbers that represent fractions of a whole. A credit card statement might show “minimum payment due: 1/50th of balance,” or a P&L might show “gross profit margin: 45% (or 9/20ths).” Understanding these fractional relationships allows you to quickly discern key performance indicators, identify areas of concern (e.g., where is more than “half” of my income going?), and make proactive financial adjustments. This skill is critical for anyone looking to go beyond superficial numbers and truly understand the financial health of their personal or business accounts.

Empowering Your Financial Journey with Fractional Knowledge
From a simple child’s allowance to multi-million-dollar investment portfolios, the principle of “what fractions equal 1/2” and its broader implications for fractional understanding are ubiquitous in the world of money. It provides a fundamental framework for perceiving proportions, allocating resources, and evaluating financial opportunities and risks. By mastering this seemingly basic mathematical concept, individuals and businesses alike can unlock a deeper level of financial literacy, leading to more informed decisions, greater control over their economic future, and ultimately, enhanced wealth creation. So, the next time you encounter a percentage, a ratio, or a division of resources, remember the power of fractions – particularly the simple yet profound concept of a half – in guiding your financial journey.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.