
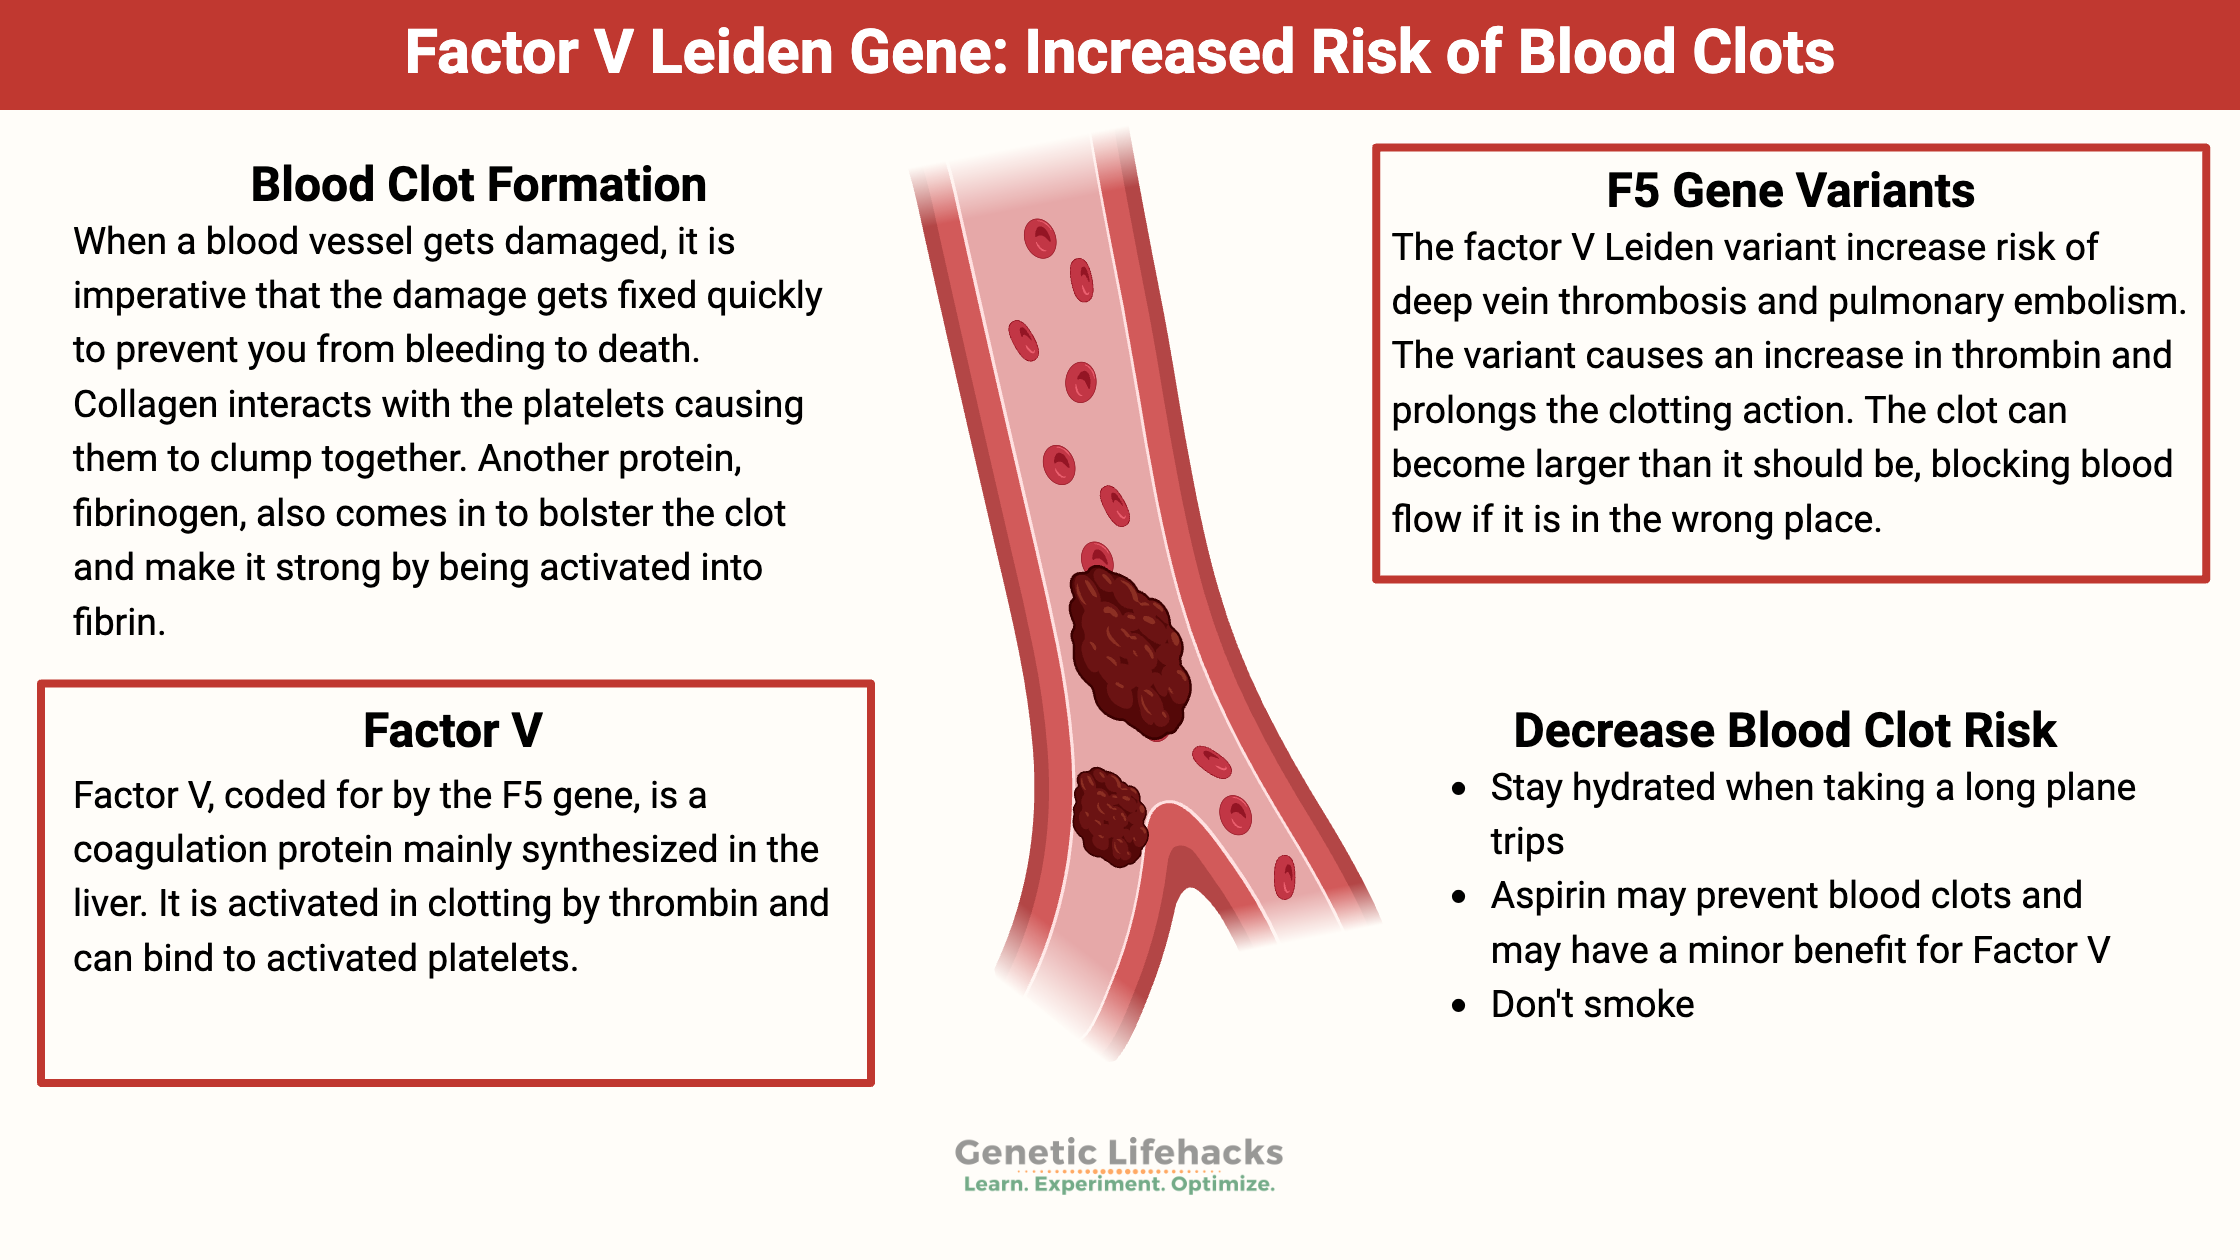
Factor V Leiden, a common genetic mutation, is primarily known for increasing an individual’s risk of developing blood clots. While its medical implications are extensively studied, the financial ramifications for individuals and families managing this condition often remain an overlooked aspect. Living with a genetic predisposition that requires ongoing vigilance and potential medical intervention can introduce a unique set of financial challenges, spanning everything from routine diagnostic costs to emergency care, insurance complexities, and long-term financial planning. This article delves into the “Money” niche, exploring the economic landscape surrounding Factor V Leiden, providing insights into navigating its financial complexities, and offering strategies for fiscal preparedness and resilience.
The Hidden Costs of a Genetic Predisposition
The journey of managing Factor V Leiden, from initial discovery to lifelong vigilance, is punctuated by a series of costs that can accumulate significantly over time. Understanding these financial touchpoints is crucial for effective budgeting and long-term planning.
Diagnostic Expenses and Initial Consultations
The first financial hurdle often comes with diagnosis. Suspecting a clotting disorder typically leads to a series of medical consultations and specialized laboratory tests. A general practitioner’s visit might lead to a referral to a hematologist or a geneticist, each involving co-pays or deductibles. The specific blood tests required to identify the Factor V Leiden mutation – often including genetic testing and coagulation factor assays – can be expensive, ranging from hundreds to potentially thousands of dollars depending on insurance coverage, lab fees, and the complexity of the diagnostic process. While some of these costs may be covered by insurance, out-of-pocket maximums and deductibles can mean a substantial initial outlay for individuals seeking a definitive diagnosis. It’s essential for individuals experiencing symptoms or with a family history of clotting disorders to understand the potential costs associated with this initial diagnostic phase and to verify their insurance benefits beforehand.
Lifelong Management: Medication and Monitoring
Once diagnosed, managing Factor V Leiden often involves ongoing monitoring and, for many, prophylactic or therapeutic medication. Individuals who have experienced a blood clot or are deemed at high risk may be prescribed anticoagulants (blood thinners) such as warfarin, rivaroxaban, apixaban, or dabigatran. The cost of these medications can vary widely. While generic versions might be relatively affordable, newer, brand-name anticoagulants can cost hundreds of dollars per month without adequate insurance coverage or manufacturer assistance programs.
Beyond medication, regular blood tests are often necessary to monitor clotting factors, assess medication efficacy, and check for side effects. For those on warfarin, frequent INR (International Normalized Ratio) testing is critical to ensure the blood’s clotting time is within a safe therapeutic range. These tests, while routine, incur costs with each visit to a lab or clinic, and home testing kits, though convenient, also represent an upfront investment. These recurring expenses for medication and monitoring form a significant ongoing financial commitment that must be factored into an individual’s budget indefinitely.
Emergency Care and Hospitalizations: The Unexpected Burden
Perhaps the most significant financial risk associated with Factor V Leiden stems from the potential for emergency events. If a blood clot does occur, especially in critical areas like the lungs (pulmonary embolism), brain (stroke), or deep veins (deep vein thrombosis), immediate and intensive medical intervention is often required. Emergency room visits, hospitalization stays (which can extend for days or weeks), specialized imaging like CT scans or MRIs, and procedures like thrombectomy can quickly accumulate bills reaching tens or even hundreds of thousands of dollars.
Even with robust health insurance, the out-of-pocket costs for such catastrophic events – including deductibles, co-insurance, and uncovered services – can be financially devastating. These unexpected expenses can deplete savings, force individuals into debt, or impact long-term financial stability. This potential for high-cost emergency care underscores the importance of not only diligent management of the condition but also comprehensive financial planning to mitigate the impact of unforeseen medical crises.
Navigating the Insurance Labyrinth
Insurance plays a pivotal role in cushioning the financial blow of Factor V Leiden. However, understanding the intricacies of various insurance products and how they apply to a pre-existing genetic condition is critical.
Health Insurance Coverage: What to Look For
Selecting the right health insurance plan is paramount. Individuals with Factor V Leiden need a plan that offers comprehensive coverage for specialist visits (hematologists), prescription medications (anticoagulants), laboratory tests, and potential emergency care. Key aspects to scrutinize include:
-
Formulary: Ensure prescribed medications are on the plan’s approved drug list, ideally in a preferred tier to minimize co-pays.
-
Network: Verify that key specialists and preferred hospitals are in-network to avoid higher out-of-network charges.
-
Deductibles, Co-pays, and Out-of-Pocket Maximums: Understand these figures thoroughly. A lower premium plan might have a high deductible, leaving you vulnerable to significant costs before coverage kicks in. A higher premium plan with lower deductibles and co-pays might be more cost-effective in the long run given ongoing needs.
-
Genetic Testing Coverage: While the Affordable Care Act (ACA) prevents insurers from denying coverage or charging more based on pre-existing conditions, individuals seeking a new diagnosis should confirm coverage for genetic testing specifically, as it can vary.
Proactive research and consultations with insurance providers are essential to ensure the chosen plan adequately addresses the unique medical needs and associated financial risks of Factor V Leiden.
Life Insurance and Disability Coverage: Planning for the Unknown
Beyond health insurance, individuals with Factor V Leiden should consider how their condition impacts other forms of personal financial protection.
-
Life Insurance: While Factor V Leiden increases the risk of certain health complications, it is often manageable. However, it can still be considered a pre-existing condition by life insurance companies. Applicants may face higher premiums, or in some rare cases, specific exclusions related to clotting events. It’s advisable to apply for life insurance earlier in life, before significant health events occur, to potentially secure better rates. Working with an independent insurance agent who understands medical conditions can help navigate options from various carriers.
-
Disability Insurance: If a severe clotting event (like a stroke or pulmonary embolism) leads to temporary or permanent disability, disability insurance can provide crucial income replacement. This is especially vital for those whose livelihoods depend on physical presence or specific cognitive functions. Short-term disability (STD) and long-term disability (LTD) policies should be explored, both through employers and individual policies. Again, pre-existing condition clauses and waiting periods will be important considerations. Securing robust disability coverage can act as a critical safety net against the potential loss of income due to severe health complications.
Pre-existing Conditions and Policy Implications
Thanks to legislation like the ACA, health insurers can no longer deny coverage or charge more due to pre-existing conditions. However, this doesn’t erase all complexities. When changing plans, there might be waiting periods for certain benefits or specific treatments. For life and disability insurance, while denial based solely on Factor V Leiden is unlikely, the actuarial risk assessment will factor it in. Transparency with insurance providers is key, but also understanding your rights and available protections is crucial. Seeking guidance from financial advisors or patient advocacy groups can illuminate the best pathways for securing comprehensive coverage.
Financial Planning for Long-Term Health Management
Effective financial planning is not just about saving for retirement; it’s also about building resilience against life’s uncertainties, especially when managing a chronic health condition.
Building a Health Savings Account (HSA) or Flexible Spending Account (FSA) Strategy
For those eligible, Health Savings Accounts (HSAs) and Flexible Spending Accounts (FSAs) are powerful financial tools to mitigate healthcare costs.
-
HSAs: Coupled with high-deductible health plans (HDHPs), HSAs offer a triple tax advantage: tax-deductible contributions, tax-free growth, and tax-free withdrawals for qualified medical expenses. This makes them an excellent vehicle for saving for both routine and unexpected medical costs associated with Factor V Leiden. The funds roll over year to year and are portable, making them a long-term savings asset.
-
FSAs: While “use-it-or-lose-it” rules apply more strictly than HSAs, FSAs still allow pre-tax dollars to be set aside for eligible medical expenses, reducing your taxable income. For individuals with predictable annual medical costs (medications, routine tests), an FSA can offer immediate tax savings.
Strategically utilizing one of these accounts can significantly reduce the overall financial burden of managing Factor V Leiden, turning a portion of your healthcare spending into a tax-advantaged investment.
Budgeting for Chronic Condition Expenses
Integrating Factor V Leiden-related expenses into a household budget is non-negotiable. This involves:
-
Tracking All Medical Expenses: Keep detailed records of all doctor visits, lab tests, prescriptions, and medical supplies.
-
Allocating Specific Funds: Dedicate a portion of your monthly budget specifically to medical co-pays, prescription refills, and anticipated tests.
-
Building an Emergency Fund: Beyond general emergency savings, consider a dedicated medical emergency fund to cover unexpected deductibles, co-insurance, or non-covered services related to a clotting event. Aim for at least 3-6 months of medical expenses, if possible.
-
Reviewing Annually: Healthcare costs can change, as can insurance plans and medication prices. Review and adjust your medical budget annually to ensure it remains realistic and effective.
Proactive budgeting ensures that managing Factor V Leiden doesn’t lead to financial distress, providing a clearer picture of your ongoing financial commitments.
Estate Planning Considerations
While not directly about daily costs, Factor V Leiden can subtly influence estate planning. Individuals with the condition might want to ensure their estate plans reflect the potential for health complications, especially if there are dependents or significant assets. This could involve:
-
Power of Attorney: Establishing a medical power of attorney and financial power of attorney ensures that trusted individuals can make decisions on your behalf if you become incapacitated due to a medical event.
-
Living Will/Advance Directives: Documenting your wishes for medical care in advance can prevent difficult decisions for family members and ensure your preferences are respected.
-
Contingency Planning: Reviewing beneficiary designations on all financial accounts and insurance policies to ensure they align with your current wishes, particularly if the condition impacts your long-term health outlook.
While Factor V Leiden doesn’t automatically mean a shorter lifespan, planning for all contingencies is a hallmark of responsible financial management.
Impact on Income and Employment
Beyond direct medical costs, Factor V Leiden can have a ripple effect on an individual’s earning potential and employment trajectory.
Managing Work-Life Balance with Chronic Health Needs
Living with Factor V Leiden, particularly after experiencing a blood clot or while on continuous medication, often necessitates a mindful approach to work-life balance. Regular doctor’s appointments, blood tests, and the potential for side effects from medication can impact work productivity and attendance. This may lead to:
-
Reduced Hours or Flexible Work Arrangements: Some individuals might need to transition to part-time work or seek employers offering flexible schedules to accommodate medical needs, potentially impacting income.
-
Career Changes: In some cases, high-stress jobs or roles requiring extensive travel might be deemed too risky or difficult to manage, prompting a career change that could affect earning capacity.
-
Fatigue and Energy Levels: Chronic health conditions, even when well-managed, can sometimes lead to fatigue or decreased energy, impacting one’s ability to maintain demanding work schedules or pursue promotions.
Open communication with employers (where appropriate and legally protected) and understanding workplace accommodations are vital for balancing health needs with career aspirations.
Short-Term and Long-Term Disability Benefits
Should a significant blood clot event or related complication render an individual unable to work for an extended period, disability benefits become a financial lifeline.
-
Short-Term Disability (STD): Typically offered through employers, STD provides a percentage of your salary for a limited period (e.g., 3-6 months) if you are temporarily unable to work due to illness or injury.
-
Long-Term Disability (LTD): This can be employer-provided or purchased individually. LTD kicks in after STD benefits expire and can provide income for years, sometimes until retirement, depending on the policy terms.
-
Social Security Disability Insurance (SSDI): For severe, long-term disabilities that prevent individuals from engaging in substantial gainful activity, SSDI provides benefits based on one’s work history.
Understanding eligibility requirements, waiting periods, and benefit amounts for all these options is essential. These benefits can bridge income gaps during periods of incapacitation, preventing financial ruin.
Career Adjustments and Financial Resilience
The long-term nature of Factor V Leiden means that career planning might need to be approached with an eye towards resilience. This could involve:
-
Skill Diversification: Developing skills that allow for remote work or more flexible employment options.
-
Building a Financial Safety Net: Beyond an emergency fund, having diversified investments and multiple income streams can provide stability if health issues impact primary employment.
-
Considering Less Physically Demanding Roles: For individuals in physically demanding jobs, proactive consideration of less strenuous career paths might be prudent over the long term.
A proactive approach to career management, combined with robust financial planning, empowers individuals to maintain financial stability despite potential health challenges.
Leveraging Financial Tools and Support Systems
Navigating the financial landscape of Factor V Leiden doesn’t have to be a solitary journey. A variety of tools and support systems exist to help alleviate the burden.
Patient Assistance Programs and Pharmaceutical Discounts
The high cost of prescription medications, especially newer anticoagulants, can be a major hurdle. Fortunately, several resources can help:
-
Pharmaceutical Manufacturer Programs: Many drug manufacturers offer patient assistance programs (PAPs) or co-pay cards to help eligible individuals afford their medications.
-
Non-Profit Organizations: Organizations focused on blood disorders or cardiovascular health sometimes provide financial aid or guidance on accessing affordable medications.
-
Discount Card Programs: Websites and apps like GoodRx offer coupons and discount cards that can significantly reduce prescription costs, even for those with insurance.
Investigating these programs can lead to substantial savings on ongoing medication expenses, making treatment more accessible and sustainable.
Financial Advisors Specializing in Health-Related Planning
A specialized financial advisor can be an invaluable asset. Some advisors have expertise in helping clients manage finances around chronic health conditions, disability planning, or long-term care needs. They can:
-
Create Tailored Financial Plans: Develop a comprehensive financial strategy that accounts for anticipated medical costs, insurance gaps, and potential income fluctuations.
-
Optimize Insurance Portfolios: Help evaluate and select the most appropriate health, life, and disability insurance policies.
-
Guide Investment Strategies: Advise on how to build savings and investments while factoring in health-related risks and expenses.
-
Navigate Benefits and Resources: Connect individuals with relevant patient assistance programs, government benefits, or community support.
Engaging such a professional can provide peace of mind and ensure a holistic approach to financial well-being.

Community Resources and Advocacy Groups
Connecting with others who understand the challenges of Factor V Leiden can offer both emotional and practical support.
-
Patient Advocacy Groups: Organizations like the National Blood Clot Alliance (NBCA) provide resources, educational materials, and often have sections dedicated to financial aid or navigating insurance. They can also connect individuals with support networks.
-
Online Forums and Support Groups: These platforms offer a space to share experiences, ask questions, and learn from others who are managing similar financial and medical complexities.
-
Hospital Social Workers: Many hospitals have social workers who can provide information on local resources, financial assistance programs, and support services.
Leveraging these communities can provide valuable insights, emotional encouragement, and practical advice for managing the financial aspects of Factor V Leiden.
In conclusion, while Factor V Leiden is a medical condition, its shadow extends deeply into the financial lives of those affected. From the initial diagnostic tests to lifelong medication, potential emergency care, and impacts on income and insurance, the monetary implications are substantial. By understanding these costs, strategically navigating insurance, engaging in meticulous financial planning, and leveraging available support systems, individuals with Factor V Leiden can build a robust financial framework that fosters resilience and allows them to focus on their health with greater peace of mind.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.