
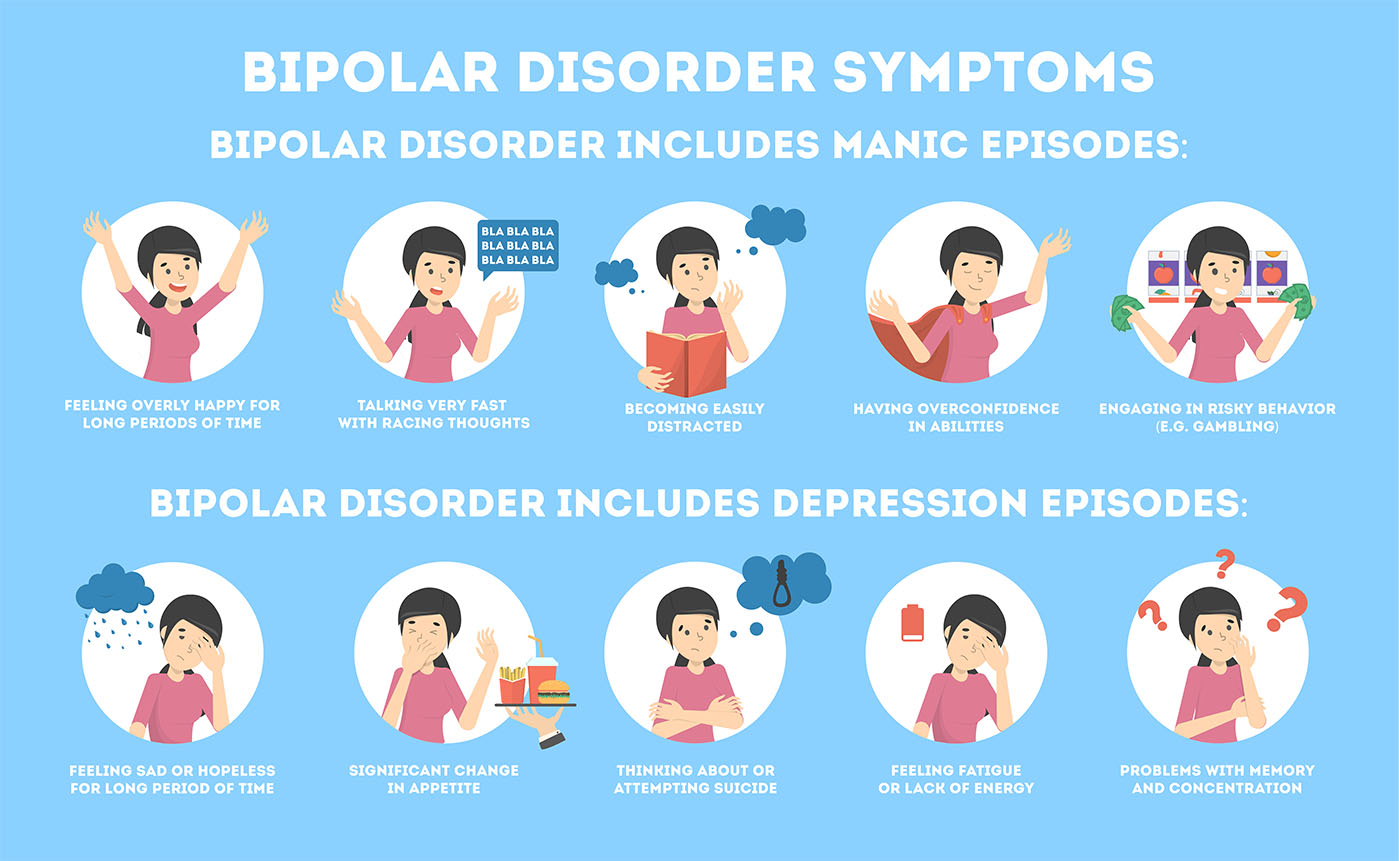
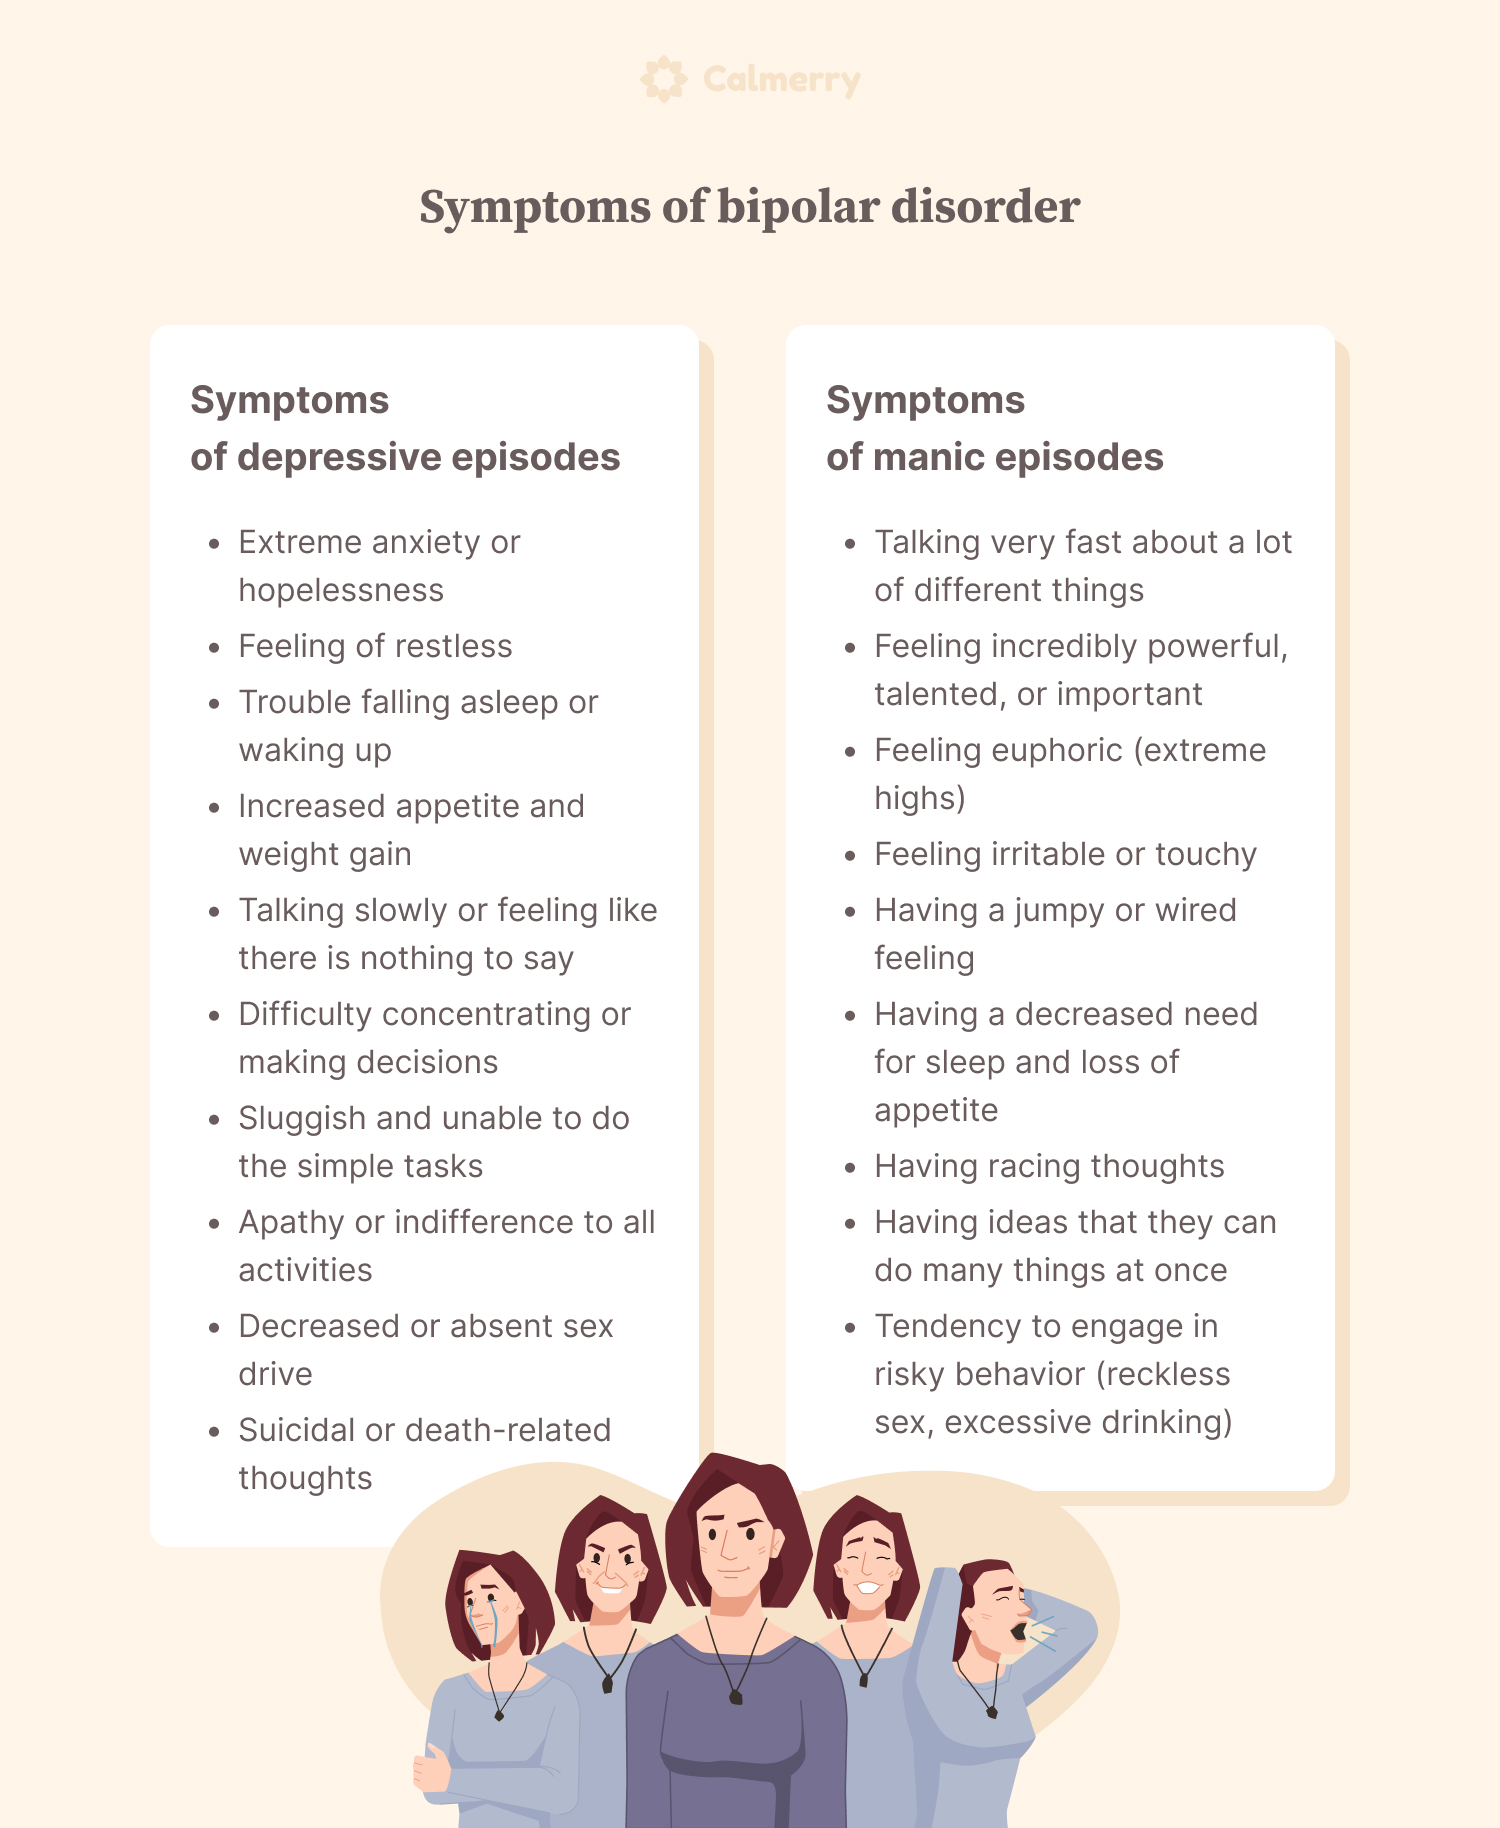
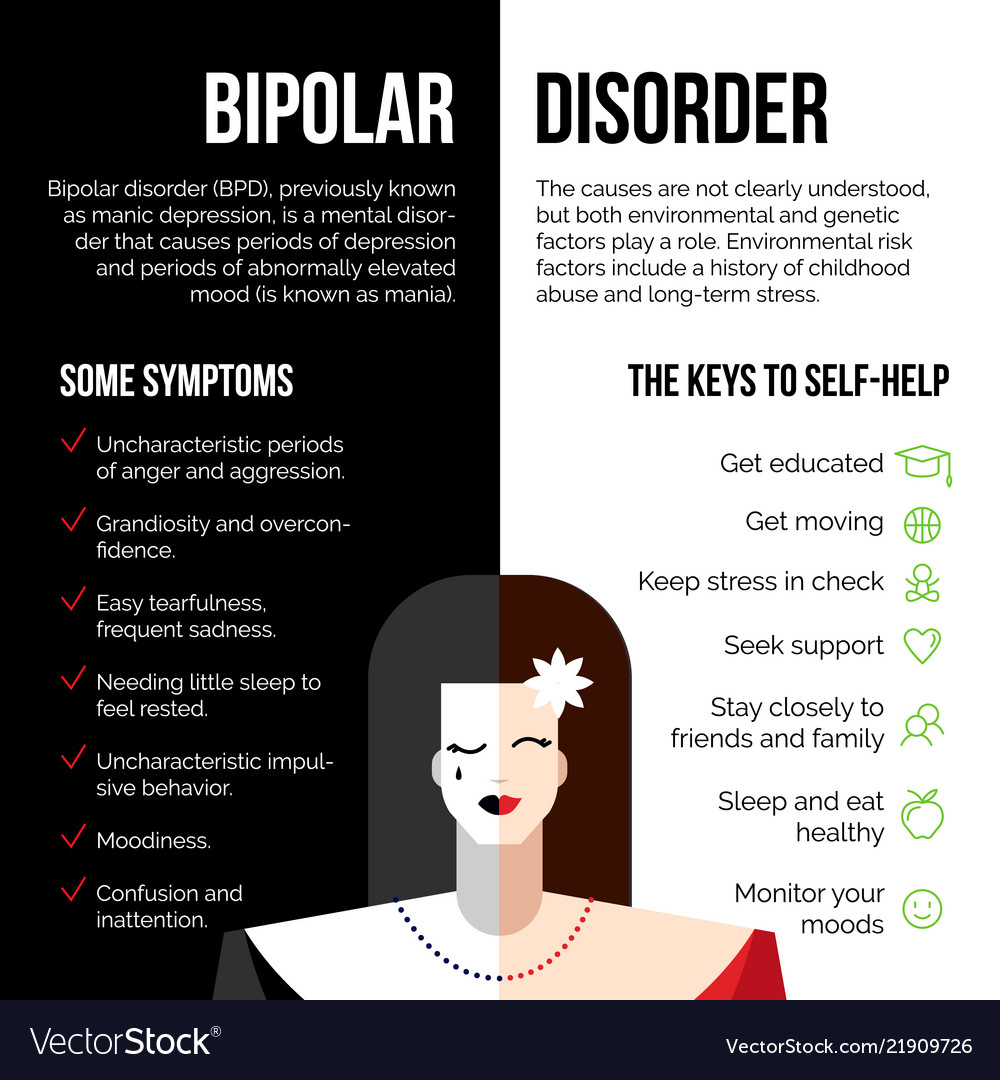
Bipolar disorder is a complex and often misunderstood mental health condition characterized by significant, sometimes extreme, shifts in mood, energy, activity levels, and concentration. These shifts can range from periods of elevated mood, euphoria, or irritability (mania or hypomania) to episodes of intense sadness, hopelessness, or lack of interest (depression). While understanding the clinical definition of these symptoms is crucial for diagnosis and medical management, grasping their financial reverberations is equally vital for comprehensive well-being and stability.
For individuals living with bipolar disorder, the symptoms extend far beyond emotional and behavioral shifts; they often cast a long shadow over their financial lives. From unexpected medical costs and impulsive spending during manic episodes to income instability during depressive phases, the financial implications are profound and multifaceted. This article will not delve into the clinical intricacies of bipolar disorder symptoms from a medical standpoint but will instead focus exclusively on the economic landscape they create, exploring the direct and indirect financial burdens, the impact on earning potential, and strategic approaches to navigating personal finance amidst the condition’s volatility. By examining “what is bipolar disorder symptoms” through a financial lens, we aim to shed light on how individuals and their families can build greater economic resilience and secure a more stable future.
The Financial Echoes of Mood Episodes: Direct and Indirect Costs
The characteristic mood swings of bipolar disorder, spanning from the highs of mania to the lows of depression, carry with them a significant financial footprint. These costs manifest in both direct, explicit expenditures related to treatment and indirect, often hidden, drains on personal finances resulting from symptom-driven behaviors. Understanding both categories is the first step toward effective financial planning and mitigation.
Direct Costs of Symptom Management
Managing bipolar disorder is an ongoing process that frequently involves substantial financial investment in healthcare. These are the most apparent costs, yet their cumulative impact can be overwhelming for many individuals and families.
-
Medication Expenses: Pharmacotherapy is a cornerstone of bipolar disorder treatment, often involving a combination of mood stabilizers, antipsychotics, and antidepressants. These prescriptions can be costly, especially for newer formulations or if multiple medications are required. Even with insurance, co-pays and deductibles can accumulate, presenting a continuous financial burden over years or even decades. The need for consistent adherence means these costs are rarely optional.
-
Therapy and Counseling Fees: Regular psychotherapy, including cognitive-behavioral therapy (CBT), dialectical behavior therapy (DBT), or family-focused therapy, is often recommended alongside medication. Sessions can range from weekly to bi-weekly, with costs varying significantly based on the therapist’s qualifications, location, and insurance coverage. Intensive outpatient programs (IOPs) or partial hospitalization programs (PHPs) for more severe episodes can incur even higher fees.
-
Hospitalization Costs: During severe manic or depressive episodes, inpatient hospitalization may become necessary to ensure safety and stabilize symptoms. Psychiatric hospitalizations are among the most expensive forms of care, with daily rates that can quickly escalate into thousands of dollars. While insurance may cover a portion, significant out-of-pocket expenses, deductibles, and co-insurance can leave individuals facing substantial medical debt.
-
Out-of-Pocket Expenses for Complementary Therapies or Support Groups: Beyond conventional treatments, many individuals explore complementary approaches like specialized dietary plans, exercise programs, mindfulness training, or acupuncture. While these can be beneficial for some, they often come with out-of-pocket costs not covered by insurance. Furthermore, participation in peer support groups or advocacy organizations, while invaluable, might involve membership fees or travel expenses.
Indirect Financial Drain from Behavioral Symptoms
Beyond the direct costs of treatment, the behavioral manifestations of bipolar disorder symptoms can lead to significant indirect financial consequences, often eroding savings, accumulating debt, and causing long-term economic instability.
-
Impulsive Spending During Manic Episodes: A hallmark of mania or hypomania is a decreased need for sleep, increased energy, and impaired judgment, which can manifest as impulsive and reckless financial decisions. This might include excessive shopping, making large and often unwise investments, extravagant gifts, gambling, or taking on significant, unaffordable debt. The aftermath of such spending sprees can leave individuals in deep financial distress, requiring years to recover.
-
Neglect of Financial Responsibilities During Depressive Episodes: Conversely, depressive episodes are characterized by low energy, lack of motivation, cognitive slowing, and profound anhedonia. During these periods, individuals may struggle to perform basic tasks, including managing their finances. This can lead to unpaid bills, missed deadlines, accumulation of late fees, damage to credit scores, and even the loss of essential services like utilities or housing due to sheer inability to address them.
-
Legal Fees Due to Poor Decisions or Conflicts: The disinhibited behavior and impaired judgment that can accompany manic episodes sometimes result in legal troubles, such as altercations, driving offenses, or disputes arising from impulsive financial decisions. The associated legal fees, fines, and potential penalties further exacerbate financial strain.
-
Cost of Lost or Damaged Property: In some extreme cases, manic or mixed episodes can involve destructive behavior, leading to damage to personal property, vehicles, or even housing. The costs associated with repairs or replacement add yet another layer of financial burden, often unforeseen and uninsured.
Impact on Earning Potential and Career Trajectory
The unpredictable nature of bipolar disorder symptoms poses significant challenges to maintaining consistent employment and advancing professionally, directly impacting an individual’s earning potential and long-term financial security. The fluctuating moods and energy levels inherent to the condition can create an unstable work history and hinder career development.
Interrupted Employment and Productivity Losses
The very essence of bipolar disorder – its cyclical and often disruptive mood episodes – can make steady employment an uphill battle. This instability directly translates into lost income and missed opportunities.
-
Difficulty Maintaining Consistent Work: Individuals with bipolar disorder often face challenges in maintaining a stable work routine due to unpredictable mood episodes. Manic phases might lead to excessive energy followed by burnout, while depressive phases can make it impossible to get out of bed, let alone perform job duties. This inconsistency can result in frequent job changes, periods of unemployment, or difficulty securing full-time positions.
-
Increased Absenteeism and Presenteeism: Even when employed, symptoms can lead to higher rates of absenteeism (missed workdays due to illness or treatment) and presenteeism (being physically present at work but unable to perform effectively due to symptoms like poor concentration, fatigue, or irritability). Both reduce productivity, impact performance reviews, and can lead to disciplinary actions or job loss.
-
Job Loss or Demotion as a Consequence of Work Performance: Poor performance, conflicts with colleagues or superiors during irritable episodes, or extended absences can ultimately lead to job termination or demotion. The stigma associated with mental illness can also play a role, making employers less tolerant or supportive even when employees are making efforts to manage their condition.
-
Challenges in Career Advancement: The cumulative effect of inconsistent employment, reduced productivity, and potential stigma often limits opportunities for promotions, salary increases, and career progression. This can result in a significant disparity in lifetime earnings compared to peers without the condition.
Barriers to Skill Development and Entrepreneurship
Beyond direct employment, bipolar disorder symptoms can create substantial barriers to educational attainment, skill acquisition, and the pursuit of entrepreneurial ventures, further curtailing long-term earning potential.
-
Difficulty Pursuing Higher Education or Specialized Training: Academic performance can be severely impacted by mood episodes. Depressive episodes can make studying impossible, while manic episodes might lead to dropping out or making impulsive, ill-advised educational choices. This can impede the acquisition of degrees or specialized certifications crucial for higher-paying jobs.
-
Hesitation or Inability to Take on Entrepreneurial Risks: Starting a business requires sustained focus, significant capital investment, and the ability to navigate high levels of stress and uncertainty. The unpredictable nature of bipolar disorder symptoms, particularly the risk of poor judgment during mania or profound lack of motivation during depression, can make entrepreneurial ventures seem too risky or simply unmanageable, thus limiting opportunities for self-employment and wealth creation.
-
Stigma in the Workplace Affecting Opportunities: Despite growing awareness, mental health stigma persists. Individuals who disclose their condition, or whose symptoms become apparent, may face discrimination in hiring, promotions, or project assignments, limiting their access to lucrative opportunities or leadership roles within organizations.
Navigating Financial Planning Amidst Symptom Volatility
Effective financial planning is challenging for anyone, but it takes on an added layer of complexity when dealing with the unpredictable nature of bipolar disorder symptoms. Strategic approaches are essential to budget for uncertainty, manage debt, and secure long-term financial stability.
Budgeting for Uncertainty
Traditional budgeting often assumes a relatively stable income and predictable expenses. For individuals with bipolar disorder, this assumption rarely holds true, necessitating a more flexible and robust approach to managing money.
-
Importance of Flexible Budgeting: A rigid budget can quickly become unworkable during periods of fluctuating income or unexpected expenses. Instead, a flexible budget that accounts for potential variations in monthly income and allows for higher medical costs or periods of reduced working hours is crucial. This might involve creating a “tiered” budget that can scale up or down depending on the individual’s current financial and mental health status.
-
Allocating Funds for Unexpected Medical Costs or Periods of Reduced Income: Building specific financial “buffers” is paramount. This includes setting aside funds specifically for emergency medical expenses (e.g., higher medication costs, therapy sessions, or unexpected hospitalizations) and for periods when income might be reduced due to an episode or inability to work.
-
Building an Emergency Fund That Accounts for Mental Health Needs: A standard emergency fund is typically recommended to cover 3-6 months of living expenses. For someone with bipolar disorder, this fund might need to be larger, potentially covering 6-12 months, to provide a stronger safety net against prolonged periods of unemployment, significant medical costs, or the financial fallout from impulsive decisions.
Debt Management and Credit Health
The financial behaviors associated with bipolar disorder symptoms can easily lead to accumulating debt and damaging credit scores, making debt management a critical component of financial stability.
-
Strategies for Addressing Debt Incurred During Episodes: If debt has been accrued through impulsive spending during manic episodes or neglect during depressive episodes, a systematic approach to debt repayment is essential. This could involve debt consolidation, balance transfer cards (used cautiously), or negotiating with creditors for lower interest rates or payment plans. Professional guidance is often beneficial here.
-
Protecting Credit Scores from the Impact of Missed Payments: Missed payments due to depressive episodes can severely impact credit scores, making it harder to secure loans, rent housing, or even obtain certain jobs in the future. Implementing automated payment systems, setting up alerts, and having a trusted individual oversee finances during vulnerable periods can help mitigate this risk.
-
Seeking Professional Financial Counseling: For complex debt situations, working with a non-profit credit counseling agency or a financial therapist specializing in mental health can provide objective advice, help create a realistic repayment plan, and negotiate with creditors on the individual’s behalf.
Long-term Financial Security Considerations
Beyond immediate expenses and debt, bipolar disorder symptoms necessitate careful consideration of long-term financial security, including retirement planning and protection against future income loss.
-
Retirement Planning in the Face of Intermittent Employment: Inconsistent employment means fewer opportunities to contribute to retirement accounts. Strategies might include maximizing contributions during stable periods, exploring self-directed retirement accounts (like Solo 401(k)s if self-employed), or seeking professional advice to optimize what can be saved.
-
Disability Insurance and Income Protection: Disability insurance (both short-term and long-term) can be a crucial safety net for individuals whose symptoms might lead to periods of inability to work. Researching policies that cover mental health conditions specifically and understanding waiting periods and benefit structures is vital.
-
Estate Planning to Ensure Stability for Dependents: For individuals with dependents, careful estate planning, including wills, trusts, and designation of financial powers of attorney, becomes even more critical. This ensures that assets are managed appropriately and dependents are cared for, especially during times when the individual might be unable to make sound financial decisions.
Leveraging Financial Tools and Strategies for Stability
In an era of digital convenience, a wealth of financial tools and strategies can be harnessed to counteract the financial volatility often associated with bipolar disorder symptoms. Automation, professional guidance, and protective measures are key to establishing robust financial safeguards.
Automated Systems for Financial Control
Technology can be a powerful ally in managing finances, particularly for individuals who might experience periods of impaired decision-making or reduced motivation. Automation can provide a crucial layer of protection.
-
Setting Up Automatic Bill Payments to Avoid Late Fees: One of the simplest yet most effective strategies is to automate bill payments for all recurring expenses (rent/mortgage, utilities, loan payments, credit cards). This prevents missed payments due to forgetfulness or an inability to manage tasks during depressive episodes, safeguarding credit scores and avoiding unnecessary fees.
-
Automating Savings Contributions: Even small, regular contributions to savings accounts can accumulate over time. Setting up automatic transfers from checking to savings (including emergency funds and investment accounts) ensures that wealth building continues even when conscious financial management might be challenging.
-
Using Budgeting Apps with Alert Features: Many personal finance apps (e.g., Mint, YNAB, Personal Capital) can link to bank accounts and provide real-time insights into spending. Their alert features can notify users of unusual spending patterns, impending bill due dates, or when account balances fall below a certain threshold, serving as an early warning system during potentially vulnerable periods.
Professional Financial Guidance
Navigating the financial landscape with bipolar disorder symptoms often benefits from expert advice tailored to specific challenges. Financial professionals can provide objective strategies and support.
-
Working with a Financial Advisor Who Understands Chronic Health Challenges: Not all financial advisors are equipped to understand the nuances of managing finances with a chronic mental health condition. Seeking an advisor who has experience with or is sensitive to these challenges can lead to more realistic and sustainable financial plans. They can help integrate healthcare costs, income volatility, and long-term planning into a cohesive strategy.
-
Engaging with Mental Health-Informed Financial Planners: A growing specialization, financial therapists or planners who integrate mental health principles can offer a holistic approach. They can help individuals address the emotional and psychological aspects of money management, providing strategies for impulse control during mania and motivation during depression, alongside traditional financial planning.
-
Seeking Legal Counsel for Financial Protections: In severe cases, or for long-term planning, legal advice might be necessary. This could involve setting up a trust, establishing a durable power of attorney for finances, or creating a health care proxy. These legal mechanisms can provide a safety net, ensuring financial decisions are made responsibly even when an individual is unable to do so themselves.
Protective Measures During Episodes
Proactive measures to safeguard finances during acute episodes can prevent significant losses and maintain stability. These strategies involve setting boundaries and enlisting support before a crisis hits.
-
Designating a Trusted Individual for Financial Oversight During Severe Episodes: A crucial protective measure is to legally designate a trusted family member or friend (via a durable power of attorney) to assist with or take over financial management during severe manic or depressive episodes. This person can monitor accounts, pay bills, and prevent impulsive spending, acting as a safeguard when judgment is impaired.
-
Setting Up “Cooling-Off” Periods or Limits on Online Spending: Technology can also be used to create barriers against impulsive spending. Some banks or apps allow users to set daily spending limits, block certain types of transactions, or implement “cooling-off” periods before large purchases are finalized. Physically removing credit cards from easy access during vulnerable times can also be effective.
-
Creating a “Financial Crisis Plan”: Similar to a mental health crisis plan, a financial crisis plan outlines steps to take during an acute episode. This document can list important account numbers, contact information for trusted individuals, payment schedules, and instructions for managing finances. It serves as a guide for the individual or their designated support person when clarity of thought is compromised.
Building a Resilient Financial Support System
No individual should face the financial challenges of bipolar disorder alone. Building a robust support system, encompassing family, community, and professional resources, is paramount for achieving and maintaining financial resilience. This network provides not only practical assistance but also emotional encouragement and advocacy.
Family and Social Support Networks
Loved ones can play a pivotal role in financial management, offering both practical help and crucial emotional support. Open communication and clear roles are key.
-
Open Communication with Family About Financial Challenges: Hiding financial struggles or patterns of impulsive spending from family can exacerbate problems. Openly discussing the financial implications of bipolar disorder symptoms with trusted family members can lead to shared understanding, collaborative problem-solving, and a more unified approach to financial management.
-
Seeking Support from Trusted Friends or Community Groups: Beyond immediate family, friends or support groups focused on mental health can offer valuable insights, emotional encouragement, and practical advice. Hearing how others manage their finances while living with bipolar disorder can provide new strategies and a sense of shared experience.
-
The Role of a Financial Accountability Partner: For some, having a trusted friend or family member act as a financial accountability partner can be beneficial. This person might not manage money directly but could check in regularly, review spending, or serve as a sounding board before major financial decisions, particularly during periods of increased vulnerability.
Community and Government Resources
A range of external resources exists to provide financial assistance, guidance, and advocacy for individuals living with mental health conditions. Tapping into these can significantly alleviate financial burdens.
-
Exploring Disability Benefits and Government Assistance Programs: Depending on the severity and impact of bipolar disorder symptoms on an individual’s ability to work, various government disability benefits (e.g., Social Security Disability Insurance, Supplemental Security Income) may be available. Understanding eligibility criteria and navigating the application process can provide a crucial income safety net. Other state or local assistance programs might also offer aid for housing, food, or utilities.
-
Accessing Non-Profit Organizations Offering Financial Aid or Counseling for Those with Mental Health Conditions: Many non-profit organizations specialize in supporting individuals with mental illness, often providing financial literacy workshops, free or low-cost financial counseling, or even direct financial assistance for specific needs like medication costs or emergency housing. These organizations can be invaluable navigators of complex systems.
-
Patient Assistance Programs for Medication Costs: Pharmaceutical companies often offer patient assistance programs (PAPs) to help individuals who cannot afford their prescription medications. Investigating these programs can significantly reduce the ongoing direct costs of treatment, which is a major financial burden for many.
Advocating for Financial Wellness
Beyond individual strategies, advocating for broader systemic changes and fostering greater understanding can create a more supportive environment for financial wellness for those with bipolar disorder.
-
Reducing Stigma Around Financial Struggles Related to Mental Health: Just as mental health stigma impacts career opportunities, it also affects discussions about money. Openly acknowledging that mental health conditions can lead to financial challenges helps normalize these struggles, encouraging more people to seek help without shame and fostering greater empathy.
-
Promoting Workplace Policies That Support Employees with Chronic Conditions: Advocating for more inclusive workplace policies, such as flexible work arrangements, mental health days, and robust employee assistance programs (EAPs) with financial counseling components, can significantly improve the financial stability of individuals managing bipolar disorder.
-
Emphasizing Holistic Well-being That Includes Financial Health: True well-being is not just about physical or mental health; it encompasses financial stability. Integrating financial literacy and planning into mental health recovery plans, and encouraging healthcare providers to consider the financial impact of their recommendations, ensures a more comprehensive and sustainable approach to managing life with bipolar disorder.
Conclusion
Understanding “what is bipolar disorder symptoms” is a journey that extends far beyond clinical definitions and into the everyday realities of life, profoundly impacting an individual’s financial stability. From the direct costs of ongoing treatment and the indirect expenses incurred during mood episodes to the challenges in maintaining consistent employment and securing long-term financial health, the economic reverberations are undeniable.
However, recognizing these challenges is the first step toward empowerment. By adopting proactive financial planning strategies, leveraging available technological and professional tools, and consciously building a strong support system, individuals living with bipolar disorder can navigate these complex financial waters with greater confidence and resilience. Automation, flexible budgeting, seeking expert advice, and establishing protective measures can mitigate risks, while tapping into family, community, and government resources provides essential layers of assistance.
Ultimately, achieving financial wellness is not merely about accumulating wealth; it’s about securing peace of mind, reducing stress, and fostering an environment that supports overall mental health. By addressing the financial dimensions of bipolar disorder symptoms head-on, individuals can take meaningful steps towards a life of greater stability, independence, and well-being, proving that even amidst unpredictability, financial resilience is an attainable and crucial goal.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.