
The arrival of a newborn brings immense joy, profound love, and an overwhelming sense of responsibility. Amidst the wonder, parents quickly learn to navigate countless new challenges, from sleepless nights to feeding schedules. One common concern that can cause significant distress is a newborn experiencing congestion. While the immediate focus is always on the baby’s comfort and health, what often goes unaddressed until the moment of need are the financial implications. Dealing with a congested newborn isn’t just emotionally taxing; it can also lead to unexpected expenses that can strain a family’s budget. This article delves into the financial considerations surrounding newborn congestion, offering insights and strategies for parents to prepare for and manage these unforeseen costs, ensuring peace of mind during an already challenging time.
Understanding the Direct Costs of Infant Congestion
When a newborn is congested, parents instinctively seek solutions to alleviate discomfort and ensure their baby’s well-being. This often involves a series of steps, each with a potential financial cost, sometimes small individually, but accumulative. Being aware of these potential expenditures is the first step in financial preparedness.
Doctor’s Visits and Medical Consultations
The primary concern for any new parent faced with a congested newborn is often when to seek professional medical advice. A visit to the pediatrician is a common and often necessary step, especially for infants under three months of age where congestion can quickly escalate. Each doctor’s visit typically incurs a co-pay, deductible, or an out-of-pocket expense depending on your health insurance plan. If the situation requires specialist consultation, such as an ENT (Ear, Nose, and Throat) specialist, these costs can further increase. Furthermore, after-hours clinics or emergency room visits – sometimes necessary if congestion seems severe or is accompanied by other alarming symptoms – carry significantly higher charges, making a single episode of congestion potentially costly without adequate insurance coverage. Understanding your health insurance policy’s specifics, including in-network providers, deductibles, co-pays, and out-of-pocket maximums, is crucial before these situations arise.
Medications and Over-the-Counter Remedies
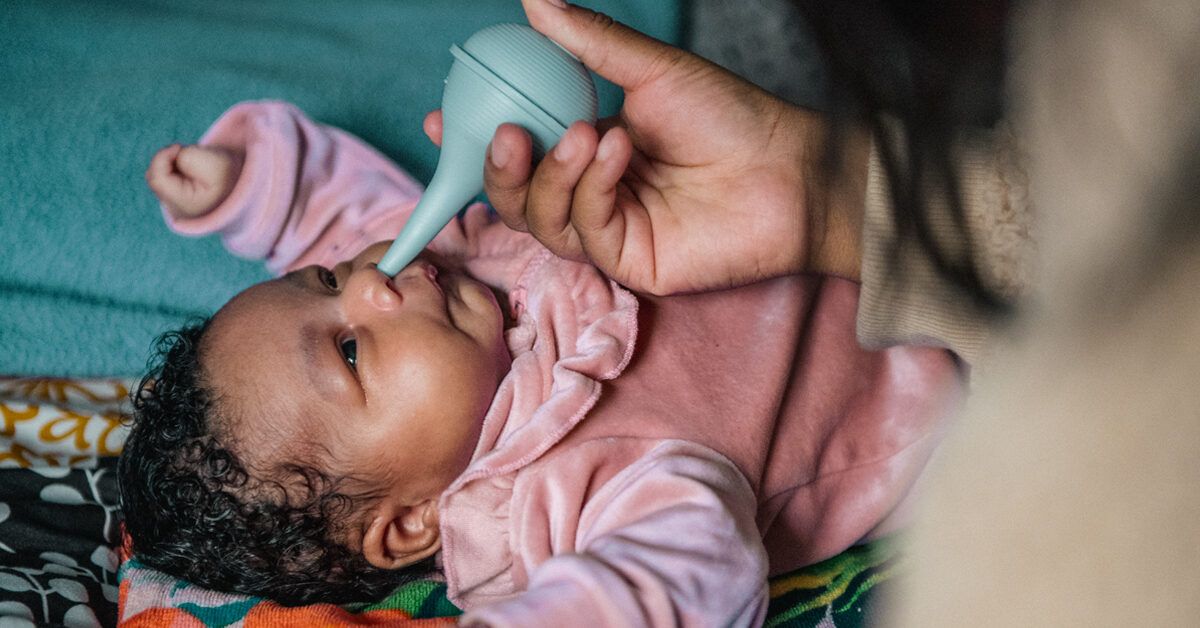
While doctors generally advise against cough and cold medications for infants, they might recommend specific saline nasal drops, nasal aspirators, or humidifiers. Saline drops, though relatively inexpensive, become a recurring cost if used frequently. Nasal aspirators, whether manual bulb syringes or more advanced electric versions, represent an initial purchase. Beyond these, a pediatrician might prescribe other medications depending on the underlying cause of congestion (e.g., antibiotics for a bacterial infection, which are rare but possible). Even if the baby doesn’t require prescription medication, parents might purchase vapor rub (specifically formulated for infants), specialized wipes, or extra supplies for comfort, all adding to the overall expenditure. These are often small, incremental costs that can add up quickly over time, especially if congestion persists or recurs.
Specialized Equipment and Home Care Items
Beyond direct medical care and basic remedies, managing newborn congestion at home often necessitates specific equipment. A humidifier is a frequently recommended item to moisten the air and help loosen mucus. Quality humidifiers can range from $30 to over $100, plus the ongoing cost of distilled water or replacement filters. Baby monitors with humidity sensors or air purifiers might also be considered by anxious parents, representing further investment. Specialized bedding, extra laundry detergent for frequent sheet changes due to spit-up or mucus, and even specific types of thermometers can all become part of the financial outlay. While these items aim to provide comfort and aid recovery, they are tangible costs that should be factored into a family’s financial planning, particularly if they are not already part of initial baby preparations.
Indirect Financial Burdens and Opportunity Costs
The financial impact of a congested newborn extends beyond direct medical and supply costs. Often overlooked are the indirect financial burdens and opportunity costs that can significantly affect a family’s economic stability. These costs relate to changes in parental work, childcare, and even mental well-being, all of which have a monetary value.
Parental Time Off Work and Lost Income
When a newborn is unwell, parents frequently need to take time off work to care for them, attend doctor’s appointments, or simply be present to monitor their condition. For hourly wage earners, this directly translates to lost income. Salaried employees might use sick days or vacation time, depleting their available leave, which could have financial implications for future needs. In some cases, prolonged or severe congestion might require one parent to take an extended leave, potentially impacting career progression or leading to a temporary reduction in household income. For self-employed individuals, time off means lost billable hours, directly affecting their business’s profitability. Understanding employer policies regarding sick leave and family leave (like FMLA in the US) is crucial for mitigating this financial impact, but the opportunity cost of missed work or delayed career milestones remains a real consideration.
Childcare Adjustments and Related Expenses
If a newborn is typically in daycare or cared for by a nanny, congestion might necessitate adjustments. Many daycare centers have policies against accepting sick children, forcing parents to find alternative care or keep the baby home. This can lead to additional childcare expenses if a temporary caregiver is hired, or, as discussed, lost income if a parent stays home. Even if the baby is primarily cared for at home, a congested infant often requires more intensive, hands-on care, which can distract parents from other income-generating activities or household tasks, indirectly costing time and money. The logistics of managing care for a sick infant can create unexpected financial strain on an already stretched budget.
Emotional and Mental Health Costs
While not immediately tangible in dollars and cents, the emotional and mental toll of a sick newborn can indirectly lead to financial consequences. The stress, anxiety, and sleep deprivation experienced by parents can impact their productivity at work, potentially affecting performance bonuses or opportunities for advancement. In more severe cases, persistent stress might lead to mental health challenges requiring professional support, such as therapy or counseling, which themselves incur costs even with insurance. Furthermore, some parents might resort to “stress spending” on convenience foods, comfort items, or online shopping as a coping mechanism, unknowingly adding to their financial burden. Recognizing these subtle financial leakages is important for holistic financial management during times of stress.
Strategies for Financial Preparedness
Proactive financial planning is the cornerstone of managing unexpected health challenges like newborn congestion. By implementing a few key strategies, parents can build a financial safety net that provides both practical resources and peace of mind.
Health Insurance Review and Optimization
A robust health insurance plan is your first line of defense against unexpected medical costs. Before or shortly after your baby’s birth, thoroughly review your policy. Understand your deductible, co-pays, coinsurance, and annual out-of-pocket maximum. Confirm that your chosen pediatrician is in-network. If you have options through your employer, compare plans to see which offers the best coverage for pediatric care, even if it has a slightly higher premium. Sometimes, a plan with a higher premium but lower deductible and co-pays can save you money in the long run, especially with a new baby who might require more frequent doctor visits. Don’t hesitate to call your insurance provider directly to clarify any ambiguities and ensure you understand your benefits for infant care, including emergency services.
Building an Emergency Fund for Medical Contingencies
An emergency fund is vital for any household, but it becomes even more critical with a new dependent. This fund should ideally cover 3-6 months of essential living expenses, but a dedicated portion for medical contingencies is a wise addition. Start small if you need to, setting aside a fixed amount each month specifically for unexpected health-related costs not fully covered by insurance. This fund can buffer against co-pays, deductibles, out-of-pocket maximums, and even lost income from taking time off work. Accessing readily available cash in a high-yield savings account ensures you can address immediate needs without resorting to high-interest credit cards or disrupting other financial goals.
Flexible Spending Accounts (FSAs) and Health Savings Accounts (HSAs)
Leveraging tax-advantaged accounts like Flexible Spending Accounts (FSAs) and Health Savings Accounts (HSAs) can significantly reduce the financial burden of medical expenses. FSAs allow you to set aside pre-tax money from your paycheck for eligible healthcare expenses, including doctor visits, prescriptions, and certain over-the-counter items. HSA plans, typically coupled with high-deductible health plans (HDHPs), offer a triple tax advantage: tax-deductible contributions, tax-free growth, and tax-free withdrawals for qualified medical expenses. Both types of accounts can be incredibly beneficial for managing routine and unexpected infant health costs, effectively making your healthcare dollars go further. It’s important to understand the specific rules for each (e.g., FSA “use it or lose it” rules vs. HSA funds rolling over) to maximize their benefits.
Navigating Costs and Maximizing Resources During an Episode
Even with diligent preparation, the actual experience of dealing with a congested newborn requires smart financial decision-making on the fly. Knowing how to navigate costs and utilize available resources can prevent unnecessary expenditure and alleviate financial stress.
Comparing Costs for Prescriptions and Supplies
Once a pediatrician prescribes medication or recommends specific supplies, take a moment to compare prices. Pharmacy costs for the same prescription can vary significantly. Websites and apps can help you find the cheapest option in your area or provide coupons. Similarly, for over-the-counter remedies like saline drops or nasal aspirators, compare prices across different retailers, including online pharmacies and big-box stores. Buying generic versions of non-prescription items can also offer substantial savings without compromising effectiveness. If a specific piece of equipment like a humidifier is recommended, research models that offer good value for money and read reviews to avoid unnecessary upgrades or features you won’t use.
Utilizing Telehealth and Nurse Hotlines
Many health insurance plans now offer telehealth services, allowing you to consult with a doctor remotely via phone or video. For non-emergency situations like mild to moderate congestion, telehealth can be a more convenient and often more affordable alternative to an in-person doctor’s visit, saving on co-pays and travel time. Additionally, many insurance providers and pediatric practices offer nurse hotlines. These services can provide immediate advice and help you determine if an in-person visit is truly necessary, potentially saving you the cost of an unnecessary consultation. Leveraging these modern resources can be a smart financial move while still ensuring your baby receives appropriate care.
Exploring Community and Employer Support Programs
Beyond personal savings and insurance, families can often find support through various community and employer programs. Some employers offer childcare subsidies, flexible work arrangements, or employee assistance programs (EAPs) that can provide resources for financial counseling or mental health support during stressful times. Community health clinics often provide services at reduced rates or on a sliding scale for families with lower incomes. Non-profit organizations focused on infant health or family support might also offer resources or financial aid for specific medical needs. Researching these options proactively can uncover valuable support networks and financial relief that you might not otherwise know exist.
Conclusion
The experience of a newborn suffering from congestion is undoubtedly stressful for parents. While the immediate priority is always the baby’s health and comfort, the financial implications, both direct and indirect, can add a significant layer of anxiety. By understanding the potential costs involved, proactively preparing with robust health insurance, building an emergency fund, and utilizing tax-advantaged accounts, parents can create a strong financial foundation. Furthermore, being resourceful in navigating costs during an actual episode – by comparing prices, leveraging telehealth, and exploring support programs – empowers families to manage expenses effectively. Financial preparedness isn’t just about saving money; it’s about safeguarding your family’s well-being and ensuring you can provide the best possible care for your newborn without compounding emotional stress with unnecessary financial strain.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.