
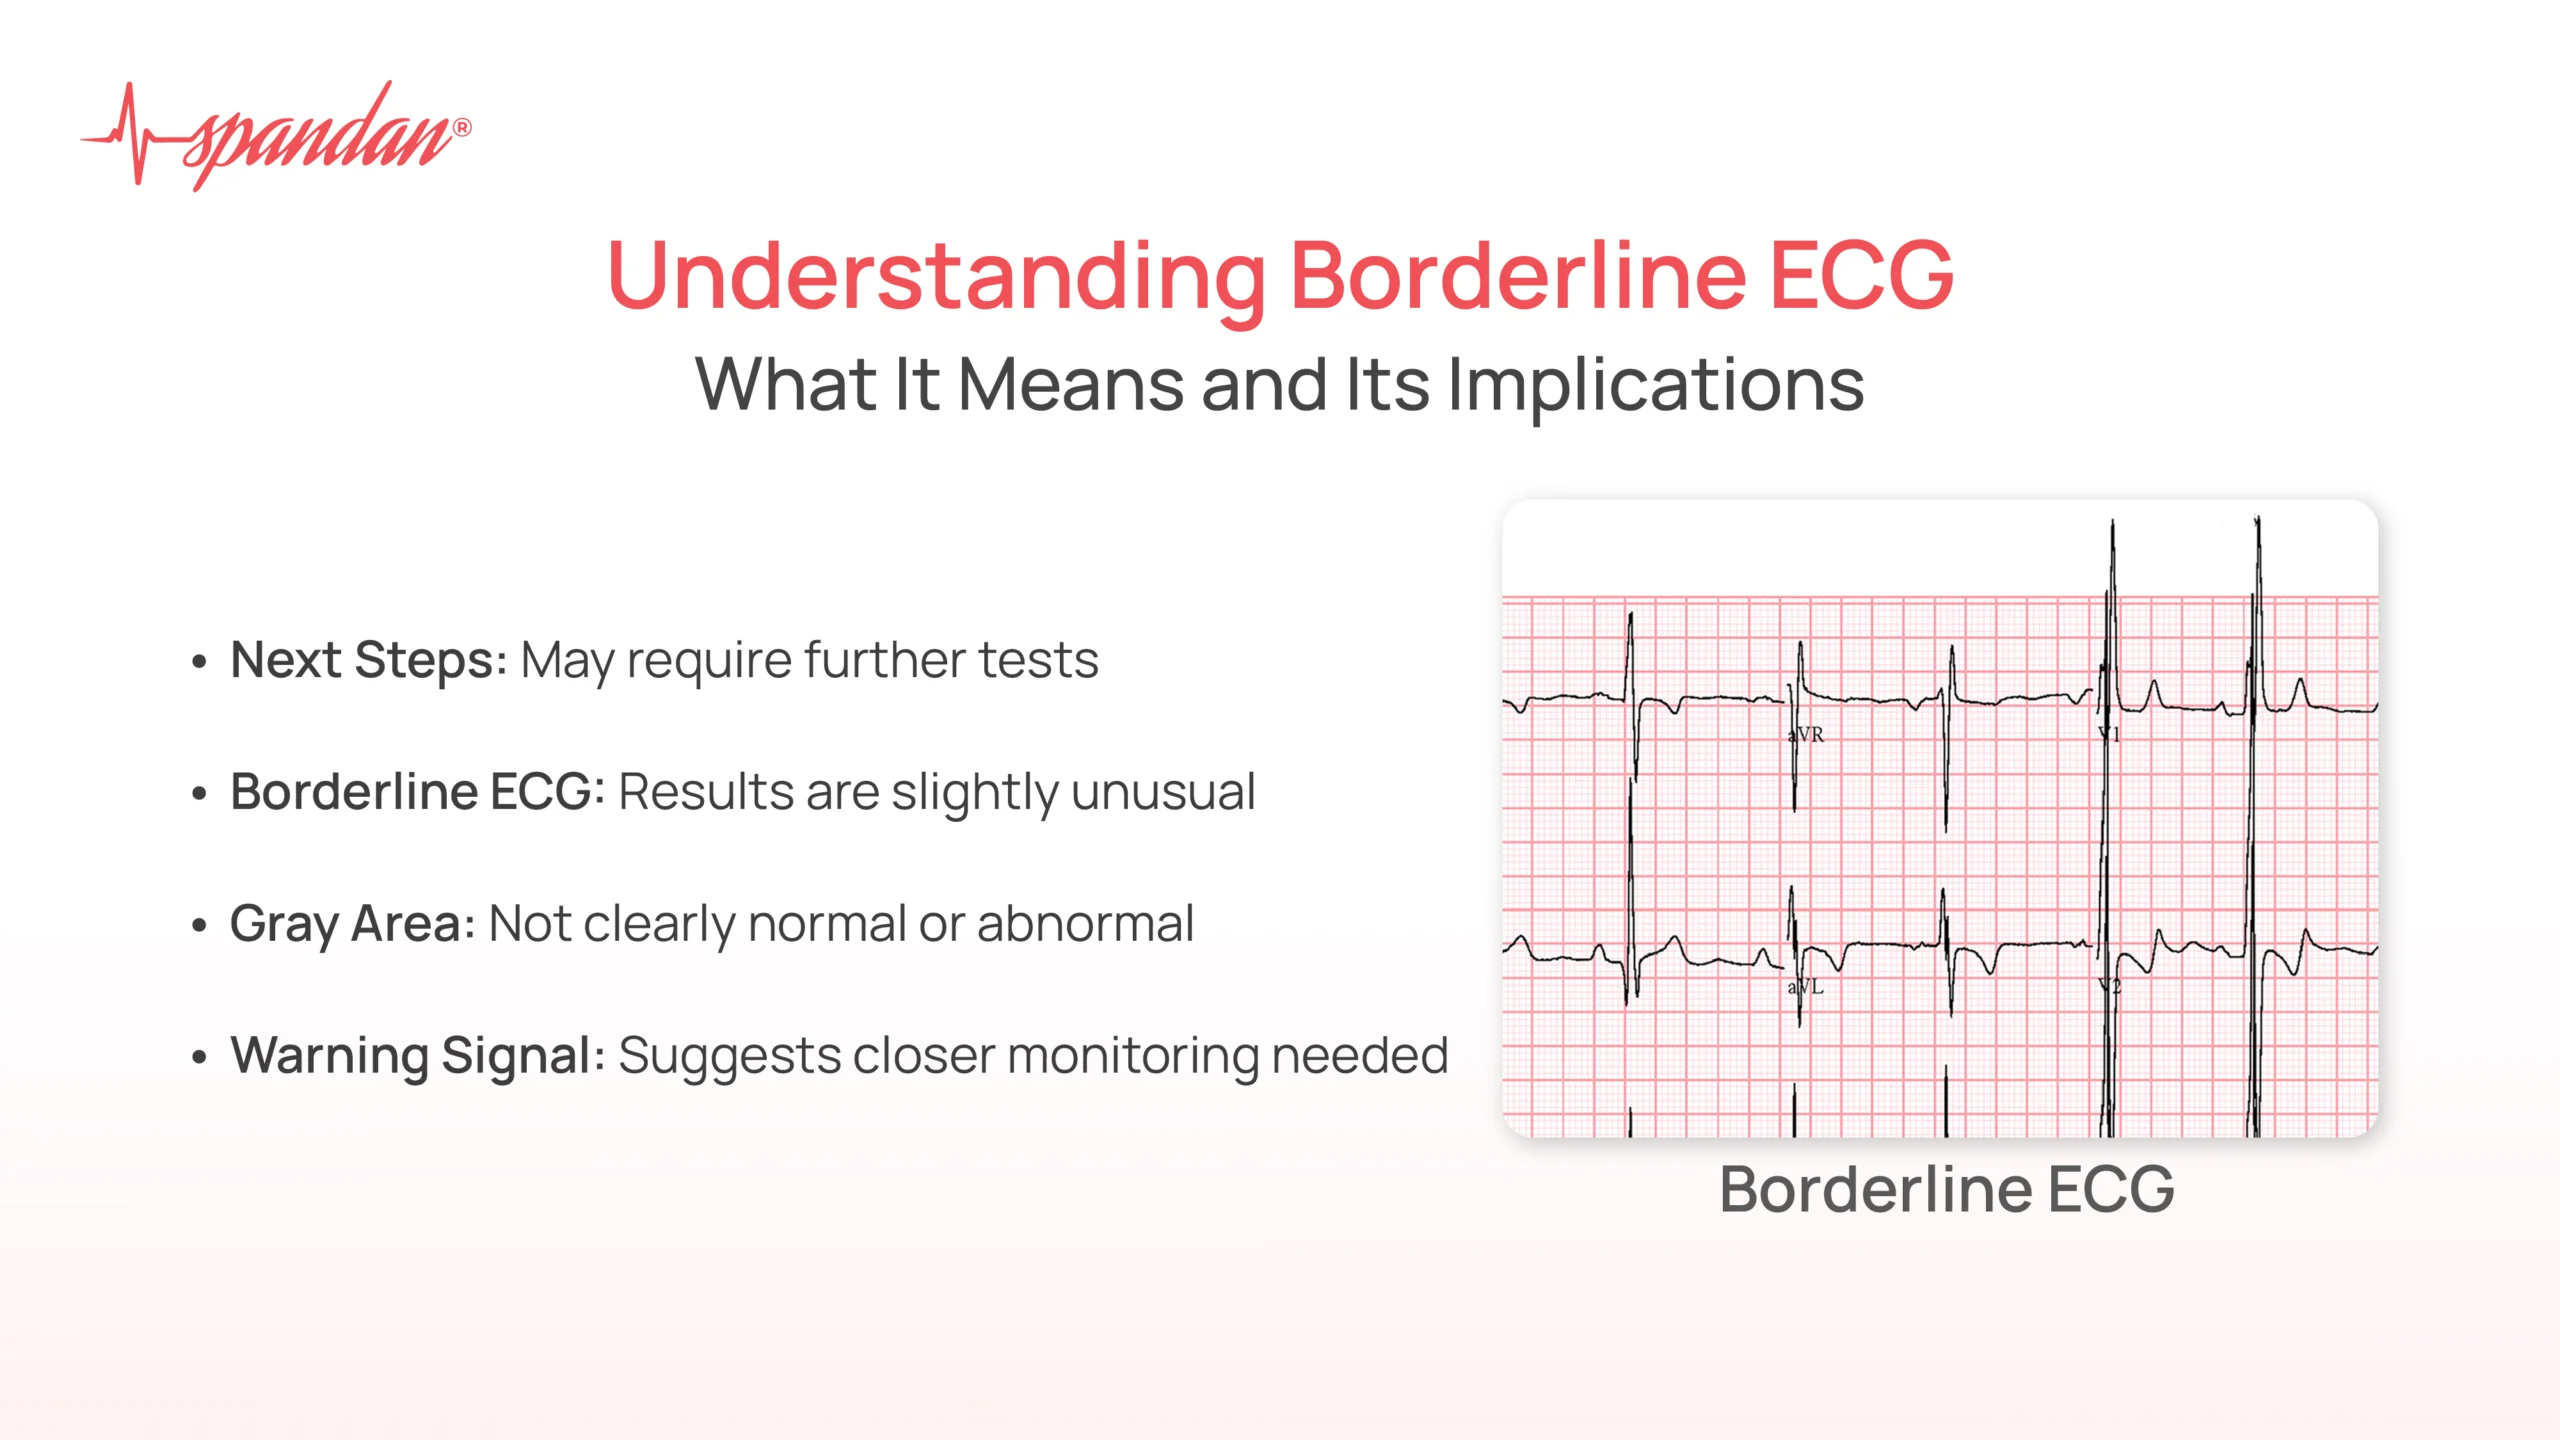
In the realm of personal finance, investing, and business strategy, the term “borderline ECG” might seem out of place. Typically, an Electrocardiogram (ECG) is a diagnostic tool used in medicine to monitor the heart’s electrical activity, identifying any irregularities. A “borderline” ECG in a medical context signals that while not overtly pathological, there are indicators that warrant closer attention, further investigation, or a change in lifestyle. It’s a yellow flag, not a red one, but certainly not a green one either.
However, the essence of a “borderline ECG” – an ambiguous signal demanding careful interpretation and potential action – is profoundly relevant to our financial health and economic well-being. In finance, we often encounter “borderline” indicators: metrics that aren’t disastrous but aren’t robust, either. They suggest underlying vulnerabilities, inefficiencies, or emerging risks that, if ignored, could lead to more severe complications down the line. This article will explore the metaphorical “borderline ECG” in the context of money, uncovering what these ambiguous signals mean for your personal finances, investments, and business health, and how to respond effectively.
The Metaphorical Pulse: Reinterpreting “ECG” in Finance
Just as an ECG measures the heart’s vital electrical signals, a financial “ECG” involves monitoring the key metrics that indicate the health and stability of your economic system, whether personal or corporate. Understanding this metaphorical application is the first step towards proactive financial management.
From Heart Health to Financial Health
Think of your financial life as a living organism. It has a pulse (cash flow), a circulatory system (assets and liabilities), and vital organs (income streams, investments). Just as a cardiologist reads an ECG to assess cardiac function, a financially astute individual or business leader interprets various financial indicators to gauge economic vitality.
A “financial ECG” comprises a snapshot of your most critical financial data points. For individuals, this might include your debt-to-income ratio, credit score, savings rate, emergency fund adequacy, and investment portfolio performance. For businesses, it could involve cash flow statements, profit margins, liquidity ratios, customer acquisition costs, and return on equity. These metrics, when viewed holistically, provide a comprehensive picture of financial health, much like an ECG provides insight into cardiac function.
The power of this metaphor lies in its emphasis on signals. Financial markets, personal spending habits, and business operations constantly generate data. Our challenge is to filter this noise and identify the critical signals that tell us something meaningful about our underlying health. A “borderline” reading suggests that while the system isn’t in immediate crisis, it’s not operating at optimal health either, and requires vigilance.
Identifying Your Financial “ECG” Metrics
To truly perform a financial “ECG,” you need to know which metrics to monitor. These are your vital signs:
-
For Personal Finance:
-
Debt-to-Income Ratio (DTI): The percentage of your gross monthly income that goes towards debt payments. A high DTI can indicate overextension.
-
Savings Rate: The percentage of your income you save. A low rate suggests insufficient preparation for future goals or emergencies.
-
Emergency Fund Balance: How many months of essential living expenses you have saved. Too little is a major vulnerability.
-
Credit Score: A numerical representation of your creditworthiness. A “borderline” score limits access to favorable lending terms.
-
Net Worth: The total value of your assets minus your liabilities. Stagnant or declining net worth (outside of intentional spending) can be a concern.
-
Investment Portfolio Performance: How your investments are performing relative to your goals and benchmarks.
-
-
For Business Finance:
-
Cash Flow from Operations: The cash generated by normal business activities. Negative or declining operational cash flow is a red flag.
-
Profit Margins (Gross, Operating, Net): The percentage of revenue left after various costs. Declining margins indicate efficiency issues or pricing pressure.
-
Current Ratio / Quick Ratio: Measures of liquidity – ability to meet short-term obligations. A ratio that’s too low or too high can be problematic.
-
Debt-to-Equity Ratio: Indicates how much debt a company is using to finance its assets relative to shareholder equity. A high ratio signals risk.
-
Customer Lifetime Value (CLV) vs. Customer Acquisition Cost (CAC): A “borderline” ratio here means you’re spending almost as much to get a customer as they bring in over their lifetime.
-
Inventory Turnover: How quickly inventory is sold. Slow turnover ties up capital.
-
These are just a few examples. The key is to select metrics that are most relevant to your specific financial context and to track them consistently.
Understanding the “Borderline” Financial Signal
What exactly constitutes a “borderline” reading in your financial ECG? It’s that uneasy feeling when numbers aren’t terrible, but they’re not great either. It’s the grey area between clear success and outright failure, a signal that demands discernment.
What Constitutes a Borderline Status?
A “borderline” financial status isn’t a crisis, but it’s far from optimal. It’s a situation where:
-
For Individuals:
-
Your debt-to-income ratio is creeping up towards a high threshold (e.g., above 36-43% depending on the lender).
-
Your emergency fund covers 3 months of expenses, but you’re aiming for 6-12 months, leaving a gap.
-
Your savings rate is positive but insufficient to meet long-term goals like retirement or a down payment.
-
Your credit score is “fair” or “good” but not “excellent,” meaning you qualify for loans but at less favorable rates.
-
Your investment portfolio is trailing its benchmark slightly, or your diversification is adequate but not robust.
-
-
For Businesses:
-
Your profit margins are slightly below industry averages, suggesting competitive pressures or inefficiencies.
-
Your cash flow from operations is positive but insufficient to fund growth initiatives without external financing.
-
Your current ratio is just above the minimum acceptable threshold, indicating limited liquidity.
-
Customer churn rates are stable but not declining, or customer acquisition costs are rising slightly.
-
Your debt load is manageable but leaves little room for unexpected downturns or investments.
-
In essence, a borderline status means you’re operating with limited buffer, reduced flexibility, or unaddressed inefficiencies. You’re not “bleeding money,” but you’re not thriving either.
Early Warnings vs. Imminent Crises
The crucial distinction of a “borderline” reading is that it represents an early warning signal, not an imminent crisis. A crisis (a heart attack, bankruptcy, foreclosure) typically involves immediate, severe, and undeniable symptoms. A borderline condition, however, is subtler. It’s the pre-diabetic stage before full-blown diabetes, the consistently high blood pressure before a stroke.
The danger of a borderline signal is its deceptiveness. Because things aren’t catastrophically bad, there’s a temptation to dismiss it, to assume “it’ll be fine.” This complacency is often the precursor to a more serious problem. A true crisis often emerges from a prolonged period of unaddressed borderline conditions. Recognizing these subtle shifts allows for intervention when solutions are often simpler, less costly, and more effective.
The Risks of Ignoring a Borderline Financial Reading
Just as ignoring a borderline medical ECG can escalate into serious health issues, overlooking borderline financial signals carries significant risks that can erode your wealth and opportunities.
Missed Opportunities and Eroding Wealth
A healthy financial system is agile and opportunistic. When your finances are in a borderline state, your ability to seize opportunities is compromised. For an individual, this might mean missing out on a strong investment because you lack the capital, or being unable to take advantage of a career change requiring a temporary income dip due to inadequate savings. For a business, it could mean being unable to invest in new technology, expand into new markets, or weather a temporary market downturn, thereby losing competitive edge.
Furthermore, borderline conditions often signify inefficiencies or suboptimal resource allocation. Slowly, almost imperceptibly, these inefficiencies can erode your wealth. Higher interest rates on loans due to a lower credit score, missed investment returns from unoptimized portfolios, or higher operating costs in a business due to overlooked inefficiencies all chip away at your financial foundation over time. This slow bleed, though less dramatic than a sudden loss, can be just as damaging in the long run.
Escalation to Critical Financial Distress
The most significant risk of ignoring a borderline financial ECG is the eventual escalation to critical distress. Without intervention, minor issues tend to compound and worsen, especially when confronted with unforeseen challenges. A personal example might be a stagnant savings rate combined with an unexpected job loss, leading directly to reliance on high-interest debt. For a business, borderline cash flow coupled with a sudden supply chain disruption can quickly lead to insolvency.
When a financial situation tips from “borderline” to “critical,” the solutions become far more painful and limited. Personal bankruptcies, business closures, and significant asset liquidation are often the outcomes when early warning signals are unheeded. The cost of remediation skyrockets, and the path to recovery becomes arduous, if not impossible. The foresight to address a borderline issue prevents it from becoming an emergency.
Strategies for Addressing Borderline Financial Health
Identifying a borderline financial ECG is only the first step; the critical phase is intervention. The strategies for addressing these signals vary depending on whether you’re focusing on personal finance, investing, or business finance, but the underlying principle remains the same: proactive, targeted action.
Personal Finance: Budgeting, Debt Management, Emergency Funds
If your personal financial ECG shows borderline readings, focus on foundational strength:
-
Rigorous Budgeting: Implement a detailed budget to track every dollar in and out. Identify unnecessary expenses and reallocate funds towards savings or debt repayment. Tools like YNAB, Mint, or even a simple spreadsheet can be invaluable.
-
Targeted Debt Management: Prioritize high-interest debt (e.g., credit card debt) using strategies like the debt snowball or avalanche method. Negotiate with creditors if necessary. The goal is to reduce your debt-to-income ratio to a healthy level.
-
Fortify Your Emergency Fund: Aim for 6-12 months of essential living expenses in a liquid, easily accessible account. This buffer is your primary defense against unexpected financial shocks.
-
Boost Savings and Investments: Once debt is under control and your emergency fund is solid, increase your contributions to retirement accounts and other investment vehicles.
-
Improve Credit Score: Review your credit report for errors, pay bills on time, keep credit utilization low, and avoid opening too many new accounts.
Investing: Portfolio Rebalancing, Risk Assessment, Diversification
For investors facing a borderline portfolio ECG:
-
Portfolio Rebalancing: If your asset allocation has drifted due to market performance, rebalance your portfolio to bring it back in line with your target risk profile. This ensures you’re not inadvertently taking on too much or too little risk.
-
Risk Assessment: Re-evaluate your risk tolerance and capacity. Are you comfortable with your current level of exposure? If your portfolio is too concentrated, consider diversifying.
-
Diversification Review: Ensure your investments are adequately diversified across asset classes (stocks, bonds, real estate), geographies, and sectors. A borderline lack of diversification can expose you to unnecessary systemic risk.
-
Tax Efficiency: Optimize your investment accounts for tax efficiency (e.g., Roth vs. Traditional IRAs/401ks, tax-loss harvesting).
-
Review Fees: High investment fees can significantly erode returns over time. Look for lower-cost alternatives like index funds or ETFs.
Business Finance: Cash Flow Optimization, Cost Control, Strategic Growth
For businesses with borderline financial health signals:
-
Cash Flow Optimization: Implement tighter accounts receivable and payable management. Offer early payment incentives to customers, negotiate extended payment terms with suppliers, and explore lines of credit for short-term liquidity needs.
-
Rigorous Cost Control: Conduct a thorough review of all operating expenses. Identify areas for reduction without compromising quality or core operations. This could involve renegotiating vendor contracts, optimizing staffing, or investing in automation.
-
Revenue Diversification: If your revenue is overly reliant on a few clients or products, explore new markets, develop new offerings, or expand your customer base to mitigate risk.
-
Strategic Growth Initiatives: Invest in areas that promise strong returns on investment, such as marketing, R&D, or technology upgrades. Ensure these investments are carefully planned and monitored.
-
Debt Restructuring: If debt is a concern, explore options like refinancing at lower rates or consolidating multiple loans to improve cash flow.
-
Operational Efficiency: Streamline processes, reduce waste, and improve productivity to boost profit margins.
Proactive Monitoring and Long-Term Financial Well-being
The proactive management of a metaphorical “borderline ECG” is not a one-time fix but an ongoing commitment to financial health. It involves continuous monitoring, regular check-ups, and a willingness to adapt strategies as circumstances evolve.
Regular Financial Check-ups
Just as you wouldn’t wait for a medical emergency to visit the doctor, you shouldn’t wait for a financial crisis to review your finances. Schedule regular, comprehensive financial check-ups. For individuals, this might be quarterly or semi-annually, reviewing budgets, investment performance, and net worth. For businesses, monthly or quarterly financial reviews are standard, often involving external auditors or financial advisors. These routine examinations help you catch borderline signals early and ensure your strategies remain aligned with your goals.
Leveraging Financial Tools and Expertise
You don’t have to navigate your financial health journey alone. Utilize the wealth of financial tools available today: budgeting apps, investment platforms with analytical features, business intelligence dashboards. For complex situations or simply for objective guidance, engage with financial professionals—financial planners, investment advisors, business consultants, or accountants. Their expertise can help you interpret borderline signals, develop effective strategies, and provide accountability.
A “borderline ECG” in finance is a powerful metaphor for recognizing the subtle, often overlooked, signals that indicate your financial health is not quite where it should be. It’s an invitation to pause, assess, and act decisively before minor issues escalate into major crises. By embracing proactive monitoring and strategic intervention, you can transform these early warnings into opportunities for strengthening your financial foundation, ensuring long-term well-being and prosperity.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.