
The world of finance, often perceived as complex and intimidating, is built upon a bedrock of fundamental mathematical principles. From calculating daily expenses and managing savings to understanding investment returns and analyzing market trends, an innate grasp of numbers is indispensable. Among these foundational concepts, the seemingly simple idea of an “equivalent fraction” stands as a silent enabler, a gateway to comprehending percentages, ratios, and proportions – all critical tools in the financial toolkit.
While the term “equivalent fraction” might evoke memories of school mathematics, its practical implications extend far beyond the classroom, subtly influencing every financial decision we make. It’s the underlying principle that allows us to compare different investment opportunities, decipher interest rates, understand budgeting allocations, and even interpret complex economic data. By demystifying what an equivalent fraction is and, more importantly, why it matters in a financial context, we can unlock a deeper level of financial literacy, empowering individuals to make more informed and strategic monetary choices. This article will embark on a journey from the basic definition of equivalent fractions to their pervasive and often-unseen role in personal finance, investing, and the broader economic landscape, proving that mastering this seemingly elementary concept is a vital step toward financial empowerment.

The Core Concept: Deconstructing Equivalent Fractions
Before we delve into the financial applications, it’s crucial to firmly establish what an equivalent fraction is. At its heart, it’s a concept of representing the same value or proportion in different numerical forms.
Defining “Equivalent” in Mathematics
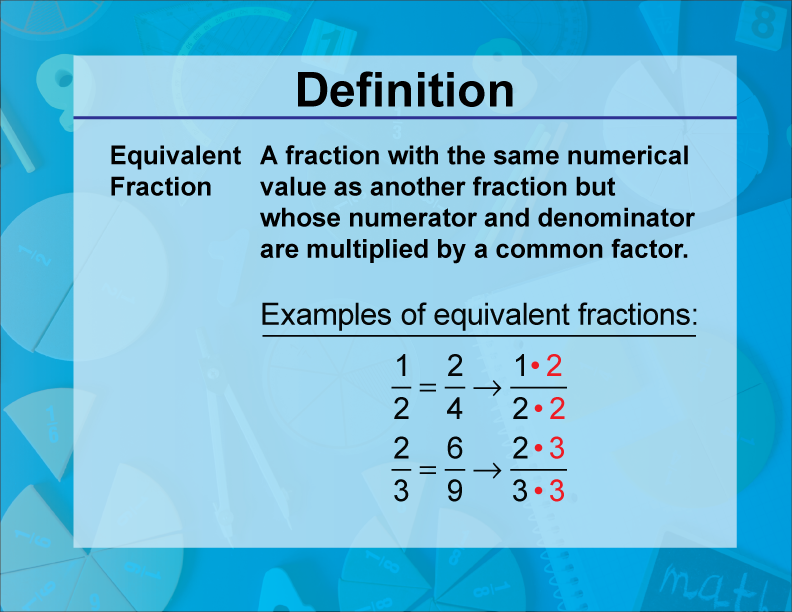
The word “equivalent” literally means equal in value, function, or meaning. In mathematics, when we speak of equivalent fractions, we are referring to different fractions that represent the exact same portion or amount of a whole. For instance, if you have a pizza cut into two equal slices and you eat one, you’ve eaten 1/2 of the pizza. If you have the same pizza cut into four equal slices and you eat two, you’ve eaten 2/4 of the pizza. In both scenarios, the amount of pizza consumed is identical, making 1/2 and 2/4 equivalent fractions. They look different numerically but hold the same value.
The beauty of equivalent fractions lies in their ability to simplify complex values or, conversely, to express values in a way that makes comparisons easier. This fundamental principle is the bedrock for understanding percentages (which are essentially fractions out of 100), ratios (which compare quantities), and proportions (which express relationships between ratios). Without a solid grasp of this equivalency, subsequent financial concepts become significantly harder to internalize.
Visualizing Equivalent Fractions: A Pie of Understanding
Visual aids are often the most effective way to grasp abstract mathematical concepts. Imagine a single circle, representing one whole unit – perhaps a dollar, an investment portfolio, or a company’s total profit.
-
If you divide that circle into two equal parts and shade one, you have 1/2.
-
If you divide the same circle into four equal parts and shade two, you have 2/4. Notice the shaded area is precisely the same size as 1/2.
-
If you divide it into eight equal parts and shade four, you have 4/8. Again, the shaded portion remains unchanged.
This visual demonstration vividly illustrates that 1/2, 2/4, and 4/8 are all equivalent fractions. They are different ways of describing the same part of the whole. This conceptual understanding is critical when we later consider how a 25% discount (which is 25/100 or 1/4) affects a price, or how dividing a profit among four partners (each getting 1/4) compares to dividing it among eight (each getting 2/8). The total value remains constant; only the way we express it numerically changes.
The Golden Rule: Multiplying and Dividing by One
The mathematical operation that allows us to find equivalent fractions is surprisingly elegant: you multiply or divide both the numerator (the top number) and the denominator (the bottom number) by the same non-zero number. This is often referred to as multiplying or dividing by a “fancy one.”
For example, to find a fraction equivalent to 1/2:
-
Multiply the numerator (1) by 2 and the denominator (2) by 2: (1 * 2) / (2 * 2) = 2/4.
-
Multiply the numerator (1) by 5 and the denominator (2) by 5: (1 * 5) / (2 * 5) = 5/10.
Conversely, to simplify a fraction like 6/12:
- Divide the numerator (6) by 6 and the denominator (12) by 6: (6 / 6) / (12 / 6) = 1/2.
The reason this works is that when you multiply or divide both the numerator and denominator by the same number, you are essentially multiplying or dividing the entire fraction by 1 (e.g., 2/2 = 1, 5/5 = 1). And multiplying or dividing any number by 1 does not change its value. This simple rule is the bedrock for converting fractions to percentages, simplifying financial ratios, and finding common denominators to compare different financial scenarios.
Beyond the Basics: Practical Applications in Personal Finance
With a firm grasp of what equivalent fractions are, we can now explore their direct and indirect roles in managing personal finances. From daily budgeting to understanding various financial products, the concept of equivalency is constantly at play.
Budgeting and Allocating Resources: Fractions in Your Wallet
Budgeting is, at its core, an exercise in fractional allocation. You take your total income (the whole) and divide it into various categories (fractions). For instance, if you decide to spend no more than 1/4 of your income on housing, 1/5 on food, and 1/10 on entertainment, you are implicitly working with equivalent fractions.
-
To compare these allocations accurately, you might convert them to a common denominator or, more commonly in personal finance, to percentages. Understanding that 1/4 is equivalent to 25% (25/100) or 1/5 is equivalent to 20% (20/100) allows for direct comparison and summation. If your housing is 25%, food is 20%, and entertainment is 10%, you immediately see that these three categories account for 55% of your income.
-
This ability to convert fractions into percentages (or back again) using the concept of equivalency is vital for ensuring your expenses don’t exceed your income. It helps you visualize how much of your “pie” (income) each category consumes and adjust accordingly. Without this fractional understanding, budgeting becomes a series of disjointed numbers rather than a coherent plan for resource allocation.
Discounts, Sales, and Interest Rates: The Power of Percentages
Perhaps the most common appearance of equivalent fractions in daily finance is through percentages. A percentage is simply a fraction where the denominator is always 100. So, 25% is equivalent to 25/100, which can be simplified (using the golden rule of division by 25) to 1/4.
-
Discounts and Sales: When a store offers “20% off,” you’re actually dealing with an equivalent fraction. 20% is 20/100, which simplifies to 1/5. This means you save 1/5 of the original price. Knowing this allows for quick mental math. If an item costs $50, 1/5 off means a $10 saving.
-
Interest Rates: Whether it’s the interest you earn on a savings account or the interest you pay on a loan or credit card, it’s always expressed as a percentage. A 5% annual interest rate means 5/100 (or 1/20) of the principal amount will be charged or earned over a year. Understanding this equivalency is crucial for calculating future loan payments, assessing the true cost of borrowing, or projecting savings growth. It enables you to grasp the proportional impact of that percentage on your overall financial health.
Comparing Financial Products: Making Informed Choices
When faced with multiple options for savings accounts, loan products, or insurance policies, equivalent fractions (often in the guise of percentages or simplified ratios) become invaluable for comparison.
-
Loan Offers: One lender might offer a loan with an annual percentage rate (APR) of 6%, while another offers 6.5%. Converting these percentages to fractions (6/100 vs. 6.5/100) helps you understand the slight difference in the proportion of interest you’ll pay relative to the principal.
-
Savings Rates: Similarly, comparing savings accounts with different interest rates (e.g., 0.5% vs. 0.75%) requires an understanding that these are fractional returns on your deposit. While the numbers seem small, the ability to convert and compare these fractions allows you to identify the best proportional return for your money.
-
Credit Card Rewards: Some cards offer “3% cash back on groceries” and “1% on all other purchases.” These are direct applications of equivalent fractions as percentages, guiding your spending to maximize proportional returns. Making informed financial choices hinges on the ability to interpret and compare these fractional representations of value.
Investing and Wealth Building: Fractions of Growth
The world of investing, with its emphasis on growth, returns, and portfolio diversification, relies heavily on a sophisticated understanding of fractions, ratios, and percentages. Equivalent fractions are the unseen bedrock beneath these complex financial metrics.

Understanding Portfolio Allocation: Diversifying Your Investments
A cornerstone of smart investing is diversification, which involves spreading your investments across different asset classes (stocks, bonds, real estate, etc.) to mitigate risk. This “spreading” is inherently a fractional exercise.
-
An investment advisor might suggest a portfolio allocation like “60% stocks, 30% bonds, 10% cash.” These percentages are equivalent fractions (60/100, 30/100, 10/100) that represent the proportion of your total investment capital dedicated to each asset class.
-
Understanding equivalent fractions allows you to quickly adjust this allocation as your financial goals or risk tolerance changes. If you have $10,000 to invest, knowing that 60% is equivalent to 6/10 or 3/5 means you allocate $6,000 to stocks. This simple conversion is fundamental to constructing and rebalancing a diversified portfolio, ensuring your investments are proportionally aligned with your strategy.
Stock Splits, Dividends, and Ratios: Deeper Financial Insights
Beyond simple allocation, equivalent fractions underpin several nuanced aspects of stock market activity and company valuation.
-
Stock Splits: A company might announce a 2-for-1 stock split. This means for every share you own, you now own two. While the number of shares doubles, the value of your total holding remains the same immediately after the split. Each new share is now worth 1/2 of its pre-split value. This is a direct application of equivalent fractions – 1 share at X value is equivalent to 2 shares at X/2 value.
-
Dividends: Dividends are often expressed as a percentage yield, representing the fractional portion of a company’s profit distributed per share. A 4% dividend yield signifies that you receive 4/100 (or 1/25) of the stock’s price in annual dividends. This fractional understanding helps investors compare income-generating potential across different stocks.
-
Financial Ratios: Professional investors and analysts heavily rely on financial ratios (e.g., Price-to-Earnings (P/E) ratio, Debt-to-Equity ratio) to evaluate a company’s health and potential. These ratios are, by definition, fractions comparing one financial metric to another. Understanding equivalent fractions allows analysts to simplify these ratios, compare them to industry benchmarks, and derive meaningful insights into a company’s proportional valuation or leverage.
Compounding Returns: The Fractional Path to Exponential Growth
The concept of compounding interest, famously dubbed “the eighth wonder of the world” by Albert Einstein, is fundamentally a fractional one. It’s the process where the interest you earn also starts earning interest.
-
While the calculation itself involves exponents, the underlying mechanism is that your principal grows by a certain fraction (the interest rate) each period, and then that larger principal again grows by the same fraction in the next period.
-
Imagine a 10% annual return (1/10). In the first year, your $100 grows by 1/10 ($10) to $110. In the second year, your $110 grows by 1/10 ($11) to $121. The “extra” dollar in the second year is the interest earned on the previous year’s interest. This recursive application of a fractional growth rate leads to exponential wealth accumulation, making it a powerful concept for long-term investing and retirement planning.
Business Finance and Economic Understanding: Scaling with Fractions
At a broader level, business finance and macroeconomics extensively utilize fractions and ratios to analyze performance, allocate resources, and understand market dynamics.
Profit Margins and Cost Analysis: Business Ratios
Businesses constantly analyze their financial performance using various metrics, many of which are ratios or percentages.
-
Profit Margins: Gross profit margin (Gross Profit / Revenue) and Net profit margin (Net Income / Revenue) are crucial indicators of a company’s efficiency. These are fractions that express what proportion of revenue turns into profit. Understanding equivalent fractions allows business owners to compare their margins to industry averages or competitors, identify areas for cost reduction, and make strategic pricing decisions. For example, a 15% net profit margin (15/100 or 3/20) immediately tells you that for every dollar of revenue, 15 cents are retained as profit.
-
Cost Analysis: Breaking down expenses as a fraction of total costs or revenue helps businesses identify disproportionate spending. Is the cost of goods sold 70% of revenue (7/10)? Is marketing spending 10% (1/10)? These fractional insights drive operational efficiency and financial planning.
Market Share and Growth: Understanding Proportions
Companies are keenly interested in their market share – the proportion of total sales in an industry that their company captures. This is a direct application of fractions.
-
If a company has $100 million in sales in an industry with $1 billion in total sales, its market share is $100M / $1,000M = 1/10, or 10%. Understanding this fractional representation helps businesses track their competitive position, identify growth opportunities, and strategize for expansion.
-
Growth rates, often expressed as percentages, also rely on fractional understanding. A 5% year-over-year revenue growth means the current year’s revenue is 5/100 (or 1/20) higher than the previous year’s, a vital metric for assessing company vitality.
Economic Indicators and Statistical Interpretation
Macroeconomic analysis, which informs government policy and investment decisions, is replete with fractional concepts.
-
Inflation Rates: The inflation rate is the percentage (fraction out of 100) increase in the price level of goods and services over a period. Understanding this percentage as an equivalent fraction helps economists and policymakers gauge the rate at which purchasing power is eroding.
-
GDP Growth: Gross Domestic Product (GDP) growth is typically expressed as a percentage, indicating the fractional increase in a country’s economic output. These figures guide fiscal and monetary policy and impact investor confidence.
-
Unemployment Rates: The unemployment rate is the fraction of the labor force that is unemployed, expressed as a percentage. This critical economic indicator directly influences policy decisions regarding job creation and social welfare.
In each of these instances, the ability to interpret, compare, and manipulate fractions (often presented as percentages or ratios) is paramount to understanding economic health and making informed decisions that affect entire populations and global markets.
Mastering Equivalent Fractions: A Stepping Stone to Financial Empowerment
The journey from understanding “what is an equivalent fraction” to appreciating its profound impact on financial literacy might seem extensive, but it underscores a crucial truth: foundational mathematical skills are not merely academic exercises; they are practical tools for navigating the complexities of the real world, especially the financial one.
Bridging the Gap: From Abstract Math to Real-World Money
The disconnect between abstract mathematical concepts taught in school and their tangible applications in daily life often leads to math anxiety and financial disengagement. By drawing a clear, consistent line between equivalent fractions and real-world financial scenarios – from calculating a sale discount to understanding portfolio diversification – we empower individuals to see math not as a hurdle, but as a powerful key to unlocking financial understanding. When students realize that 1/4 is not just an arbitrary fraction but also represents 25% of their paycheck or the proportion of their loan payment going to interest, the relevance becomes immediate and impactful.
Cultivating Confidence in Financial Calculations
A solid grasp of equivalent fractions builds confidence. It allows individuals to:
-
Quickly estimate costs and savings.
-
Mentally compare different financial offers.
-
Understand the proportional impact of interest rates and returns.
-
Feel more capable when engaging with financial advisors or reviewing financial statements.
This confidence reduces reliance on others for basic calculations and fosters a proactive approach to financial planning, moving individuals from passive consumers of financial services to active participants in their wealth journey.
The Lifelong Value of Mathematical Fluency
Ultimately, the mastery of equivalent fractions is more than just a specific skill; it’s a stepping stone to broader mathematical fluency. It lays the groundwork for understanding algebraic equations, statistical analysis, and complex financial modeling – all of which become increasingly relevant as financial lives grow more intricate. In a world saturated with financial data, the ability to dissect, interpret, and act upon fractional information is not just an advantage; it’s a necessity for achieving personal financial goals, building wealth, and contributing meaningfully to economic discussions. Thus, investing time in truly understanding “what is an equivalent fraction” is perhaps one of the most fundamental investments one can make in their financial future.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.