
Understanding the racial composition of the United States is more than a sociological exercise; it is a fundamental requirement for anyone navigating the worlds of personal finance, macroeconomics, and institutional investing. Demographic data serves as the bedrock upon which market trends are predicted, consumer spending is analyzed, and wealth management strategies are built. As of the most recent decennial census and subsequent American Community Survey updates, the United States is undergoing a profound demographic shift that is directly impacting the flow of capital.
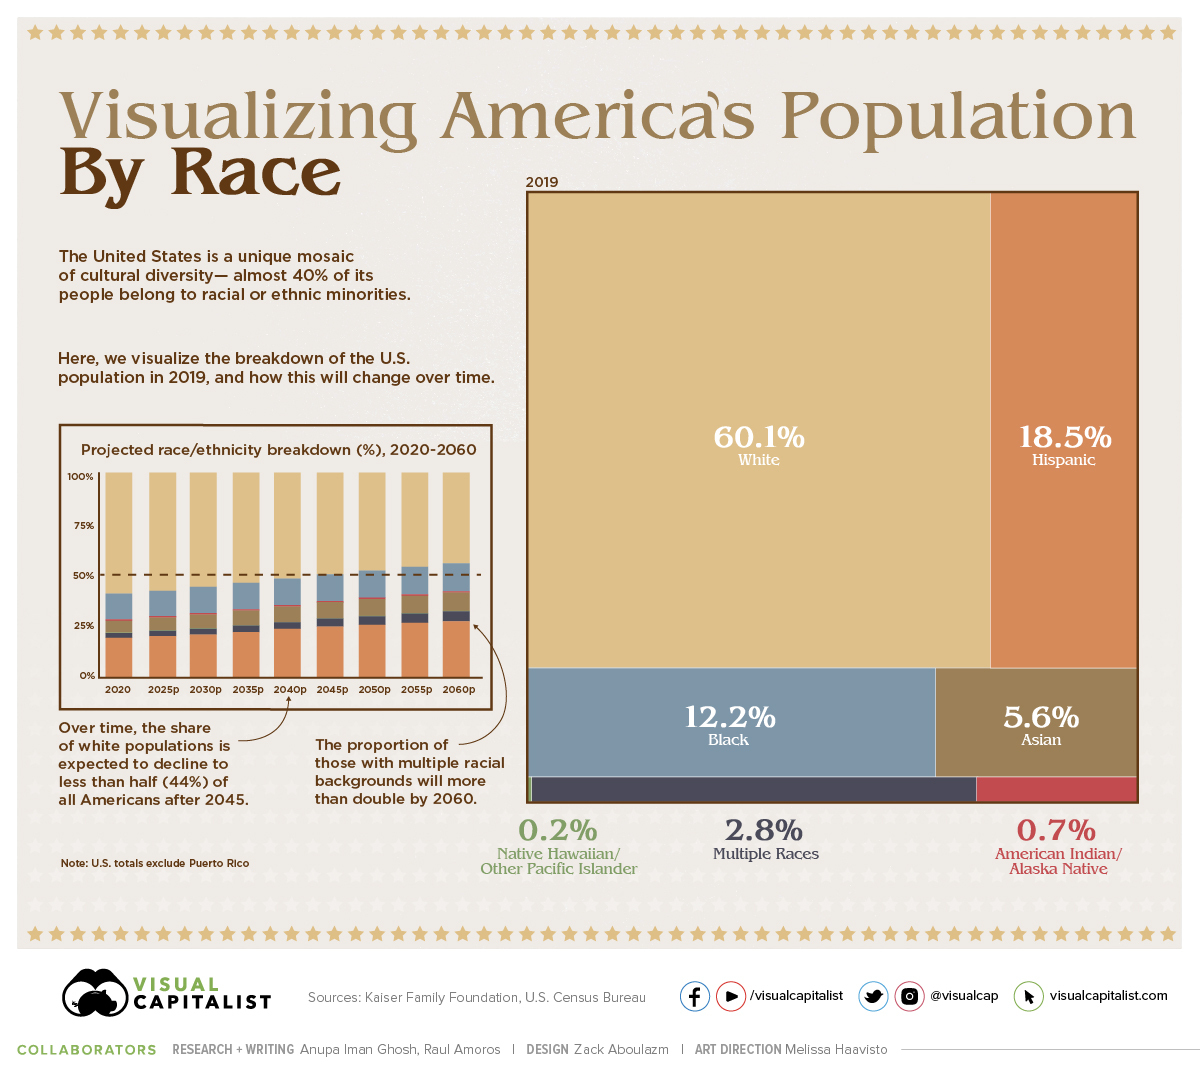
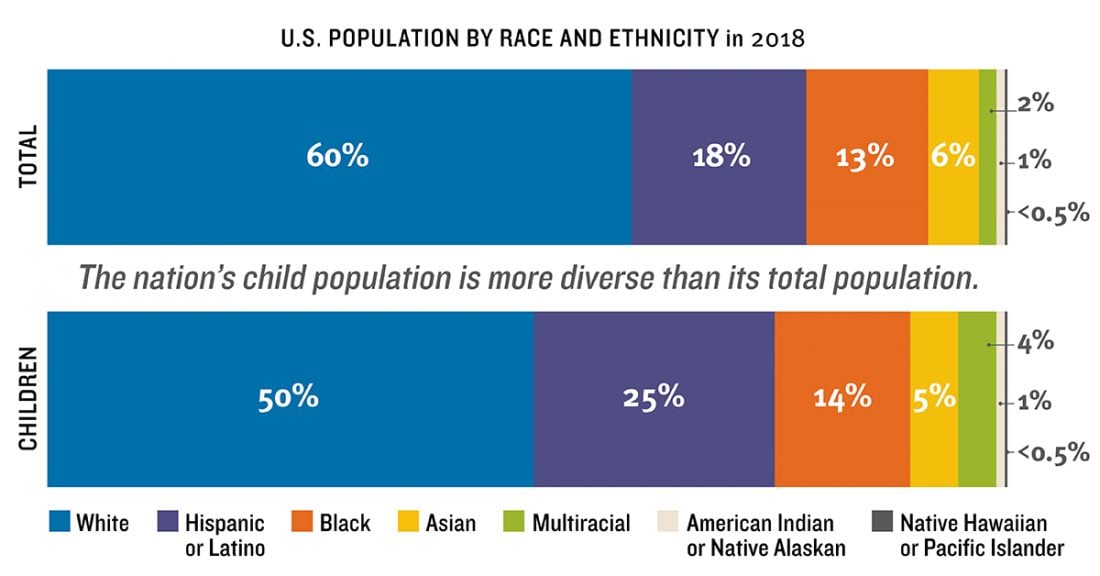
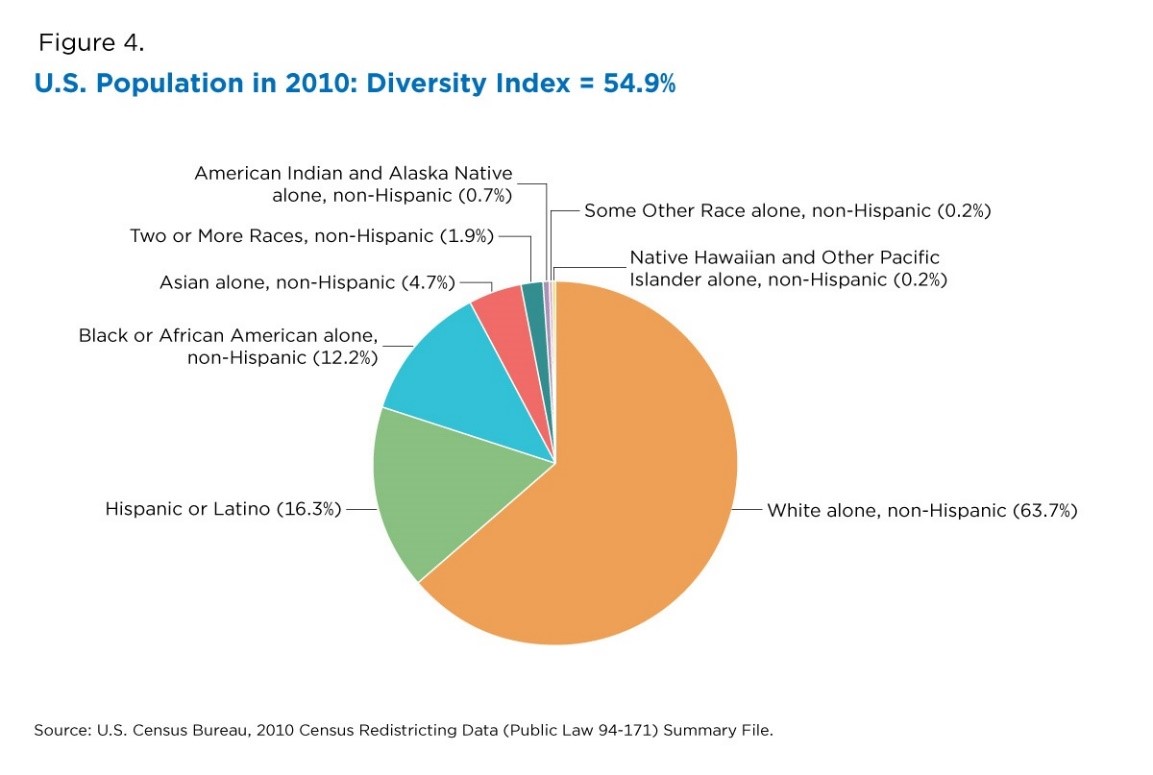
Today, the U.S. population is approximately 59% White (non-Hispanic), 19% Hispanic or Latino, 13% Black or African American, 6% Asian, and about 3% identifying as multiracial or from other groups. For the astute investor or financial professional, these percentages represent shifting “economic centers of gravity.” This article explores the intersection of racial demographics and financial systems, analyzing how the changing face of America dictates the future of the dollar.
The Statistical Foundation of the American Consumer Economy
The sheer volume of the American economy is driven by domestic consumption. Therefore, knowing who the consumers are—and their specific financial trajectories—is essential for understanding market demand. The current racial percentages reveal a country in transition, moving toward a “majority-minority” status by the mid-2040s. This shift has immediate implications for business finance and retail investment.
The Rising Purchasing Power of the Hispanic Market
The Hispanic population, currently making up nearly one-fifth of the nation, represents the fastest-growing segment of domestic purchasing power. Economically, this demographic is characterized by a younger median age compared to the national average. From a “Money” perspective, this signifies a massive wave of first-time homebuyers, new credit consumers, and life-insurance seekers entering the market over the next decade. Financial institutions are increasingly pivoting their service models to cater to this $2.5 trillion powerhouse of cumulative purchasing power, recognizing that the future of banking growth lies in this specific demographic expansion.
Analyzing the Asian-American Wealth Profile and Investment Trends
While representing roughly 6% of the population, the Asian-American demographic holds a disproportionately high level of household income and educational attainment. This translates into a unique profile for the wealth management industry. This group often shows a high propensity for high-growth tech investing and real estate accumulation. For financial advisors, understanding the nuances of this demographic’s saving habits—which often trend higher than the national average—is key to capturing a significant portion of the nation’s liquid investment capital.
Wealth Distribution and the Persistent Racial Wealth Gap
To discuss money in America without addressing the distribution of that money across racial lines would be to ignore the most significant hurdle in the U.S. financial system. Despite the growing diversity, the “racial wealth gap” remains a defining characteristic of the American economic landscape. This gap is not merely a social issue; it is a structural financial reality that affects liquidity, risk tolerance, and capital gains across the country.
Barriers to Entry in Real Estate and Homeownership
Historically, real estate has been the primary vehicle for middle-class wealth creation in the United States. However, when we look at the racial percentages, the homeownership rates tell a story of financial divergence. While the White homeownership rate often hovers around 74%, the rate for Black households is closer to 44-45%. This 30-percentage-point gap represents trillions of dollars in “missing” equity that could otherwise be used for small business collateral, education funding, or retirement security. For the finance professional, this gap indicates an underserved market where specialized lending products and financial literacy programs could unlock significant latent value.
Retirement Planning and the Transfer of Generational Wealth
The “Great Wealth Transfer”—the movement of assets from Baby Boomers to younger generations—is estimated to involve over $68 trillion. However, because of the racial makeup of the current aging wealthy population, this transfer is not being distributed equally across the racial percentages of the country. White households are significantly more likely to receive an inheritance than Black or Hispanic households. This discrepancy creates different “financial starting lines” for young investors. Understanding these nuances is vital for fintech companies designing apps for “Gen Z” or “Millennials,” as the financial needs of a debt-free inheritor differ vastly from those of a first-generation wealth builder.
Strategic Investing in a Multicultural America
For the modern investor, demographic shifts are “alpha”—they provide the insights needed to beat the market. As the percentages of the American population shift, the sectors that will see the most growth are those that align with the needs and values of an increasingly diverse public.
Targeting Growth in Minority-Owned Businesses (MBEs)
There is a growing trend in “Impact Investing” and “Venture Capital” to focus on Minority-Owned Businesses. Currently, while people of color make up roughly 40% of the population, they own a much smaller percentage of employer firms. This “representation gap” is increasingly seen by savvy investors as an arbitrage opportunity. By providing capital to underserved Black, Hispanic, and Asian entrepreneurs, investors are tapping into markets that have been historically overlooked by traditional big-ticket lenders. The financial return on these investments often outperforms the broader market because these businesses are solving problems for a rapidly growing, diverse consumer base.
Demographic Shifts as an Investment Signal in Healthcare and FinTech
Demographics influence sector-specific performance. For instance, the aging White population creates a high demand for traditional senior living and Medicare-related financial products. Conversely, the younger Hispanic and Black populations drive demand for mobile-first banking solutions (FinTech). Investors who track racial percentages understand that “The Unbanked” or “Underbanked” segments are largely concentrated in minority communities. Companies that successfully bridge this gap through technology are not just performing a social good; they are securing a massive, loyal customer base that will grow in value over the next thirty years.
The Future of Money in a “Majority-Minority” Nation
By 2045, the U.S. Census Bureau projects that no single racial group will make up a majority of the population. This transition will redefine the American economy, shifting the focus from traditional legacy systems to more inclusive, tech-driven, and globally-connected financial structures.
Economic Policy and the Necessity of Inclusivity
From a business finance perspective, the American economy cannot reach its full potential if large segments of the population are financially marginalized. Economists suggest that closing the racial wealth gap could add between $1 trillion and $1.5 trillion to the U.S. GDP over the next decade. As the percentages of Black, Hispanic, and Asian Americans continue to rise, the health of the entire U.S. economy—and the strength of the U.S. Dollar—will depend on these groups’ ability to earn, save, and invest at the same rates as the current majority. For policymakers and corporate treasurers, diversity is no longer an HR metric; it is a prerequisite for national solvency.
Technology’s Role in Closing the Financial Divide
The digital revolution in finance (DeFi, AI-driven credit scoring, and fractional investing) is the primary tool for democratizing wealth. As the American racial percentages change, we are seeing a shift away from “relationship banking” (which often excluded minorities) toward “algorithmic banking.” AI tools that look at cash flow rather than just credit scores are allowing a more diverse group of Americans to access capital. This technological shift is essential for a country where the minority populations are the fastest-growing segment of the workforce. The intersection of technology and demographic data is where the next generation of American millionaires will be minted.
In conclusion, the percentages of races in America are a vital map for the future of money. By recognizing the growth of the Hispanic market, the investment power of the Asian-American community, and the untapped potential within the Black community, investors and financial professionals can position themselves for a more volatile but ultimately more prosperous economic future. Demographics are the ultimate long-term indicator; to follow the money, one must first follow the people.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.