
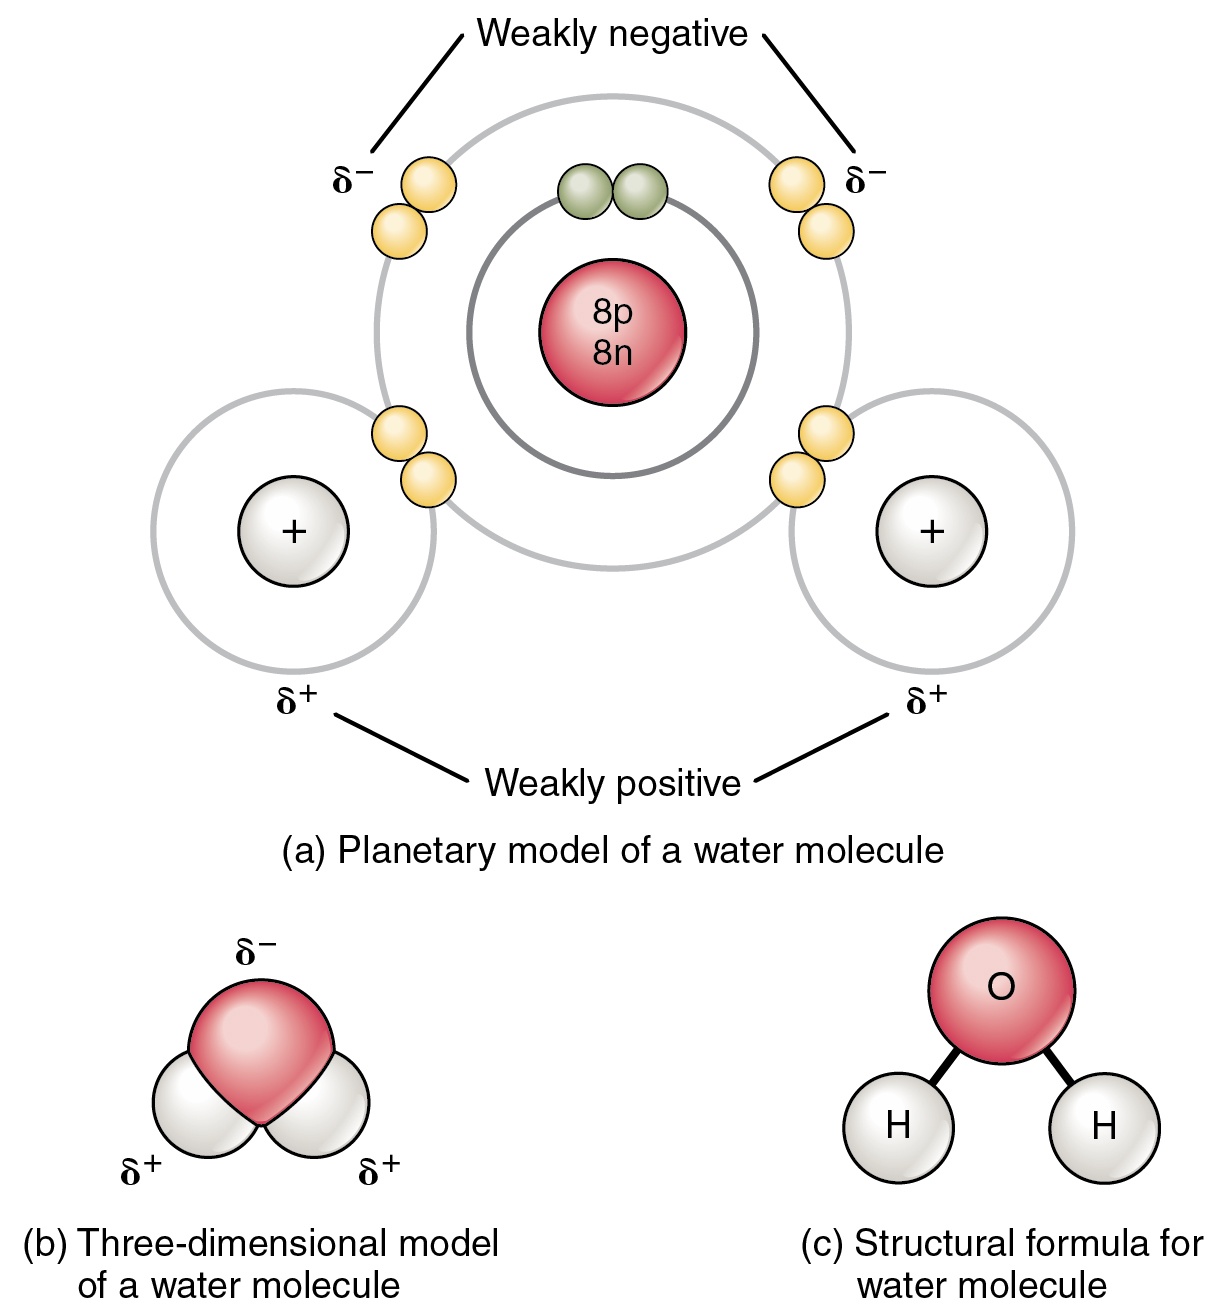
In the world of chemistry, the bonds in water are what hold life together—polar covalent bonds and hydrogen bonds that create surface tension and solvent properties. In the world of finance, however, “water bonds” represent something equally fundamental: the foundational debt instruments that secure our global infrastructure and the metaphorical “liquidity” that keeps the markets flowing.
Understanding what type of bonds are in water—meaning the financial vehicles used to fund, manage, and profit from the world’s most precious resource—is essential for any modern investor. As we move into an era defined by climate volatility and infrastructure renewal, the intersection of fixed-income assets and the water sector has become a primary focus for institutional and retail investors alike.
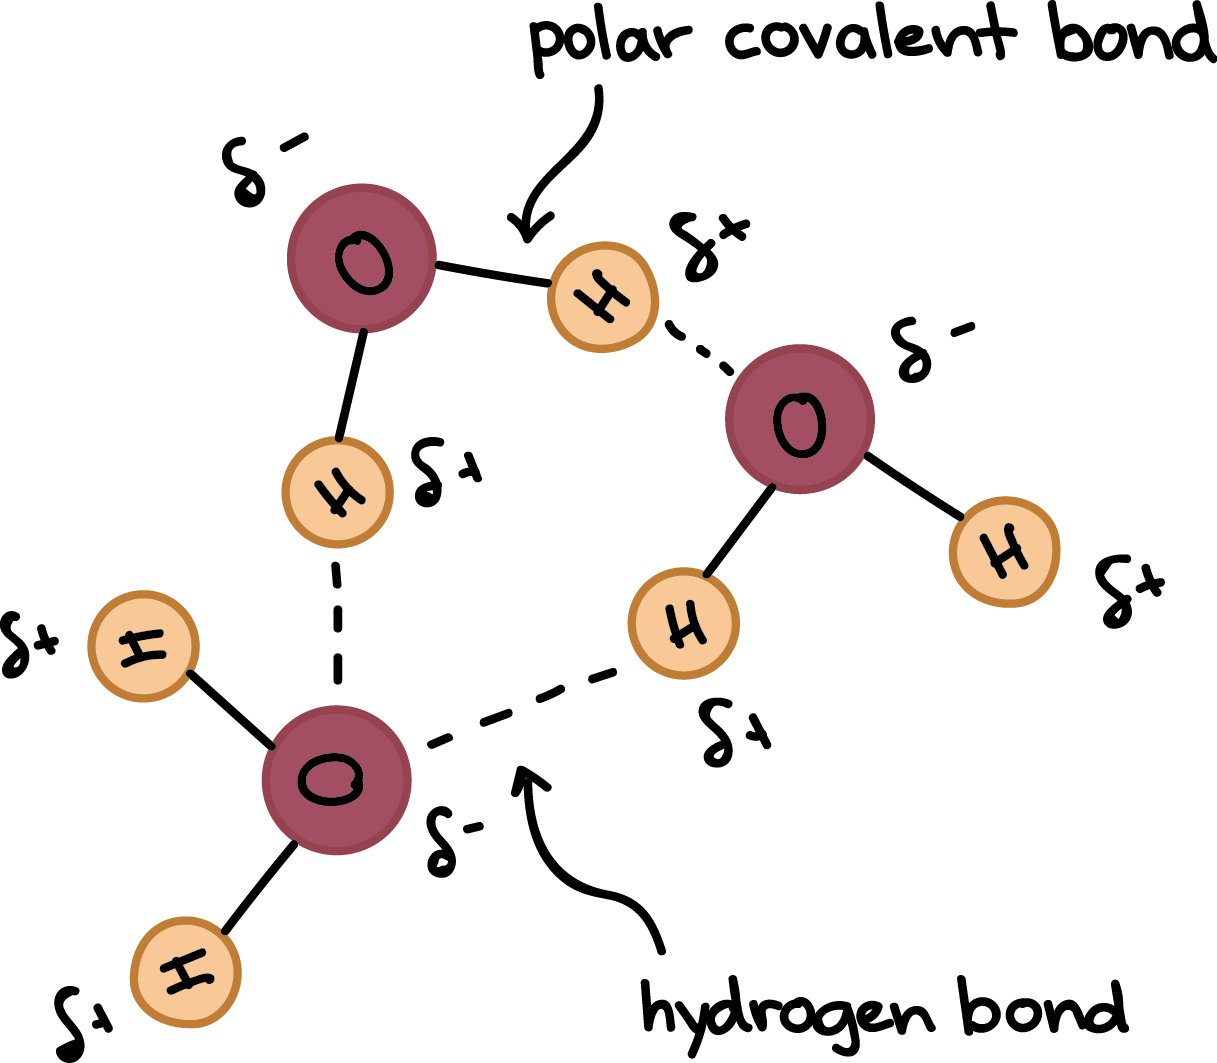
The Foundation of Infrastructure: Municipal and Revenue Bonds
At the most basic level, when we ask what types of bonds are in water, we are usually looking at the municipal bond market. These are the debt securities issued by states, cities, counties, and other governmental entities to fund day-to-day obligations and to finance large-scale capital projects like water treatment plants, sewage systems, and dams.
General Obligation (GO) Bonds
General Obligation bonds are backed by the “full faith and credit” of the issuing municipality. This means the issuer can use any available resources—including tax revenue—to repay the bondholders. In the context of water, a GO bond might be used to fund a city-wide drainage overhaul. For the conservative investor, these are often seen as low-risk “bonds in water” because the government’s taxing power serves as a robust safety net.
Revenue Bonds
Unlike GO bonds, Revenue Bonds are repaid specifically from the income generated by the project they funded. For example, if a county issues a bond to build a new desalination plant, the debt is repaid from the water bills paid by the citizens who use that plant. These bonds are common in the utility sector. They offer a direct link between the physical asset (the water system) and the financial return. For an investor, understanding the “bond” in this water project requires analyzing the consumption patterns and population growth of the service area.
Private Activity Bonds (PABs)
In certain jurisdictions, private companies are brought in to manage public water systems through public-private partnerships (P3s). Private Activity Bonds allow private developers to access the tax-exempt bond market to fund water projects that provide a public benefit. These are sophisticated instruments that offer a unique blend of corporate efficiency and public sector stability.
The Evolution of ESG: Blue Bonds and Green Financing
As the investment landscape shifts toward Environmental, Social, and Governance (ESG) criteria, a new species of bond has emerged. If we look at the modern “bonds in water,” we find “Blue Bonds.” These are a relatively new financial innovation designed specifically to support oceanic and freshwater health.
What are Blue Bonds?
A Blue Bond is a debt instrument issued by governments, development banks, or corporations to raise capital for projects that protect the ocean and its resources. This might include sustainable fisheries, coral reef protection, or reducing plastic pollution in waterways. Like Green Bonds, Blue Bonds are verified by third-party auditors to ensure the proceeds are used specifically for environmental water projects.
The Role of Multilateral Development Banks
Many “water bonds” in the international market are backed by organizations like the World Bank or the Asian Development Bank. These entities provide “credit enhancement,” which makes the bonds safer for private investors to buy. For an investor looking for impact, these bonds provide a way to fund water security in developing nations while earning a predictable fixed-income return.
Sustainability-Linked Bonds (SLBs)
Unlike traditional Blue Bonds, which earmark funds for specific projects, SLBs are corporate bonds where the interest rate (coupon) is tied to the company’s performance against water-related targets. For instance, a global beverage corporation might issue a bond where the interest rate drops if they reduce their water intensity per liter of product. These represent a “bond” between the company’s financial health and its water stewardship.
Assessing Risk: The Impact of Climate Change on Water Assets
To understand what types of bonds are in water, one must also understand the risks inherent in the medium itself. Water is a volatile asset class because of its susceptibility to climate change. Investors must perform rigorous due diligence to ensure the underlying “bonds” don’t dissolve under environmental pressure.
Drought and Revenue Risk
For revenue-backed water bonds, a prolonged drought can be a double-edged sword. While water scarcity might drive up prices, it often leads to mandatory conservation measures. If citizens use less water, the utility collects less revenue, potentially jeopardizing the debt service on the bond. Professional investors look for “rate-setting flexibility”—the legal ability of a utility to raise prices to cover shortfalls.
Regulatory and Political Risk
Water is often viewed as a human right, not just a commodity. This makes the “bonds in water” subject to heavy regulation. Changes in environmental laws (such as new limits on “forever chemicals” like PFAS) can require massive capital expenditures from utilities, leading to the issuance of more debt and potentially diluting the value of existing bonds.
Physical Asset Vulnerability
Infrastructure bonds are only as good as the infrastructure they fund. In an era of rising sea levels and extreme weather, the physical “bonds” of water systems—the pipes, pumps, and levees—are at risk. Smart money is currently flowing into “Resilience Bonds,” which are designed to fund projects that specifically mitigate the risk of catastrophic water-related events, such as flood barriers and storm surge protection.
Liquidity: Why “Water” is the Ultimate Market Metaphor
In finance, the term “liquidity” refers to how easily an asset can be converted into cash without affecting its market price. The metaphor of water is pervasive here; a “liquid” market flows smoothly, while an “illiquid” market is frozen. When discussing what type of bonds are in water, we must address how these assets contribute to or suffer from market liquidity.
Cash Equivalents and Short-Term Water Paper
Highly liquid water-related assets often include short-term municipal notes. These are “water bonds” with very short maturities (less than a year) that institutions use to park cash. Because they are backed by essential services (everyone needs water, so the bills get paid), they are considered nearly as liquid as cash itself.
The Liquidity Premium in Fixed Income
Some niche water bonds, particularly those from smaller municipalities or specialized “Blue Bond” issuers, can be relatively illiquid. This means they don’t trade often. Investors in these bonds usually demand a “liquidity premium”—a higher interest rate—to compensate them for the fact that they might not be able to sell the bond quickly in a crisis.
Diversification through Water ETFs
For the individual investor, buying a single “water bond” can be difficult and expensive. Instead, many turn to Water Exchange-Traded Funds (ETFs). While these often hold stocks in water companies rather than the bonds themselves, some fixed-income ETFs specifically target the “bonds in water” sector, providing the liquidity of a stock with the stability of a bond.
Building a Resilient Portfolio with Water-Related Assets
Integrating water-related bonds into a broader financial strategy requires a balance between the search for yield and the desire for stability. As an asset class, water is unique because it is both a defensive utility and a growth-oriented infrastructure play.
Long-Term Wealth Preservation
Institutional investors, such as pension funds and insurance companies, favor water bonds because they match their long-term liabilities. Water infrastructure lasts for decades, and the bonds that fund them often have maturities of 20 to 30 years. This makes them excellent tools for wealth preservation, offering a steady, inflation-protected stream of income (especially if the bonds have built-in rate escalators).
The “Inflation Hedge” Potential
Unlike some fixed-income assets that lose value when inflation rises, water bonds can be remarkably resilient. Because water utilities are essential, they often have the power to pass inflation-linked cost increases directly to the consumer. This creates a “bond” that is, in many ways, “inflation-proof,” provided the regulatory environment remains supportive.

Conclusion: The Flow of Capital
When we ask “what type of bonds are in water,” we find a complex ecosystem of municipal debt, ESG-driven blue bonds, and high-liquidity financial instruments. These bonds are the invisible pipes of the financial world, moving capital from those who have it to the projects that sustain our society.
For the professional investor, the “bonds in water” represent more than just a return on investment; they represent a stake in the most vital resource on the planet. By understanding the nuances of municipal revenue, the risks of climate change, and the growing importance of blue finance, investors can build a portfolio that is as resilient and essential as water itself. Whether you are looking for the tax-free advantages of municipal paper or the impact-heavy profile of a Blue Bond, the water sector remains one of the most stable and significant areas of the fixed-income market.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.