
At first glance, the question “how do you make a whole number into a fraction” might seem like a relic from elementary school mathematics. A fundamental concept, undoubtedly, but what relevance does it hold for sophisticated financial planning, investment strategies, or even daily personal finance management? The answer is profound: this seemingly simple conversion is a cornerstone of financial literacy, a foundational skill that unlocks a deeper, more precise understanding of your money, assets, and liabilities.
In the world of finance, where percentages, ratios, and proportional allocations reign supreme, the ability to effortlessly translate whole numbers into their fractional equivalents is not merely academic—it’s empowering. It allows you to dissect complex financial data, make informed decisions about budgeting, investment diversification, debt management, and wealth accumulation. This article delves into the mechanism of converting whole numbers into fractions and, more importantly, illuminates why this foundational mathematical skill is indispensable for anyone seeking robust financial acumen.

The Foundational Concept: Whole Numbers as Fractions with a Denominator of One
Before we explore the vast financial applications, let’s briefly revisit the core mathematical principle. A fraction represents a part of a whole. It consists of a numerator (the top number) and a denominator (the bottom number). The denominator tells you how many equal parts the whole is divided into, and the numerator tells you how many of those parts you have.
Understanding the “Why”: Bridging Integers and Ratios
A whole number, by its very nature, represents a complete, undivided unit or a collection of such units. For example, if you have $5, it means you have five full dollars. The magic of converting a whole number into a fraction lies in recognizing that any whole number can be expressed as itself divided by one. This seemingly trivial step is immensely powerful because it immediately casts the whole number into a relational context, ready to interact with other fractions, percentages, and ratios that are so prevalent in financial calculations.
The “why” is about standardization and operational compatibility. When you’re dealing with a mix of whole numbers and fractions in financial calculations (e.g., determining what fraction of your income goes to savings, or calculating an interest rate fraction of your principal), you need a common format. Expressing a whole number as a fraction with a denominator of one provides this universal language. It maintains the original value while preparing it for proportional analysis.
Practical Demonstration: Simple Conversion for Financial Context
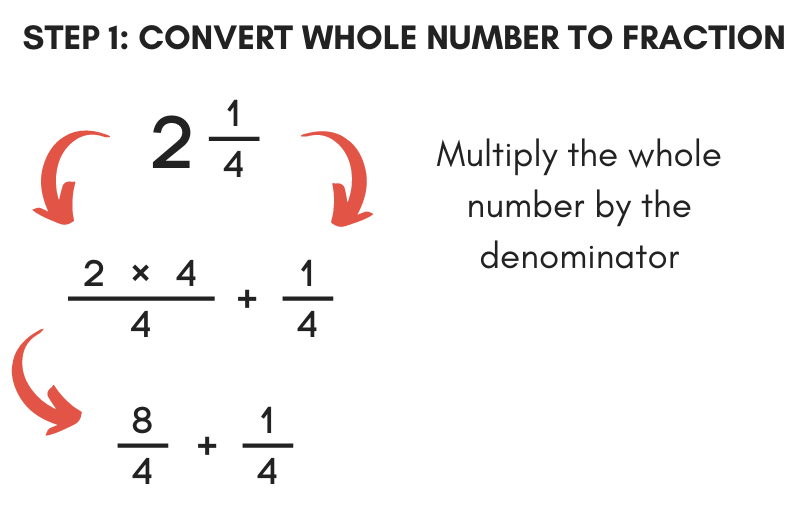
The process is remarkably straightforward: to convert any whole number into a fraction, simply place the whole number over the number 1.
Formula: Whole Number = Whole Number / 1
Examples:
-
If you have $100, it can be written as 100/1.
-
If your asset total is $50,000, it’s 50,000/1.
-
If you’re tracking 3 investment properties, this is 3/1.
While this operation doesn’t change the value of the number, it fundamentally changes its utility within a financial context. It re-frames a discrete quantity into a ready-to-be-divided, ratio-ready component, essential for operations that involve proportions, distributions, and comparisons. This simple re-framing is the gateway to more sophisticated financial analysis.
Applications in Personal Finance: Deconstructing Your Financial World
The utility of converting whole numbers into fractions becomes evident across various facets of personal finance, transforming raw numerical data into actionable insights.
Budgeting and Expense Allocation: Dividing Your Income Pie
Effective budgeting is fundamentally about allocating portions of your income to different categories. While many people think in percentages, percentages are, at their core, fractions with a denominator of 100.
Imagine your monthly take-home pay is $4,000. This is your whole number, $4,000/1. If you allocate $1,000 for rent, $500 for groceries, and $500 for savings, understanding these as fractions of your total income provides a clearer picture:
-
Rent: $1,000 / $4,000 = 1/4 of your income
-
Groceries: $500 / $4,000 = 1/8 of your income
-
Savings: $500 / $4,000 = 1/8 of your income
By converting your total income (a whole number) into a fractional denominator, you can easily express any expense or saving as a relative portion, allowing for precise adjustments and a balanced financial plan. This method helps you visualize exactly what “slice” each category takes from your overall “income pie.”
Investment Portfolios: Understanding Asset Allocation and Diversification
In investing, asset allocation is paramount for managing risk and maximizing returns. Investors typically divide their total investment capital across various asset classes like stocks, bonds, real estate, and commodities.
Suppose you have a total investment portfolio of $100,000. This is your whole number, $100,000/1. You decide to allocate:
-
$60,000 to stocks
-
$30,000 to bonds
-
$10,000 to a high-yield savings account
Expressed as fractions of your total portfolio:
-
Stocks: $60,000 / $100,000 = 6/10 or 3/5 of your portfolio
-
Bonds: $30,000 / $100,000 = 3/10 of your portfolio
-
Savings: $10,000 / $100,000 = 1/10 of your portfolio
This fractional breakdown allows you to monitor diversification levels, rebalance your portfolio as values change, and ensure your asset mix aligns with your risk tolerance and financial goals. Without understanding whole numbers as components of a larger fraction, it would be challenging to accurately gauge your portfolio’s true composition.
Debt Management and Loan Payments: Slicing Your Liabilities
Managing debt effectively often involves breaking down large sums into manageable parts and understanding payment structures. When you take out a loan, the principal amount is a whole number. Your monthly payment, however, is often split between principal and interest.
Imagine a mortgage payment of $1,500. While the payment is a whole number, a portion of it goes towards the principal balance, and another portion covers interest. If $500 goes to principal and $1,000 to interest (especially early in the loan term), you can see the fractional breakdown:
-
Principal portion: $500 / $1,500 = 1/3 of the payment
-
Interest portion: $1,000 / $1,500 = 2/3 of the payment
Understanding these fractions helps you grasp how quickly you are paying down the actual debt versus simply covering the cost of borrowing. This insight is crucial for making decisions about extra payments or refinancing.
Investing and Wealth Building: Advanced Fractional Insights
The application of converting whole numbers to fractions extends to more advanced investment strategies and wealth-building scenarios, providing critical clarity in complex financial instruments.
Share Ownership and Stock Splits: The Anatomy of Equity
When you own shares in a company, the number of shares you hold is a whole number (e.g., 100 shares of XYZ Corp). However, your ownership represents a fraction of the entire company. If XYZ Corp has 1,000,000 outstanding shares, your 100 shares represent 100/1,000,000 or 1/10,000 of the company.
Stock splits, a common corporate action, dramatically illustrate this. A 2-for-1 stock split means that for every one share you owned, you now own two. Your number of shares (a whole number) doubles, but your fractional ownership of the company remains the same. If you owned 100/1,000,000 of the company, after a 2-for-1 split, you now own 200/2,000,000, which simplifies back to 1/10,000. This understanding is key to not misinterpreting the impact of a split on your overall investment.
Interest Rates and Returns: Fractions of Your Principal
Interest rates are almost universally expressed as percentages (e.g., 5%). As mentioned, percentages are just fractions out of 100 (5% = 5/100 or 1/20). When calculating interest earned on savings or paid on a loan, you’re essentially applying this fraction to your principal (a whole number).
If you have $1,000 in a savings account with a 2% annual interest rate, you’re calculating 2/100 of $1,000. By converting $1,000 to 1000/1, you can easily perform the multiplication: (2/100) * (1000/1) = $20. Understanding this fractional relationship is fundamental to grasping concepts like compound interest, annual percentage yield (APY), and calculating your actual return on investment (ROI). It helps you see how a “small” percentage can translate into significant gains or costs over time.
Real Estate and Fractional Ownership: Dividing Tangible Assets
In some real estate ventures or through instruments like Real Estate Investment Trusts (REITs), individuals can hold “fractional ownership” in properties. Here, your investment might represent a literal fraction of a larger asset. Even without direct fractional ownership, understanding a property’s value as a whole number (e.g., a $500,000 house) and then calculating how much of that value is covered by your down payment (e.g., $100,000 or 1/5 of the value) or how much is financed by a mortgage, requires this core fractional thinking. It’s about seeing your individual contribution or share as a piece of the entire asset’s value.
Beyond Calculation: The Strategic Advantage of Fractional Thinking
The ability to convert whole numbers to fractions, and to think fractionally, offers more than just calculation ease; it bestows a strategic advantage in navigating the complexities of the financial world.
Enhancing Financial Literacy: From Numbers to Narrative
True financial literacy isn’t just about knowing what numbers are; it’s about understanding what they mean in relation to each other. By routinely converting whole numbers to fractions, you train your mind to think proportionally. Instead of just seeing “$500 debt payment,” you see “1/10 of my monthly income going to debt.” This shift in perspective provides a richer narrative to your financial data, helping you to truly grasp the impact of each financial decision on your overall well-being. It moves you from merely crunching numbers to truly comprehending your financial situation.
Empowering Negotiation and Comparison: The Fractional Edge
Whether you’re comparing loan offers, evaluating investment opportunities, or negotiating a salary, the ability to rapidly convert whole numbers into a fractional context provides a significant edge. A small percentage difference in an interest rate might seem insignificant as a whole number, but when you realize it represents an extra 1/200th of your principal over the loan term, its cumulative impact becomes much clearer. This precision allows for more effective comparisons and stronger negotiating positions, as you can articulate the exact proportional implications of different terms.

Conclusion
The humble act of converting a whole number into a fraction, a concept we often learn in our formative years, blossoms into an indispensable skill for comprehensive financial literacy. It’s not about performing complex mathematical gymnastics but about developing a fundamental framework for understanding proportionality in the monetary sphere. From meticulously crafting a budget and strategically diversifying investments to deciphering the nuances of debt and equity, thinking fractionally empowers you to move beyond surface-level numbers.
By mastering how to make a whole number into a fraction, you equip yourself with the analytical precision necessary to dissect financial statements, evaluate risks, optimize returns, and ultimately make more informed, confident, and strategic decisions that pave the way for sustained financial growth and security. In a world saturated with financial data, the ability to see the “whole” in terms of its “parts” is truly priceless.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.