
The dream of financial independence often feels distant, an elusive goal for a select few. Yet, one of the most powerful forces in finance, compound interest, offers an accessible path to accelerating wealth accumulation. While most people understand the concept of earning interest on interest, the profound impact of daily compounding is often underestimated. This article delves into the mechanics of daily compounding, exploring various avenues to harness its power and outlining strategies to integrate it into your personal financial journey, transforming modest savings into substantial wealth over time.
Understanding the Power of Daily Compounding
At its core, compound interest is interest earned on both the initial principal and the accumulated interest from previous periods. It’s often referred to as “interest on interest” and is widely considered the eighth wonder of the world by financial gurus. When this compounding happens daily, its effect becomes significantly more potent, creating a continuous feedback loop of growth that can dramatically amplify your returns.

What is Compound Interest?
Imagine you deposit $1,000 into an account with a 5% annual interest rate. After one year, you’d earn $50, bringing your total to $1,050. In the second year, instead of just earning 5% on the original $1,000, you earn 5% on $1,050, resulting in $52.50 interest for that year. This seemingly small difference quickly compounds over decades, leading to exponential growth. Compound interest allows your money to work harder for you, growing not just linearly, but geometrically. It’s a fundamental principle behind long-term investing and retirement planning.
The Exponential Advantage of Daily Compounding
While annual or even monthly compounding is beneficial, daily compounding takes this advantage to another level. With daily compounding, the interest earned each day is immediately added to your principal, meaning that the very next day, you’re earning interest on a slightly larger sum. This continuous cycle means that your principal grows incrementally every single day, leading to a higher effective annual yield than an account that compounds less frequently, even if the stated annual interest rate is the same. Over a 30-year period, the difference between daily and annual compounding on a substantial sum can amount to tens of thousands, if not hundreds of thousands, of dollars. It’s a subtle but significant factor in maximizing returns, especially for long-term investments.
The Time Value of Money in Action
Daily compounding is a vivid demonstration of the time value of money, the concept that a sum of money today is worth more than the same sum will be at a future date due to its potential earning capacity. By compounding daily, you are essentially accelerating the earning capacity of your money. The longer your money is subject to daily compounding, the greater the impact, as the interest has more opportunities to earn interest itself. This principle underscores the importance of starting to save and invest early, even with small amounts. Each day your money sits uninvested or in a low-interest account, it’s missing out on countless opportunities to grow.
Strategies and Vehicles for Daily Compounding
Earning compound interest daily isn’t a mythical feat; it’s a tangible outcome achievable through various financial products and investment strategies. The key is to identify vehicles that explicitly offer daily interest accrual and compounding.
High-Yield Savings Accounts (HYSAs)
Many modern high-yield savings accounts advertise daily interest accrual, even if the interest is paid out monthly. These accounts typically offer significantly higher interest rates than traditional savings accounts, making them an excellent starting point for those looking to benefit from daily compounding without taking on significant risk. While their rates fluctuate with market conditions, HYSAs provide liquidity and security, often being FDIC-insured up to statutory limits, making them suitable for emergency funds and short-term savings goals.
Money Market Accounts
Similar to HYSAs, money market accounts (MMAs) often offer competitive interest rates and typically compound interest daily. They bridge the gap between savings and checking accounts, often providing check-writing privileges or debit card access, along with higher interest rates. MMAs are also typically FDIC-insured and are suitable for funds you might need occasional access to, while still benefiting from consistent growth.
Certificate of Deposits (CDs) with Daily Compounding
While many CDs have interest paid out at maturity or periodically, some specialized CDs offer daily compounding. These require you to lock up your money for a specific term (e.g., 6 months, 1 year, 5 years) in exchange for a fixed interest rate, which can be higher than savings accounts. If you find a CD that compounds daily, it can be a secure way to grow a specific sum over a defined period, especially if you don’t need immediate access to the funds. Laddering CDs, where you invest in several CDs with staggered maturity dates, can help maintain liquidity while still benefiting from higher rates.
Brokerage Accounts and Reinvesting Dividends/Interest
For those comfortable with a higher level of risk, investing in stocks, ETFs, or mutual funds within a brokerage account can also facilitate daily compounding. Many growth stocks, for example, might increase in value daily, effectively compounding your principal. More directly, dividend-paying stocks and interest-bearing bonds can be set up to automatically reinvest their payouts. While dividends are usually paid quarterly, and bond interest semi-annually, reinvesting them immediately means those new shares or bond units start earning their own dividends/interest, accelerating your total returns over time. This strategy leans into market growth as a form of compounding.
Peer-to-Peer Lending Platforms
Peer-to-peer (P2P) lending platforms allow individuals to lend money directly to other individuals or small businesses, bypassing traditional financial institutions. Lenders earn interest on these loans, and many platforms allow for interest payments to be compounded and reinvested into new loans or portions of loans. While this can offer potentially higher returns than traditional savings, it comes with increased risk, including borrower default. Diligent research into the platform’s history, loan performance, and risk management practices is crucial.
Crypto Savings and Staking Platforms (with caution)
The burgeoning world of cryptocurrency offers platforms that allow users to earn interest on their digital assets through various mechanisms, including crypto savings accounts or staking. Some of these platforms offer daily or even hourly compounding. While the potential yields can be very high, this sector carries significant risks, including extreme volatility, lack of regulatory oversight, and potential platform vulnerabilities. It is imperative to approach these options with a thorough understanding of the underlying technology, market dynamics, and associated risks, and only allocate a small, acceptable portion of your portfolio if you choose to explore them.
Maximizing Your Daily Compounding Potential
Simply choosing an account that compounds daily isn’t enough; actively managing and optimizing your approach can dramatically enhance its effect. Maximizing the power of daily compounding involves strategic planning and consistent execution.
Start Early and Be Consistent
The single most impactful factor in harnessing compound interest, especially daily compounding, is time. The earlier you begin investing, the longer your money has to grow and compound. Even small, consistent contributions made over a long period can outperform larger, sporadic contributions made later in life. Automate your savings and investments to ensure regularity, making contributions a non-negotiable part of your financial routine. Consistency builds momentum, allowing daily compounding to work its magic uninterrupted.
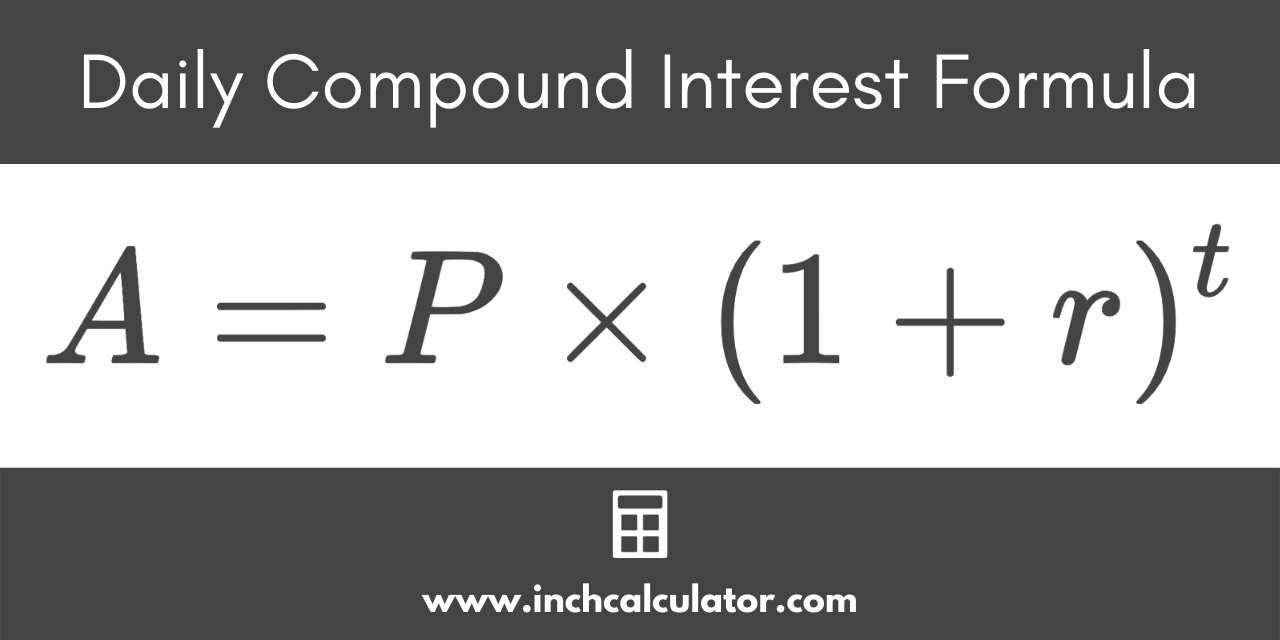
Prioritize Increasing Your Principal
The principal is the foundation upon which compound interest is built. The larger your initial and subsequent contributions to your compounding accounts, the greater the absolute amount of interest you will earn each day. Look for opportunities to increase your contributions whenever possible – whether it’s through a bonus, a raise, or by cutting discretionary spending. Every additional dollar added to your principal today means that dollar starts earning daily interest immediately, significantly accelerating your wealth accumulation over the long run.
Minimize Fees and Taxes
Fees, no matter how small, eat into your returns and reduce the amount available for compounding. Be vigilant about account maintenance fees, transaction fees, and management fees, especially in brokerage or P2P platforms. Similarly, taxes can diminish your gains. Explore tax-advantaged accounts like IRAs or 401(k)s, where your investments can grow tax-deferred or tax-free, allowing more of your earnings to compound daily without immediate tax implications. Understanding the tax efficiency of your investment vehicles is a critical component of maximizing your net compounded returns.
Automate Your Investments
Set up automated transfers from your checking account to your high-yield savings, investment, or crypto staking accounts. Whether it’s weekly, bi-weekly, or monthly, automation ensures that your money is consistently flowing into your compounding vehicles without requiring conscious effort. This strategy removes the temptation to spend money that could otherwise be working for you, guaranteeing that your principal continues to grow, and daily compounding is consistently applied to an ever-increasing base.
Risks and Considerations for Daily Compounding
While highly advantageous, daily compounding strategies are not without their inherent risks and considerations. A comprehensive understanding of these factors is crucial for making informed financial decisions and protecting your assets.
Inflation Erosion
Perhaps the most pervasive risk is inflation. If the annual interest rate you’re earning through daily compounding is lower than the rate of inflation, your purchasing power is actually diminishing, even if your nominal account balance is growing. It’s essential to seek out returns that outpace inflation to ensure your wealth truly grows in real terms. This often means considering investments with higher potential yields, which typically come with increased risk.
Market Volatility (for certain investments)
For investments tied to market performance, such as stocks, ETFs, or certain P2P lending options, daily compounding of capital gains or reinvested dividends is subject to market volatility. While your shares may technically compound daily in terms of value, that value can also decrease significantly in a downturn. This risk is less relevant for FDIC-insured savings products but becomes a major factor in higher-risk, higher-reward strategies. Diversification is key to mitigating this risk.
Platform Risks and Regulatory Scrutiny
When venturing into newer financial territories like certain crypto platforms or even some lesser-known P2P lenders, platform risk is a significant concern. This includes the risk of the platform itself failing, security breaches, or regulatory changes that could impact your investments. Unlike traditional banks, many of these platforms may not offer the same level of consumer protection (e.g., FDIC insurance). Always research the platform’s security measures, reputation, and regulatory compliance before committing funds.
Understanding Terms and Conditions
Always read the fine print. The stated interest rate might come with specific conditions, withdrawal limits, or fees that could negate some of the benefits of daily compounding. For instance, some HYSAs might only offer the highest rates on balances above a certain threshold, or specific CDs might penalize early withdrawals. Understanding the exact terms, including how and when interest is calculated and paid, is vital to avoid unwelcome surprises.
Calculating and Monitoring Your Daily Compound Growth
To truly appreciate and manage the impact of daily compounding, it’s beneficial to understand how it’s calculated and to regularly monitor its progress. This allows you to track your wealth accumulation and make adjustments to your strategy as needed.
The Compound Interest Formula Explained
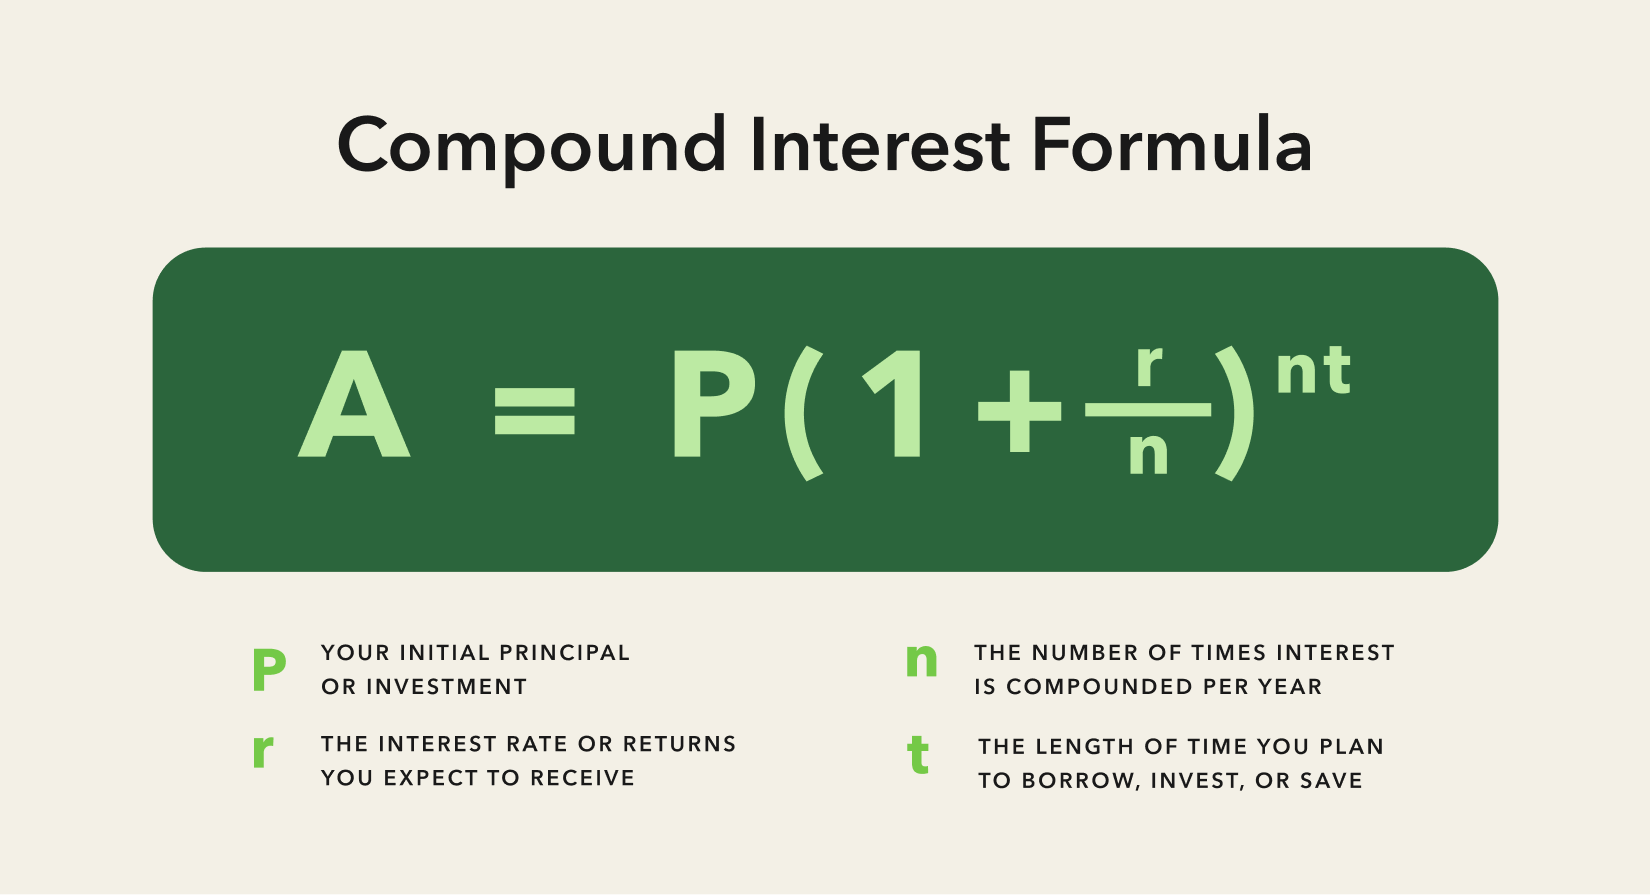
The general formula for compound interest is:
A = P (1 + r/n)^(nt)
Where:
-
A = the future value of the investment/loan, including interest
-
P = the principal investment amount (the initial deposit or loan amount)
-
r = the annual interest rate (as a decimal)
-
n = the number of times that interest is compounded per year (for daily compounding, n = 365)
-
t = the number of years the money is invested or borrowed for
By plugging in ‘365’ for ‘n’, you can calculate the precise future value of your daily compounded investment. This formula clearly illustrates the exponential effect of compounding over time, especially when ‘n’ is a large number.
Utilizing Online Calculators and Financial Apps
Fortunately, you don’t need to manually crunch these numbers. Numerous free online compound interest calculators are available. These tools allow you to input your principal, interest rate, compounding frequency (daily), and investment horizon to instantly see projected growth. Many personal finance apps also incorporate similar calculators and allow you to link your accounts to track your actual interest earnings and overall portfolio growth in real-time. These tools are invaluable for visualizing the long-term impact of your daily compounding strategy and for setting realistic financial goals.
Regular Review and Adjustment of Your Strategy
The financial landscape is constantly evolving. Interest rates change, new investment opportunities emerge, and your personal financial goals may shift. Regularly review your compounding strategy, at least annually. Assess whether your current vehicles are still offering competitive rates, if there are better alternatives available, or if you need to adjust your contribution amounts. This proactive approach ensures that your daily compounding strategy remains optimized for your objectives and continues to work as efficiently as possible towards your financial independence.
Conclusion
Earning compound interest daily is not a secret reserved for financial elite; it is a powerful, accessible mechanism that can dramatically accelerate your journey towards financial security and wealth accumulation. By understanding its fundamental principles, selecting the right financial vehicles, maximizing your contributions, and diligently monitoring your progress, you can harness this exponential force. While patience and consistency are paramount, the long-term rewards of daily compounding are undeniable, offering a profound testament to the quiet power of consistent growth. Start today, and watch your money truly work for you, day in and day out.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.