
Starting a new business is often framed as a journey of passion and creativity, but at its core, it is a rigorous exercise in financial engineering. To transition from an initial concept to a profitable enterprise, an entrepreneur must navigate the complexities of capital allocation, revenue modeling, and fiscal sustainability. Success is rarely the result of luck; it is the byproduct of disciplined financial planning and a deep understanding of how money moves through a commercial structure.
Laying the Financial Foundation: Capital and Cost Analysis
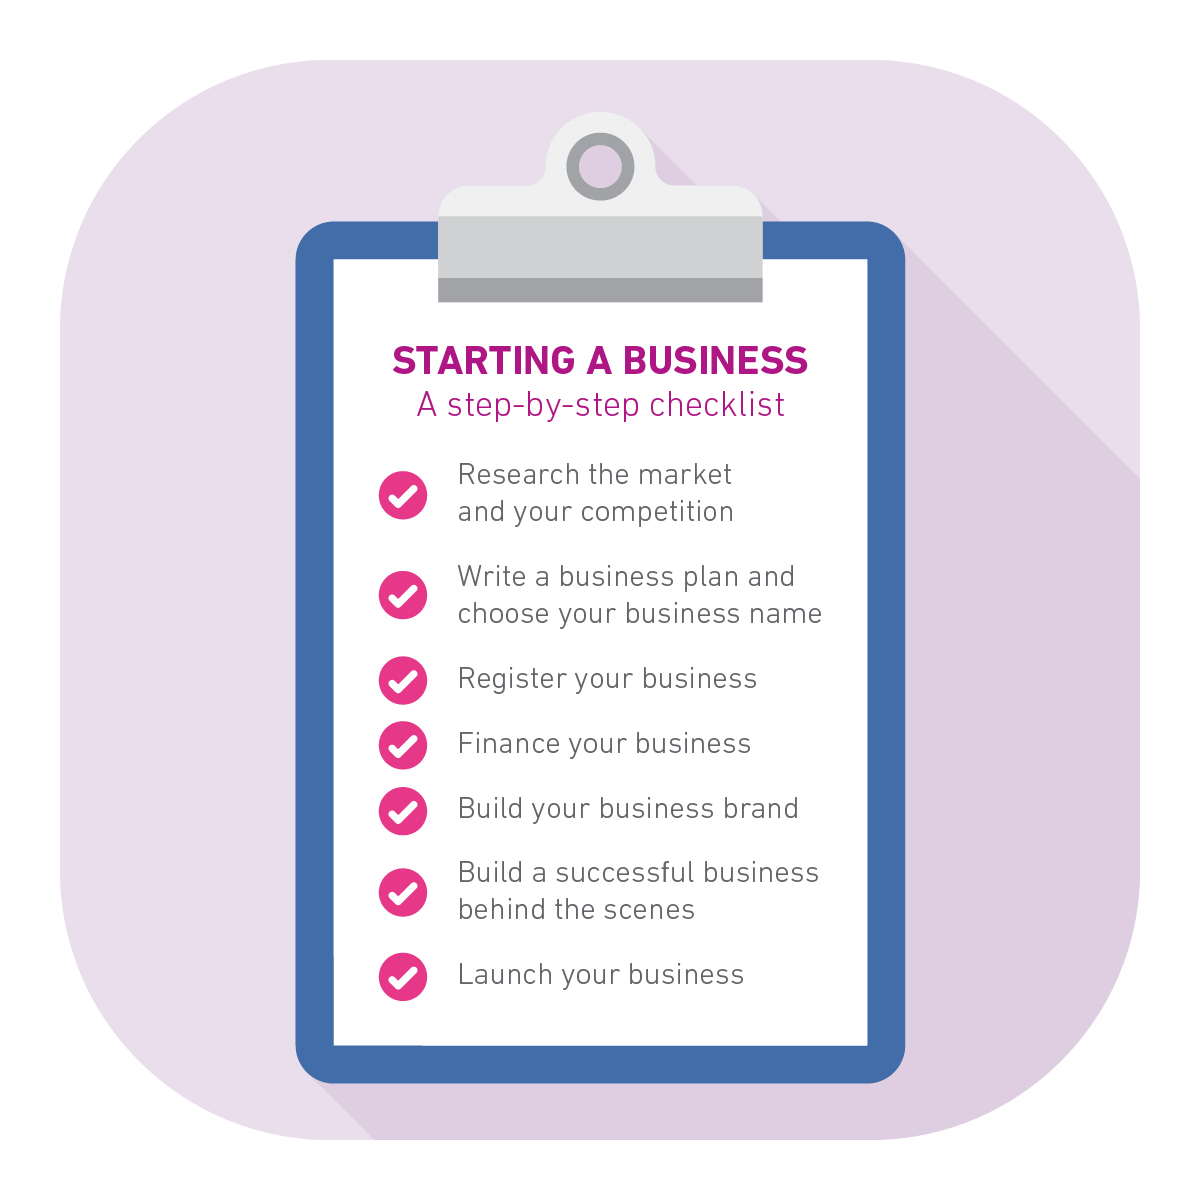
The first hurdle for any aspiring business owner is the objective assessment of the required “fuel” to get the venture off the ground. This involves a granular breakdown of startup costs, distinguishing between essential capital expenditures (CapEx) and ongoing operating expenses (OpEx). Without a clear picture of these figures, a business risks insolvency before it even reaches its first customer.
Identifying Initial Capital Requirements
Before launching, you must conduct a comprehensive audit of every dollar required to reach “Day One.” This includes one-time costs such as legal fees for incorporation, licensing and permits, initial inventory, equipment, and office or retail space deposits. Many entrepreneurs fail because they underestimate these “sunk costs,” failing to account for the buffer needed to survive the initial months when revenue is typically non-existent or inconsistent.
A professional approach involves creating a pro-forma balance sheet that estimates these costs alongside a “runway” calculation. Your runway is the amount of time your business can survive if it generates zero revenue. For most service-based or digital businesses, a six-month runway is the minimum recommendation, while capital-intensive industries like manufacturing may require much longer leads.
The Role of Bootstrapping vs. External Funding
Deciding how to fund your business is a strategic choice that dictates your level of control and your long-term profit margins. Bootstrapping—funding the business through personal savings and early sales—is the most fiscally conservative route. It forces lean operations and ensures the founder retains 100% equity, but it can limit the speed of growth.
Conversely, seeking external capital through debt (loans) or equity (investors) can accelerate market entry. Debt financing, such as SBA loans or lines of credit, allows you to keep ownership but introduces the pressure of monthly interest payments, which can strain cash flow. Equity financing, such as angel investment or venture capital, provides a cash infusion without the burden of repayment, but it requires surrendering a portion of future profits and decision-making power. Choosing the right mix depends on your industry’s scalability and your personal risk tolerance.
Revenue Models and Profitability Forecasting
Once the capital is secured, the focus must shift to the engine of the business: the revenue model. A business is not truly a business until it has a repeatable, scalable way to generate more money than it spends. This requires a shift from “selling” to “financial modeling.”
Establishing Sustainable Pricing Strategies
Pricing is one of the most powerful levers in business finance. Set it too low, and you may achieve high volume but fail to cover your overhead. Set it too high, and you risk low market penetration. To find the “sweet spot,” you must understand your Unit Economics—the direct revenues and costs associated with a single unit of your product or service.
The primary goal is to ensure a healthy Gross Margin. This is the percentage of revenue that exceeds the Cost of Goods Sold (COGS). For a software business, gross margins might be as high as 80-90%, whereas a grocery store might operate on 2-5%. Understanding your industry benchmark is vital. If your margins are too slim, your business will be fragile, unable to absorb unexpected costs or market fluctuations.
Calculating the Break-Even Point
The break-even point is the psychological and financial milestone where total revenue equals total expenses. Reaching this point means the business is no longer “burning” cash and is technically self-sustaining. To calculate this, you must divide your total fixed costs (rent, salaries, utilities) by your contribution margin (the price of the product minus the variable cost to produce it).
Forecasting your break-even point allows you to set clear sales targets. It transforms an abstract goal into a concrete financial objective. If your break-even analysis reveals that you need to sell 10,000 units a month to survive, but your market research shows a maximum capacity of 2,000, you know immediately that your business model is flawed and requires adjustment before you invest significant capital.
Navigating Business Finance and Tax Efficiency
As the business begins to generate income, the complexity of managing those funds increases. Financial management is not merely about accounting; it is about protecting assets and optimizing the amount of profit that actually stays in the business.
Structuring for Financial Protection
The legal structure of your business has profound implications for your personal finances and tax obligations. For many new business owners, moving beyond a sole proprietorship to a Limited Liability Company (LLC) or a Corporation is a critical step in risk management. These structures create a “corporate veil” that separates personal assets from business liabilities.
From a tax perspective, the choice of entity (such as an S-Corp election for an LLC) can significantly reduce self-employment taxes. By paying yourself a “reasonable salary” and taking the remaining profits as distributions, you can optimize your tax liability, leaving more capital available for reinvestment.
Tax Planning as a Growth Strategy
Taxation should be viewed as a controllable expense rather than an inevitable burden. Sophisticated entrepreneurs utilize strategic tax planning to improve their bottom line. This includes maximizing deductible expenses, such as home office deductions, equipment depreciation, and research and development credits.
Furthermore, setting aside a percentage of every dollar earned for tax obligations is a non-negotiable habit. One of the most common reasons small businesses fail is a “surprise” tax bill that wipes out their cash reserves. Implementing a “Profit First” mentality—where taxes and profits are allocated to separate accounts the moment revenue is received—ensures that the business remains compliant and liquid.
Scaling Through Strategic Reinvestment
The final stage of starting a new business is the transition from survival to growth. This requires a disciplined approach to cash flow management and a strategic vision for where to deploy excess capital.
Managing Cash Flow for Longevity
It is a common paradox in finance that a profitable business can still go bankrupt. This happens due to poor cash flow management—when the timing of money coming in doesn’t align with the timing of money going out. For instance, if you have to pay suppliers today but your customers don’t pay you for 60 days, you face a “cash gap.”
Mastering the Cash Conversion Cycle is essential for scaling. This involves negotiating better payment terms with vendors, incentivizing early payments from customers, and maintaining a “cash reserve” for emergencies. A healthy cash flow provides the “optionality” to take advantage of market opportunities, such as purchasing discounted inventory or hiring top-tier talent during a downturn.
Diversifying Income Streams
As the business matures, the focus should shift toward building financial resilience. Relying on a single product or a single client is a high-risk strategy. Starting a new business successfully means eventually evolving that business into a portfolio of income streams.
This might involve “vertical integration,” where you acquire a supplier to reduce costs, or “horizontal expansion,” where you launch complementary products for your existing customer base. Strategic reinvestment of profits into these new avenues reduces the impact of market volatility. By diversifying where your money comes from, you move from the precarious state of a “startup” to the stable foundation of a wealth-generating enterprise.

The Long-Term Wealth Perspective
Ultimately, starting a new business is one of the most effective paths to personal wealth creation, provided it is managed with financial rigor. The goal is to build an asset that has value independent of your daily labor. This means creating systems that track Every Dollar In (EDI) and Every Dollar Out (EDO) with precision.
By focusing on high margins, maintaining a lean cost structure, and aggressively managing cash flow, you transform a business idea into a financial engine. The successful entrepreneur is, above all else, a steward of capital, ensuring that every investment made into the business yields a return that justifies the risk. In the world of business, passion may start the engine, but financial discipline is the fuel that keeps it running for the long haul.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.