
In an increasingly digital world, understanding the mechanisms that underpin our financial transactions is more crucial than ever. Among these, Automated Clearing House (ACH) transactions stand out as a silent workhorse, facilitating billions of payments and transfers daily. For members of Navy Federal Credit Union, grasping “what is ACH credit Navy Federal” is fundamental to navigating their personal finances, managing income, and understanding how funds move in and out of their accounts. This article delves into the intricacies of ACH credits, specifically within the robust ecosystem of Navy Federal, providing a professional, insightful, and engaging exploration for anyone keen to master their financial dealings.

Demystifying ACH: The Digital Pulse of Your Money
At its core, ACH refers to an electronic network for financial transactions in the United States. Managed by Nacha (National Automated Clearing House Association), this network allows for high-volume, low-cost electronic funds transfers between bank accounts. Unlike wire transfers, which are often immediate and costlier, ACH transactions are typically processed in batches and are significantly more economical, making them ideal for recurring payments and large-scale disbursements.
Understanding ACH: Beyond Just “Electronic Transfers”
When we talk about ACH, it’s important to distinguish between ACH credits and ACH debits.
-
ACH Credits: These are transactions where money is “pushed” into your account. Think of direct deposits from your employer, government benefits (like Social Security), refunds from merchants, or payments received from a friend via a payment app that uses ACH to deposit funds. The originator of the payment initiates the transaction to send money to your account.
-
ACH Debits: These are transactions where money is “pulled” from your account. Common examples include automatic bill payments for utilities, mortgage payments, insurance premiums, or subscription services. Here, you’ve typically authorized a third party to withdraw funds from your account.
For Navy Federal members, understanding ACH credits means recognizing the primary channel through which their regular income and various incoming payments arrive. It’s the system that ensures your paycheck lands in your account on time, every time, without the need for physical checks.
How ACH Credits Differ from Other Payment Methods
The landscape of digital payments is diverse, with options ranging from credit card payments to wire transfers and peer-to-peer apps. ACH credits carve out a specific niche due to their unique characteristics:
-
Compared to Wire Transfers: Wire transfers are typically real-time, irreversible, and more expensive. They are often used for large, urgent, or international transfers. ACH credits, on the other hand, are batch processed, less expensive, and have a more defined dispute resolution process, making them suitable for everyday transactions.
-
Compared to Credit Card Transactions: Credit card payments involve card networks (Visa, MasterCard, etc.) and typically incur higher transaction fees, often borne by the merchant. They also offer consumer protections like chargebacks. ACH payments bypass these card networks, operating directly between bank accounts, which can be more cost-effective for businesses and consumers alike for certain types of payments.
-
Compared to Physical Checks: ACH credits are the digital evolution of checks. They eliminate the need for paper, postage, and manual processing, drastically reducing processing times and the risk of fraud associated with physical checks.
The efficiency and cost-effectiveness of ACH credits make them a preferred method for many types of financial transfers, especially those that are recurring or high-volume.
The Role of Nacha and the ACH Network
Nacha plays a pivotal role as the steward of the ACH Network, developing rules and standards that govern the movement of money. This ensures consistency, security, and interoperability across the thousands of financial institutions, including Navy Federal Credit Union, that participate in the network. For Navy Federal members, Nacha’s oversight translates into a reliable and secure system for receiving their funds. The network’s robust framework includes rules for transaction processing, settlement, and error resolution, providing a strong foundation of trust for electronic payments.
ACH Credits in Your Navy Federal Account
For the nearly 13 million members of Navy Federal Credit Union, ACH credits are an integral part of their financial lives. The credit union leverages the ACH Network to provide seamless and secure services that cater to the diverse needs of its military and veteran community.
Receiving Funds: Direct Deposits and More
The most common and arguably most important type of ACH credit for many Navy Federal members is direct deposit. Whether it’s a paycheck from the Department of Defense, a private employer, military retirement pay, or VA benefits, direct deposit ensures these vital funds are electronically transferred into your Navy Federal checking or savings account. This method not only offers unparalleled convenience but also often provides earlier access to funds compared to traditional checks.
Beyond regular income, Navy Federal members might receive other ACH credits such as:
-
Tax Refunds: The IRS frequently uses ACH to deposit refunds directly into taxpayers’ accounts.
-
Investment Payouts: Dividends or proceeds from investment accounts can be credited via ACH.
-
Merchant Refunds: If you return an item purchased online or in-store, the refund might be issued as an ACH credit.
-
Government Benefits: Social Security, disability payments, or other government disbursements are typically sent via ACH.
-
Peer-to-Peer (P2P) Transfers: Many popular P2P payment apps like Zelle (which Navy Federal integrates) or Venmo often use the ACH network to deposit funds from your app balance into your bank account.
Making Payments: How ACH Debits Complement Credits
While this article focuses on ACH credits, it’s worth briefly mentioning ACH debits as the other side of the same coin. Navy Federal members frequently use ACH debits to automate payments for mortgages, car loans, credit card bills, and utility services. The efficiency of the ACH network allows for both incoming and outgoing electronic transfers to be managed smoothly, offering a complete digital banking experience. Together, ACH credits and debits form the backbone of automated financial management, allowing members to set it and forget it, while maintaining visibility and control through Navy Federal’s online banking and mobile app.
Common Scenarios for ACH Credits at Navy Federal
Consider these practical scenarios for ACH credits within Navy Federal:
-
New Employment: When you start a new job, your employer will typically request your Navy Federal account and routing number for direct deposit setup. This initiates a recurring ACH credit.
-
Receiving a Bonus: Many employers issue bonuses via ACH direct deposit, separate from regular payroll.
-
Selling an Item Online: If you sell goods through an online marketplace, the payout may be sent as an ACH credit to your Navy Federal account.
-
Insurance Claim Payouts: Following an approved insurance claim, the funds might be disbursed directly to your account via ACH.
-
Student Loan Refunds: If you receive a refund of excess student loan funds from your educational institution, it will often come via ACH.
Each of these scenarios underscores the pervasive and practical utility of ACH credits in the daily financial lives of Navy Federal members.
The Benefits of ACH Transactions for Navy Federal Members
The widespread adoption of ACH by Navy Federal and other financial institutions isn’t accidental. It’s driven by significant advantages that enhance efficiency, security, and cost-effectiveness for both the credit union and its members.
Speed and Efficiency in Financial Management
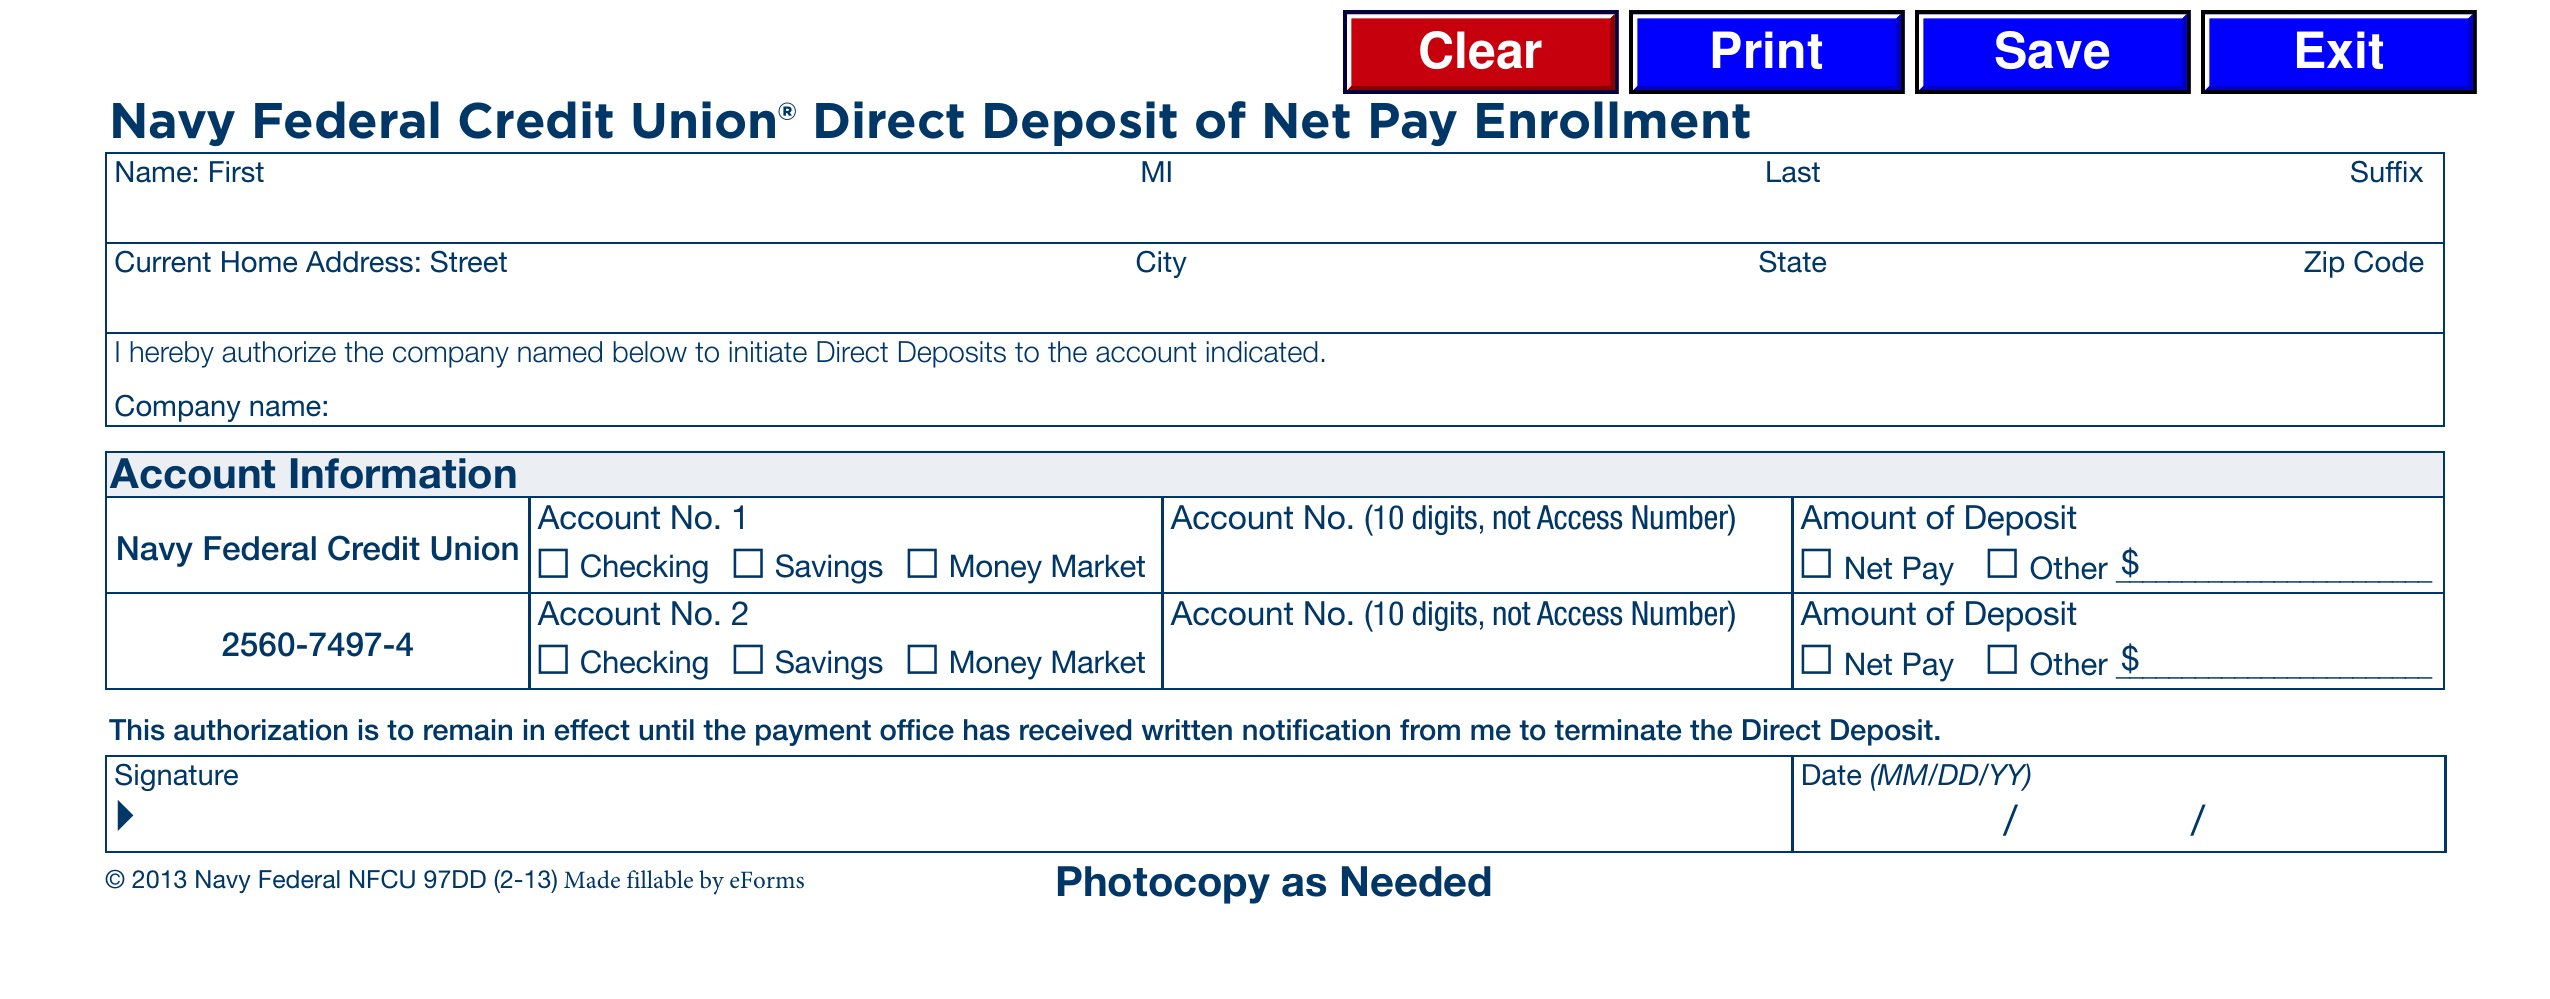
ACH credits offer a level of speed and efficiency that traditional paper-based systems cannot match. While not instantaneous like a wire transfer, same-day ACH processing has significantly reduced settlement times. This means that funds from direct deposits, refunds, or other incoming payments can often be available in your Navy Federal account on the same business day they are initiated, or within 1-2 business days for standard processing. This rapid turnaround is crucial for managing cash flow, meeting financial obligations, and avoiding late fees. For members relying on timely access to their paychecks or benefits, the efficiency of ACH is invaluable.
Enhanced Security Features
Security is paramount in financial transactions, and ACH credits are built with robust safeguards. Nacha’s operating rules mandate strict security protocols for all participating financial institutions, including Navy Federal. These measures include:
-
Data Encryption: Sensitive financial information transmitted over the ACH Network is encrypted to prevent unauthorized access.
-
Fraud Detection and Prevention: Financial institutions employ sophisticated systems to monitor for unusual activity and prevent fraudulent transactions.
-
Authorization Requirements: For ACH debits, explicit authorization from the account holder is required, although this is less relevant for credits where funds are sent to your account. However, the integrity of the sending party is also scrutinized.
-
Dispute Resolution Process: In the rare event of an error or unauthorized transaction, Nacha’s rules provide a clear framework for dispute resolution, offering protection to account holders.
Navy Federal further enhances this security through its own internal measures, providing members with peace of mind knowing their funds are handled safely.
Cost-Effectiveness Compared to Wire Transfers
One of the most compelling advantages of ACH credits is their cost-effectiveness. Wire transfers can incur fees ranging from $15 to $50 or more for domestic transactions. ACH transactions, by contrast, are typically free for the receiving party and incur very low fees for the originator (often fractions of a dollar per transaction), making them an economical choice for both businesses and individuals. This cost-efficiency allows Navy Federal to offer services like direct deposit without charging its members, maximizing the value of their income. For businesses and government agencies, the lower cost of processing ACH payments translates into significant savings, which can indirectly benefit consumers through lower product prices or more efficient service delivery.
Navigating ACH Transactions with Navy Federal: Practical Considerations
While ACH transactions are generally smooth, understanding some practical aspects can further empower Navy Federal members to manage their finances effectively.
Understanding Processing Times and Settlement Dates
It’s important to differentiate between when an ACH credit is initiated and when it settles in your account.
-
Initiation: This is when the payer (e.g., your employer) sends the payment instruction.
-
Processing: The ACH Network batches and clears these transactions.
-
Settlement: This is when the funds are officially moved between the banks and become available in your Navy Federal account.
Standard ACH processing typically takes 1-3 business days. However, with the advent of Same Day ACH, many payments can settle on the same business day if initiated within specific cutoff times. It’s crucial to remember that weekends and holidays do not count as business days, which can extend processing times. Navy Federal’s online banking and mobile app usually provide clear indications of pending deposits and when funds will be available, helping members plan accordingly.
What to Do If an ACH Credit is Delayed or Incorrect
While rare, delays or errors with ACH credits can occur. If you anticipate an ACH credit that doesn’t appear in your Navy Federal account as expected, or if the amount is incorrect:
-
Check Your Navy Federal Account Statements: Verify the transaction history through online banking or the mobile app.
-
Contact the Originator: The first step should be to contact the sender of the funds (e.g., your employer’s HR/payroll department, the company issuing the refund, or the government agency). They can verify if the payment was sent, when, and to which account number.
-
Contact Navy Federal Customer Service: If the originator confirms the payment was sent correctly and still isn’t appearing, contact Navy Federal. They can investigate the transaction using the ACH trace number provided by the originator.
It’s important to act promptly to resolve any discrepancies. Navy Federal’s dedicated customer service team is equipped to assist members with these types of inquiries.
Utilizing Navy Federal’s Digital Tools for ACH Management
Navy Federal Credit Union provides a suite of digital tools that make managing ACH credits and your overall finances effortless:
-
Online Banking: Access detailed transaction history, view pending deposits, and set up alerts for incoming funds.
-
Mobile App: Manage accounts on the go, receive push notifications for deposits, and categorize transactions.
-
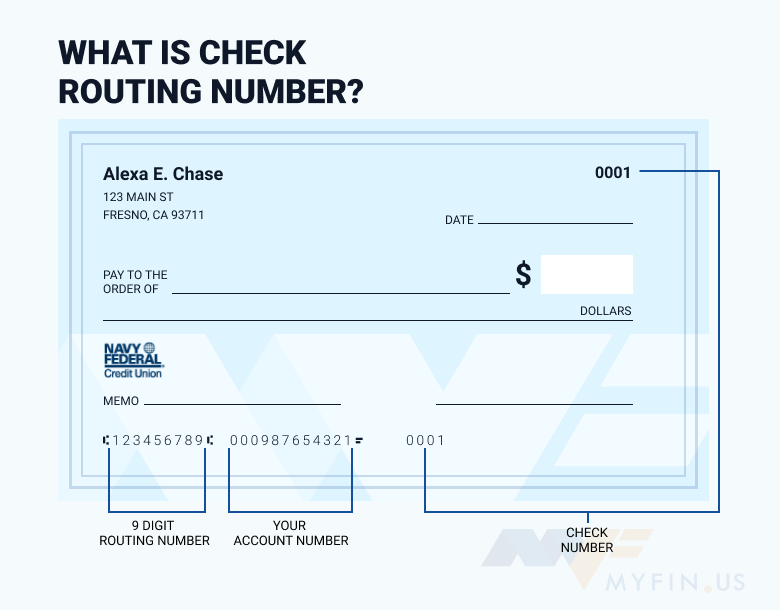
Direct Deposit Information: Easily find your account and routing number within your online banking profile to provide to employers or other payers.
-
Alerts and Notifications: Set up alerts to notify you via email or text when an ACH credit hits your account, ensuring you’re always aware of incoming funds.
These tools are designed to give Navy Federal members complete control and visibility over their money, including the timely arrival of ACH credits.
ACH Credits: A Cornerstone of Modern Personal Finance
In an economy increasingly reliant on digital transactions, ACH credits are not just a convenience; they are a fundamental component of effective personal finance management. For Navy Federal members, they represent a secure, efficient, and cost-effective method for receiving their income and other financial disbursements.
Integrating ACH into Your Financial Planning
Understanding the rhythm of your ACH credits—when your paycheck arrives, when benefits are deposited—is vital for effective financial planning. It allows you to:
-
Budgeting: Accurately forecast your income to create realistic budgets.
-
Saving: Automate savings by setting up transfers to a savings account shortly after direct deposit.
-
Debt Management: Schedule automated bill payments (ACH debits) to align with your incoming ACH credits, ensuring bills are paid on time.
-
Financial Goal Setting: Use the predictability of ACH credits to plan for larger financial goals, such as buying a home, saving for retirement, or funding education.
The Future of ACH and Digital Banking
The ACH Network continues to evolve, with ongoing enhancements like Same Day ACH demonstrating a commitment to faster, more efficient transactions. As digital banking technologies advance, Navy Federal, along with other financial institutions, will continue to integrate these improvements, offering members even greater flexibility and speed in managing their money. Innovations in payment technology will likely build upon the robust foundation laid by ACH, making electronic fund transfers even more seamless and pervasive.
Why Navy Federal Prioritizes Seamless ACH Services
Navy Federal Credit Union’s commitment to providing seamless ACH services is a testament to its mission to serve its members’ financial needs. For a community that often experiences deployments, relocations, and unique financial circumstances, reliable and efficient electronic banking is not just a feature—it’s a necessity. By ensuring that direct deposits arrive promptly and securely, and by offering robust tools to manage these transactions, Navy Federal empowers its members to focus on their service and their families, with confidence in their financial well-being.
In conclusion, an ACH credit at Navy Federal is more than just an electronic transfer; it’s the reliable flow of income, benefits, and various payments into your account, facilitated by a powerful, secure, and cost-effective digital network. Understanding its mechanics and leveraging Navy Federal’s sophisticated tools can significantly enhance your financial management and peace of mind.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.