
Navy Federal Credit Union (NFCU) stands as a pillar of financial stability for service members, veterans, and their families. As the world’s largest credit union, it offers a suite of financial products that rival major global banks, yet it retains a member-centric approach that prioritizes low fees and competitive rates. However, the true utility of any financial institution lies in the ease with which one can manage liquidity. Understanding how to fund a Navy Federal account efficiently is not merely a matter of administrative necessity; it is a fundamental component of proactive personal finance management. Whether you are transitioning your primary banking to NFCU or using it for specific investment vehicles, mastering the diverse funding channels available is essential for maintaining a seamless cash flow.
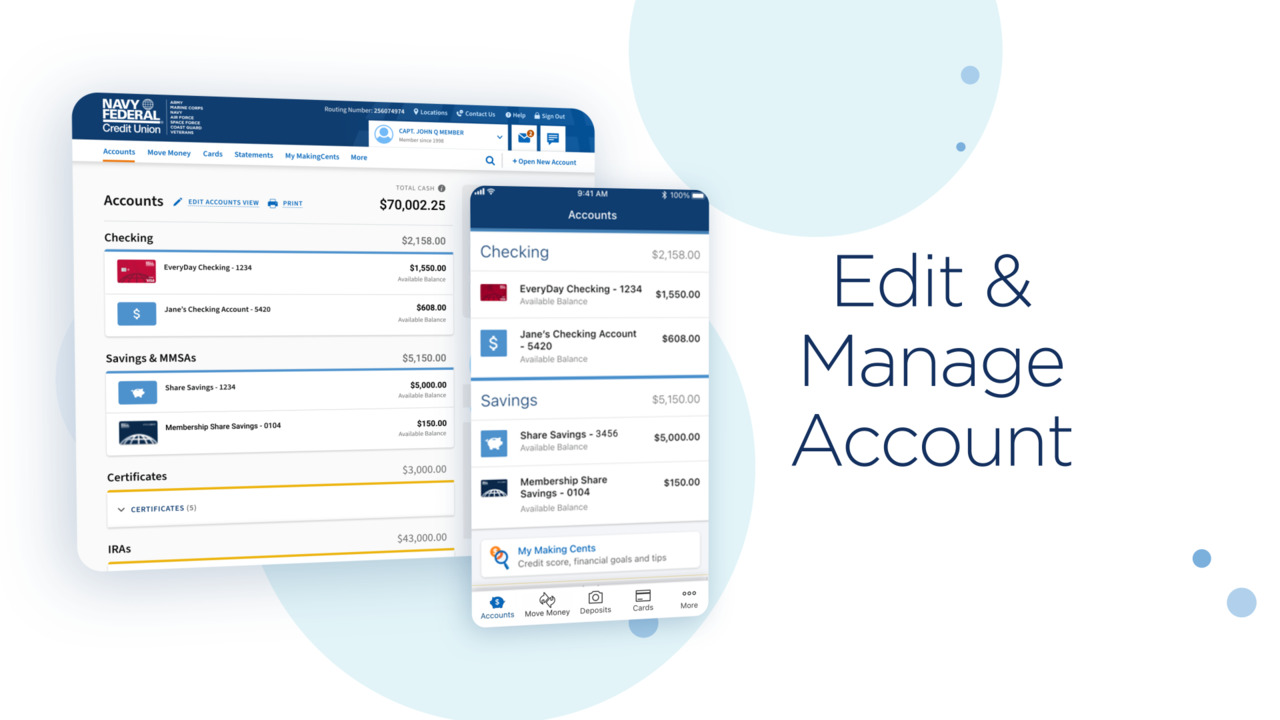
Seamless Digital Transfers and External Linking
In the modern financial ecosystem, the speed of capital movement is a primary metric of convenience. Navy Federal provides several digital avenues to move money from external banks or between internal sub-accounts, ensuring that your capital is always where it needs to be when you need it.
Leveraging the NFCU Mobile App and Online Banking
The primary gateway for most members is the Navy Federal mobile app or the online banking portal. To initiate an internal transfer—for instance, moving funds from a Flagship Checking account to a savings account or a certificate—the process is instantaneous. However, the real power of the digital platform lies in its “Move Money” feature, which allows for the orchestration of complex financial movements with a few taps.
When you first open your account, linking an external financial institution is a critical step. By navigating to the “Transfer Money” section and selecting “Add an External Account,” you can initiate the verification process. This typically involves providing the routing and account numbers of your other bank. Navy Federal utilizes secure verification methods, often involving micro-deposits or instant verification via third-party secure connectors. Once verified, you can pull funds from your external bank into your Navy Federal account. It is important to note that while NFCU does not charge for these standard ACH transfers, the process can take one to three business days depending on the originating institution’s policies.
Connecting External Financial Institutions via ACH
Automated Clearing House (ACH) transfers represent the backbone of domestic money movement. For members who want to automate their savings or investment strategies, setting up recurring ACH transfers is a professional-grade strategy. By establishing a pull from a secondary income source or another bank directly into a Navy Federal account, you can “pay yourself first” without manual intervention.
For those moving larger sums of money, it is vital to understand the difference between a “pull” and a “push” transfer. A pull transfer is initiated from within the Navy Federal interface, requesting money from your external bank. A push transfer is initiated from your external bank, sending money to Navy Federal. Often, “pushing” money from a high-yield savings account or a major commercial bank can result in faster availability of funds than a “pull” initiated by the credit union.
Immediate Funding Solutions: Direct Deposit and Mobile Check Deposits
For many members, the most consistent way to fund their Navy Federal account is through the automation of their primary income. Navy Federal has optimized these channels to provide immediate or even early access to capital, which is a significant advantage for those managing tight monthly budgets or aggressive investment schedules.
The Power of Direct Deposit for Consistent Growth
Direct deposit is arguably the most efficient way to fund an account. For active-duty military members and federal employees, Navy Federal often provides “Early Post” benefits. This means that if your payroll provider sends the notification of funds early, Navy Federal may credit your account up to a day or two before the actual payday.
Setting up direct deposit requires providing your employer or the Defense Finance and Accounting Service (DFAS) with your Navy Federal routing number and your specific account number. A professional tip for maximizing this funding method is to use “split direct deposit.” By directing a portion of your paycheck to a checking account for expenses and another portion directly into a Navy Federal high-yield savings account or a Money Market Savings Account (MMSA), you automate your wealth-building process at the source.
Mastering Mobile Check Deposits for On-the-Go Funding
While the world is moving toward a cashless society, paper checks—such as tax refunds, insurance settlements, or gifts—still play a role in personal finance. Navy Federal’s mobile deposit technology is highly sophisticated, utilizing image recognition to process checks quickly.
To ensure a smooth mobile deposit, members must adhere to specific endorsement requirements. It is now standard practice to sign the back of the check and write “For NFCU Mobile Deposit Only” beneath the signature. Failure to do so can result in the deposit being rejected by the automated system. Once submitted, funds are often made available partially on the same day, with the remainder clearing after a brief holding period. This holding period is a risk-management protocol that protects both the member and the credit union from potential fraud, and it typically shortens as the account tenure and member standing increase.
Modern Peer-to-Peer and Third-Party Funding Options
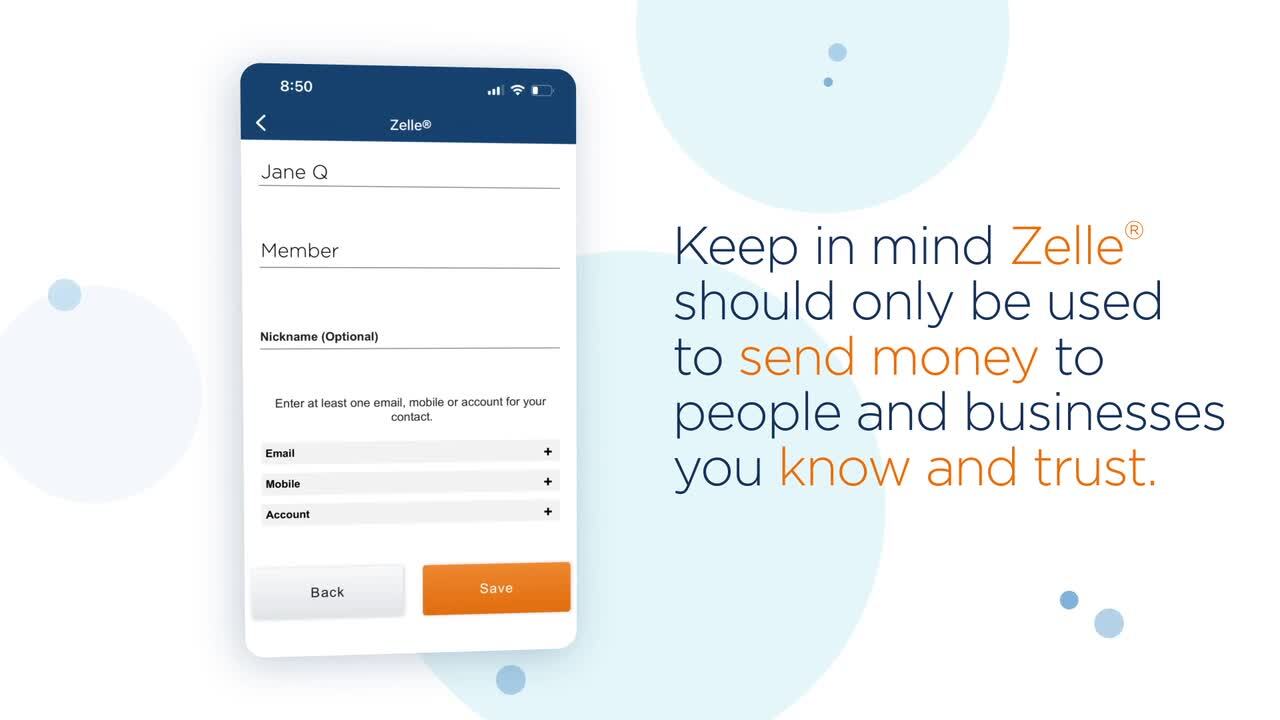
As financial technology evolves, the lines between traditional banking and social payment apps have blurred. Navy Federal has embraced these changes by integrating directly with popular peer-to-peer (P2P) services, allowing for near-instantaneous account funding from friends, family, or side-hustle platforms.
Utilizing Zelle for Instant Transfers
Zelle is integrated directly into the Navy Federal mobile app, providing a secure way to receive funds instantly from almost any other U.S.-based bank account. This is particularly useful for members who need to reimburse expenses or receive payments for freelance work. Because Zelle moves money directly between bank accounts without holding it in a third-party “wallet,” the funds are available to spend or invest via your Navy Federal account within minutes.
To fund your account via Zelle, you simply need to share your registered email address or mobile phone number with the sender. There are no fees associated with receiving money via Zelle at Navy Federal, making it a superior alternative to wire transfers for smaller, non-commercial amounts.
Wire Transfers for High-Value Capital Movement
For significant financial milestones—such as a down payment on a home, a large investment, or an inheritance—wire transfers remain the gold standard for speed and security. Unlike ACH transfers, which are processed in batches, wire transfers are handled individually and are typically cleared on the same business day if initiated before the cutoff time.
To receive a domestic wire transfer at Navy Federal, you must provide the sender with specific wiring instructions, which differ from standard ACH routing numbers. Navy Federal utilizes a specific transit routing number for wires. While Navy Federal generally does not charge a fee to receive domestic wires, the sending institution likely will. For international wires, the process involves using a SWIFT code. Given the complexity and the irreversible nature of wire transfers, it is recommended to double-check all account details to prevent capital from being stuck in administrative limbo.
Physical Funding: Branches, ATMs, and Shared Branching
Despite the digital revolution, physical infrastructure remains a vital component of the Navy Federal experience. For those who deal in cash or prefer face-to-face interactions, the credit union’s physical footprint offers diverse ways to inject capital into an account.
Utilizing the CO-OP Shared Branching Network
One of the most unique advantages of credit union membership is the concept of shared branching. Navy Federal is a participant in the CO-OP Shared Branch network, which allows members to conduct business at thousands of other credit union locations across the country as if they were at a Navy Federal branch.
This is a game-changer for members who are stationed in areas or living in regions without a local Navy Federal presence. By visiting a participating shared branch, you can deposit cash or checks directly into your NFCU account. You will need your Navy Federal account number and a valid government-issued photo ID. This network effectively gives Navy Federal one of the largest physical branch footprints in the United States, ensuring that you are never far from a way to fund your account.
Cash and Check Deposits via ATMs
Navy Federal’s own network of ATMs, along with participating partner ATMs, allows for 24/7 deposits. When using a Navy Federal branded ATM, cash deposits are typically credited to the account immediately, providing instant liquidity. Check deposits made via ATM follow a similar verification schedule to mobile deposits.
For members using non-NFCU ATMs, it is important to verify if the machine accepts deposits for the CO-OP network. Many “surcharge-free” ATMs allow for withdrawals but not deposits. Utilizing the ATM locator in the Navy Federal app can help you filter for machines that specifically support deposit functionality, saving time and ensuring your cash is securely moved into your digital balance.
Strategic Liquidity Management and Automation
Funding an account is the first step; optimizing how those funds are distributed is where true financial mastery begins. A professional approach to managing your Navy Federal accounts involves creating a “financial hub” where capital is strategically routed to various buckets based on your goals.
By utilizing the “Scheduled Transfers” tool within online banking, you can create a sophisticated waterfall of funds. For example, once your primary direct deposit hits your checking account, you can schedule an immediate transfer of a fixed percentage to your “Specialed Savings” account for an emergency fund, and another portion to your “Digital Investor” or brokerage account. This ensures that your funding efforts are not just keeping the account active, but are actively working toward long-term wealth accumulation.
In conclusion, funding your Navy Federal account is a multi-faceted process that can be tailored to your specific lifestyle and financial needs. From the high-tech integration of Zelle and mobile deposits to the expansive reach of the CO-OP Shared Branching network, Navy Federal provides the tools necessary to ensure your capital is always mobile, accessible, and ready to be put to work. By understanding the nuances of each method—timing, limits, and procedures—you can build a robust financial foundation that supports your journey toward financial independence.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.