
In the dynamic world of personal finance, few numbers hold as much sway over household budgets and future aspirations as home loan interest rates. For prospective homebuyers and current homeowners considering refinancing, understanding “what are home loan rates right now” isn’t merely a point of curiosity; it’s a critical financial imperative. These rates dictate the affordability of a mortgage, the size of monthly payments, and ultimately, the long-term cost of homeownership. The recent economic climate, marked by inflation, central bank interventions, and shifting market sentiments, has ushered in a period of significant volatility, making it more challenging than ever to pinpoint exact figures or predict future trends with certainty. This article aims to demystify the current landscape, explain the forces at play, and equip you with the knowledge to navigate the home loan market effectively.
Understanding the Current Landscape of Home Loan Rates
The present environment for home loan rates is characterized by a delicate balance of economic forces, central bank policies, and global market sentiment. To truly grasp “what are home loan rates right now,” one must look beyond a single number and delve into the underlying mechanisms.
A Snapshot of Today’s Market
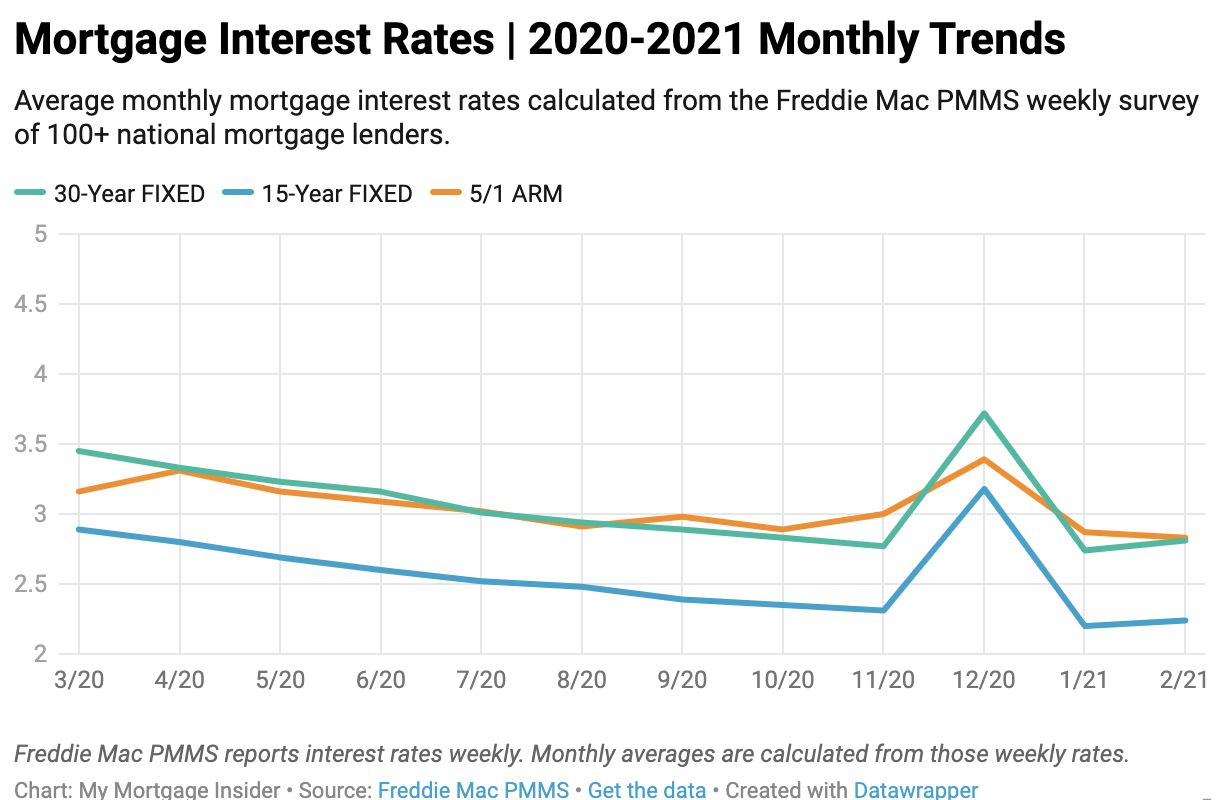
As of late, home loan rates have seen considerable fluctuation, largely influenced by the Federal Reserve’s actions to combat inflation. While specific rates vary daily and by lender, the general trend over the past year or two has been an upward climb from the historically low levels seen during the pandemic. We’ve moved from an era of sub-3% 30-year fixed-rate mortgages to a reality where rates often hover in the 6-8% range, sometimes even higher depending on market conditions and borrower specifics. This shift has significantly impacted affordability, pricing out some potential buyers and prompting others to reconsider their homeownership timelines. The market remains sensitive, with even minor economic data releases or policy statements capable of moving rates by several basis points in a single day. Prospective borrowers should prepare for a range of possibilities and monitor real-time data closely.
Key Economic Indicators at Play
Several powerful economic indicators act as the primary drivers behind the movement of home loan rates:
-
Inflation: This is arguably the most significant factor. When inflation is high, the Federal Reserve typically raises the federal funds rate in an effort to cool the economy. While the federal funds rate doesn’t directly dictate mortgage rates, it influences the overall cost of borrowing for banks, which then passes those costs on to consumers in the form of higher loan rates. Mortgage rates tend to rise in anticipation of and response to inflation and the Fed’s counter-actions.
-
Federal Reserve Policy: The Federal Open Market Committee (FOMC) meets regularly to discuss monetary policy, most notably setting the federal funds rate. Their statements and projections provide strong signals to the market. When the Fed signals a hawkish stance (e.g., intending to raise rates further), mortgage rates typically trend upward. Conversely, dovish signals (e.g., potential rate cuts or a pause) can lead to rates stabilizing or even decreasing.
-
The 10-Year Treasury Yield: Mortgage rates, particularly for 30-year fixed loans, are closely correlated with the yield on the 10-year U.S. Treasury bond. This bond yield serves as a benchmark for many long-term loans. When investors demand higher returns on Treasury bonds (e.g., due to inflation concerns or economic uncertainty), the yield rises, and mortgage rates usually follow suit.
The Impact of Global and Domestic Events
Beyond core economic indicators, broader events can inject volatility into the home loan market. Geopolitical tensions, such as international conflicts or trade disputes, can create uncertainty, prompting investors to seek safe-haven assets like U.S. Treasury bonds, which can influence yields and thus mortgage rates. Domestically, factors like employment reports, consumer confidence surveys, and GDP growth figures all contribute to the overall economic outlook, shaping investor sentiment and the trajectory of rates. A robust economy with strong job growth might encourage the Fed to maintain a tighter monetary policy, while signs of an economic slowdown could lead to expectations of easing, impacting rates accordingly.
Factors Influencing Your Specific Home Loan Rate
While macroeconomic forces set the general range of home loan rates, the specific rate you qualify for is a highly personalized matter. Lenders assess individual risk profiles, meaning two different borrowers applying for the same loan on the same day could receive vastly different offers.
Your Credit Score and Financial Health
Your credit score is paramount. Lenders use it as a quick indicator of your creditworthiness and your history of managing debt. Borrowers with excellent credit scores (typically 740 and above) are perceived as lower risk and generally qualify for the most competitive rates. Lower credit scores signal higher risk, leading to higher interest rates to compensate the lender for that increased risk. Beyond the score, your overall financial health, including your debt-to-income (DTI) ratio, plays a significant role. A high DTI indicates that a large portion of your income is already committed to debt payments, which can make lenders hesitant and result in less favorable rates.
Loan-to-Value (LTV) Ratio
The loan-to-value (LTV) ratio is a comparison of the amount of your mortgage to the appraised value of the home. It’s calculated by dividing the loan amount by the home’s value. A lower LTV, meaning you’re making a larger down payment, indicates less risk for the lender. For example, a 20% down payment results in an 80% LTV. Lenders often offer better rates for LTVs of 80% or less, as it means you have more equity in the home from the start, reducing the lender’s exposure if you default.
Loan Term and Type
The duration and type of your mortgage significantly impact the interest rate.
-
Loan Term: Shorter loan terms, such as a 15-year fixed-rate mortgage, typically come with lower interest rates than longer terms like a 30-year fixed-rate mortgage. This is because the lender is taking on less long-term interest rate risk and getting their money back faster. While monthly payments are higher on a 15-year loan, the total interest paid over the life of the loan is substantially lower.
-
Loan Type: Fixed-rate mortgages (FRMs) offer a consistent interest rate for the life of the loan, providing predictability. Adjustable-rate mortgages (ARMs) typically start with a lower interest rate for an initial period (e.g., 5 or 7 years) before adjusting periodically based on market indexes. ARMs often have lower initial rates but come with the risk of future payment increases.
Lender Specifics and Market Competition
Different lenders—banks, credit unions, and independent mortgage companies—have varying cost structures, risk appetites, and marketing strategies. This competition means that rates can differ significantly from one lender to another on any given day, even for the same borrower profile. Some lenders might specialize in certain loan types or cater to specific borrower segments, offering more competitive rates in those niches. It’s crucial not to assume that the first quote is the best.
Navigating the Home Loan Market: Strategies for Borrowers
In a volatile rate environment, a proactive and informed approach is essential for securing the best possible home loan. Strategic planning can save you tens of thousands of dollars over the life of your mortgage.
Shop Around and Compare Offers
This cannot be stressed enough: do not settle for the first loan offer you receive. Contact at least three to five different lenders to request quotes. Provide them with identical information to ensure an apples-to-apples comparison. Look not only at the interest rate but also at the Annual Percentage Rate (APR), closing costs, and any lender fees. Small differences in rates or fees can add up substantially over a 15- or 30-year mortgage. Many online tools and aggregators can help streamline this process, but direct contact with lenders is often necessary for personalized quotes.
Understand the APR vs. Interest Rate
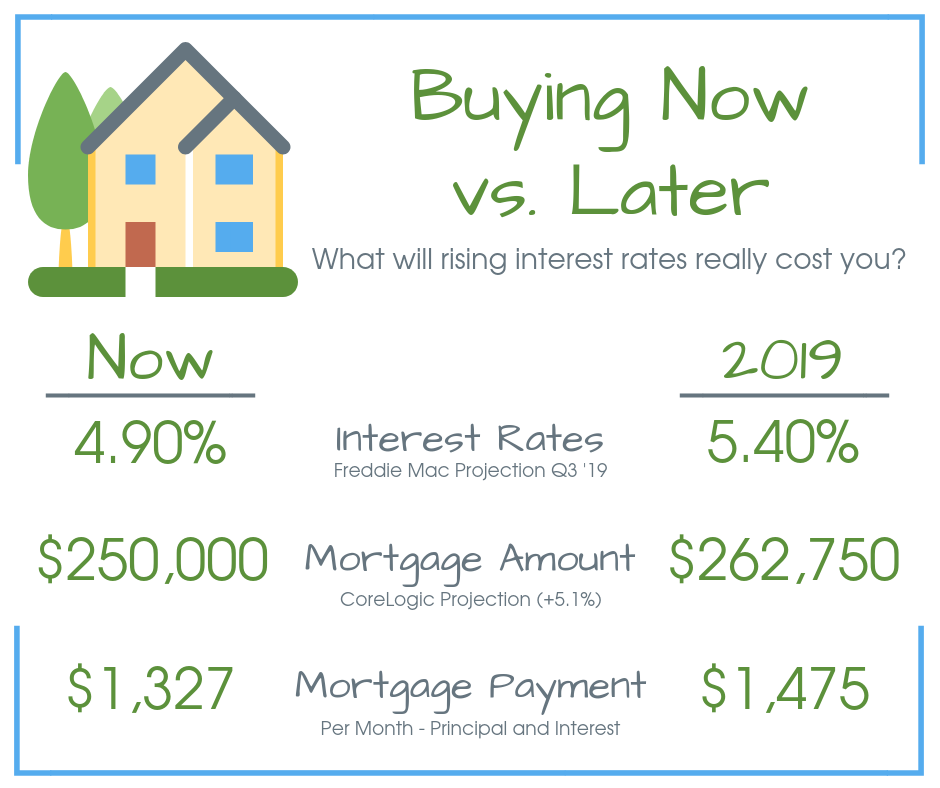
The interest rate is the percentage charged on the principal loan amount. The APR (Annual Percentage Rate) is a broader measure of the total cost of borrowing, expressed as an annual rate. It includes the interest rate plus certain fees and other charges (like origination fees, discount points, mortgage insurance, etc.) associated with the loan. While the interest rate tells you how much interest you’ll pay on the loan balance, the APR gives you a more comprehensive picture of the true cost of your loan. Always compare APRs when evaluating different loan offers to get the most accurate cost comparison.
Improving Your Financial Profile
Before even applying for a loan, take steps to strengthen your financial standing. Pay down existing debts, especially high-interest credit card balances, to lower your DTI ratio. Review your credit report for errors and dispute any inaccuracies. Make timely payments on all your accounts to boost your credit score. Accumulate as large a down payment as possible; a larger down payment not only reduces your LTV but also signals financial discipline to lenders, potentially earning you a lower rate.
The Role of Mortgage Brokers vs. Direct Lenders
-
Direct Lenders: These are banks, credit unions, and mortgage companies that lend their own money. They offer their own products and often have streamlined processes. If you prefer dealing directly with a single institution and value brand recognition, a direct lender might be a good fit.
-
Mortgage Brokers: These professionals act as intermediaries between you and multiple lenders. They have access to a wide range of loan products from various financial institutions and can shop around on your behalf to find the best rates and terms. Brokers can be particularly valuable if you have a complex financial situation or want an expert to guide you through the maze of options. They typically charge a fee, either paid by you or by the lender.
Consider Rate Locks
Given the volatility of current rates, a rate lock can be a valuable tool. A rate lock agreement guarantees that the interest rate offered to you will remain the same for a specified period (e.g., 30, 45, or 60 days) while your loan application is being processed. This protects you if rates rise during that time. However, be aware of “lock-in” fees and the expiration date of the lock. If rates fall significantly after you’ve locked, you might be unable to take advantage of the lower rates unless your lender offers a “float-down” option, which typically comes with its own conditions and fees.
Types of Home Loans and Their Rate Implications
Understanding the different types of home loans available is crucial, as each comes with unique rate structures, eligibility requirements, and long-term implications. The best choice for you depends on your financial situation, risk tolerance, and homeownership goals.
Fixed-Rate Mortgages (FRM)
A fixed-rate mortgage is the most common and perhaps the most straightforward loan type. With an FRM, your interest rate remains constant for the entire duration of the loan, typically 15 or 30 years. This provides unparalleled payment predictability, as your principal and interest payments will never change, regardless of market fluctuations.
-
Pros: Stability, predictable monthly payments, protection against rising interest rates.
-
Cons: Often have higher initial interest rates compared to ARMs, especially in a low-rate environment. You won’t benefit if market rates fall unless you refinance.
-
Ideal for: Borrowers seeking long-term stability, planning to stay in their home for many years, and those with a lower tolerance for risk.
Adjustable-Rate Mortgages (ARM)
An adjustable-rate mortgage (ARM) features an interest rate that changes periodically after an initial fixed-rate period. For example, a 5/1 ARM means the rate is fixed for the first five years, then adjusts annually for the remainder of the loan term, based on a specific market index plus a margin.
-
Pros: Often offer lower initial interest rates than FRMs, resulting in lower initial monthly payments. Can be beneficial if you anticipate moving or refinancing before the fixed-rate period ends.
-
Cons: Payment amounts can increase significantly after the fixed period, making budgeting challenging. Introduces interest rate risk.
-
Ideal for: Borrowers who plan to sell or refinance before the adjustment period, anticipate a significant increase in income, or are comfortable with the inherent risk of fluctuating payments.
Government-Backed Loans (FHA, VA, USDA)
These loan types are insured or guaranteed by a government agency, making them more accessible to specific borrower groups and often coming with more lenient eligibility requirements compared to conventional loans.
-
FHA Loans: Insured by the Federal Housing Administration, these loans are popular for first-time homebuyers due to lower down payment requirements (as little as 3.5%) and more flexible credit score criteria. They do, however, require mortgage insurance premiums (MIP) for the life of the loan. FHA rates are often competitive with conventional rates, but the MIP adds to the overall cost.
-
VA Loans: Guaranteed by the U.S. Department of Veterans Affairs, these loans are available to eligible veterans, active-duty service members, and surviving spouses. They offer significant benefits, including no down payment requirement, no private mortgage insurance (PMI), and competitive interest rates.
-
USDA Loans: Backed by the U.S. Department of Agriculture, these loans are designed to promote homeownership in rural and eligible suburban areas. They offer 100% financing (no down payment) and competitive rates for qualifying low- to moderate-income borrowers, often with lower mortgage insurance costs than FHA.
-
Rate Implications: While rates for these government-backed loans track conventional rates, their specific program benefits (like low down payments or no PMI) can make the effective cost of borrowing lower for eligible individuals.
Jumbo Loans
Jumbo loans are mortgages that exceed the conforming loan limits set by the Federal Housing Finance Agency (FHFA). These limits vary by location but are significantly higher in high-cost areas. Because jumbo loans are not eligible for purchase by Fannie Mae and Freddie Mac, they carry a higher risk for lenders.
-
Rate Implications: Historically, jumbo loan rates were higher than conforming loan rates. However, in certain market conditions, they can sometimes be competitive or even lower, depending on the lender’s portfolio strategy and the borrower’s financial strength (excellent credit, substantial assets, and large down payment are typically required).
-
Ideal for: Borrowers purchasing high-value properties that exceed conforming loan limits and who possess exceptional financial qualifications.
The Future Outlook for Home Loan Rates
Predicting the future of home loan rates with absolute certainty is impossible, as they are subject to a complex interplay of global economic, geopolitical, and domestic policy factors. However, economists and financial analysts constantly provide forecasts based on current trends and anticipated developments.
Expert Predictions and Market Forecasts
Many experts anticipate continued volatility in the near term. The Federal Reserve’s stance on inflation remains a dominant force. If inflation continues to moderate, there’s a possibility that the Fed might pause or even consider rate cuts in the future, which could lead to a downward pressure on mortgage rates. Conversely, a resurgence in inflation or stronger-than-expected economic growth could prompt the Fed to maintain higher rates for longer, potentially leading to further increases. Market forecasts often project a gradual stabilization, but the timing and magnitude of any significant shifts are hotly debated. Some believe rates may dip slightly, while others foresee them remaining elevated for the foreseeable future, making it imperative for potential borrowers to stay agile.
Potential Scenarios for Rate Movement
-
Continued Volatility: The most likely scenario in the immediate future is continued day-to-day or week-to-week fluctuations, driven by economic data releases and central bank commentary.
-
Stabilization: If inflation consistently declines and the economy shows signs of a soft landing, we might see rates stabilize within a certain range, offering more predictability for borrowers.
-
Further Increases: Should inflation prove more stubborn or economic growth accelerate unexpectedly, the Fed might be compelled to tighten monetary policy further, pushing mortgage rates higher.
-
Decreases: A significant economic slowdown or recession could prompt the Federal Reserve to cut rates aggressively, leading to a notable drop in mortgage rates. However, this scenario often comes with its own set of economic challenges for consumers.
Why Staying Informed is Crucial
Given this dynamic environment, staying informed is not just beneficial; it’s critical. Regularly monitor economic news, Federal Reserve announcements, and market analyses. Subscribe to financial news outlets, follow reputable mortgage industry experts, and check daily rate updates. Understanding the broader economic context will help you discern whether a particular rate movement is an anomaly or part of a larger trend, enabling you to make more timely and informed decisions regarding your home loan. Being prepared to act when rates align with your financial goals can make a substantial difference in the long run.

Conclusion
The question “what are home loan rates right now” doesn’t have a static answer; it’s a moving target influenced by a myriad of global and domestic forces. We are currently in an environment of elevated rates compared to the recent past, characterized by sensitivity to inflation and central bank policy. For anyone looking to buy a home or refinance an existing mortgage, this means a thoughtful, strategic approach is more important than ever.
Understanding the economic indicators that drive rates, diligently improving your financial profile, and thoroughly shopping around for the best offers are non-negotiable steps. Furthermore, familiarizing yourself with the nuances of different loan types—fixed-rate, adjustable-rate, and government-backed options—will empower you to select the product that best aligns with your financial comfort and long-term goals. While predicting the precise future of rates is a fool’s errand, staying informed and prepared to act decisively based on real-time information will put you in the strongest possible position to secure a home loan that serves your financial interests for years to come. In today’s market, knowledge is not just power; it’s pivotal to prudent financial decision-making in homeownership.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.