
The American Express® Gold Card stands as one of the most prestigious and functionally robust tools in the world of personal finance. Positioned strategically between entry-level rewards cards and the ultra-premium Platinum tier, the Amex Gold is frequently cited by financial experts as the “sweet spot” for consumers who prioritize dining and grocery expenditures. However, securing this piece of metal requires more than just a desire for its aesthetic appeal; it necessitates a solid financial profile, an understanding of the American Express ecosystem, and a strategic approach to the application process.
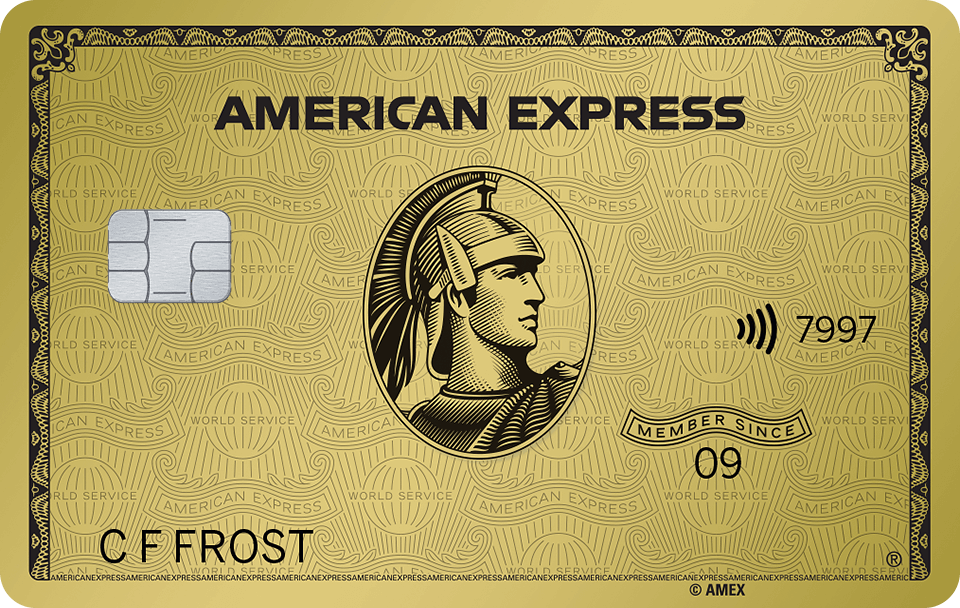
Obtaining the Amex Gold is a milestone for many building their credit portfolio. It signals a transition into high-tier credit management and unlocks a reward structure that can yield thousands of dollars in value when managed correctly. This guide explores the multifaceted process of qualifying for, applying for, and ultimately mastering the American Express Gold Card.
Understanding the Prerequisites and Eligibility Requirements
Before hitting the “Apply” button, it is essential to understand the financial benchmarks American Express typically looks for in a successful applicant. While the issuer does not publicly disclose exact cut-offs, historical data from thousands of applicants provides a clear picture of the ideal candidate.
Credit Score Benchmarks
The Amex Gold is a premium card, and as such, it requires a “Good” to “Excellent” credit score. Generally, applicants should aim for a FICO score of 700 or higher. While some individuals have been approved with scores in the high 600s, these approvals often come with lower internal spending limits or require a pre-existing relationship with the bank. If your score is currently below the 700 threshold, it is advisable to spend three to six months practicing credit optimization—paying down revolving balances and ensuring 100% on-time payment history—before applying.
Income and Debt-to-Income Ratio
Unlike traditional credit cards, the Amex Gold is technically a “Card with No Preset Spending Limit.” This does not mean unlimited spending; rather, your limit fluctuates based on your history, income, and financial resources. During the application, American Express will ask for your total annual income. They are looking for a Debt-to-Income (DTI) ratio that suggests you can comfortably manage your monthly obligations alongside potential new spending on the Gold card. Accuracy is paramount here; American Express is known for occasional “Financial Reviews,” where they may request tax documentation to verify the income stated on your application.
The “Once Per Lifetime” Rule and Eligibility
One of the most critical aspects of the American Express ecosystem is their “once per lifetime” rule regarding welcome bonuses. Generally, if you have held the Amex Gold Card in the past, you may be ineligible to receive the introductory points offer again. Furthermore, American Express has recently introduced family language across their product lines. This means that if you currently hold or have held the Amex Platinum Card, you might be ineligible for the Gold Card’s welcome bonus. Always check the specific “Terms and Conditions” on the application page to ensure you are eligible for the incentive.
Navigating the Application Process for Maximum Success
Once you have verified that your financial profile aligns with the requirements, the next step is the application itself. This stage is about more than just filling out a form; it is about timing and sourcing the best possible offer to maximize your financial return.
Finding the Best Welcome Offer
The standard welcome offer for the Amex Gold fluctuates, but it often sits between 60,000 and 90,000 Membership Rewards points after meeting a specific spending requirement (usually $6,000 within the first six months). To get the highest possible offer, you should look beyond the main American Express homepage.
-
Referral Links: Often, friends or family members who already hold the card can provide a referral link that features a higher bonus than the public offer.
-
The Resy Offer: American Express has a partnership with the dining platform Resy. Occasionally, applying through the Resy website provides a unique offer that includes a lower points bonus but adds significant cash-back statement credits for dining during the first year.
-
Incognito Browsing: Sometimes, opening the Amex website in a private or incognito browser window triggers a higher targeted offer based on your IP address and browsing data.
Utilizing the “Apply with Confidence” Tool
One of the most consumer-friendly innovations in recent years is the American Express “Apply with Confidence” feature. This allows prospective cardmembers to see if they are approved for the card with a “soft” credit pull, which does not impact their credit score. If you are approved and choose to accept the card, only then will a “hard” inquiry be performed. This significantly lowers the risk for those who are uncertain about their eligibility.
Handling a “Pending” or “Denied” Status
If your application isn’t instantly approved, it doesn’t necessarily mean a denial. A “Pending” status often means the system needs to verify your identity or address. If you are denied, American Express is required by law to provide an Adverse Action Notice explaining why. If the reason is something that can be clarified—such as a typo in your income or a temporary freeze on your credit report—you can call the Amex Reconsideration Line. Speaking with a representative allows you to plead your case, provide additional context, and potentially overturn the initial decision.
Strategic Use of the Amex Gold for Personal Finance Growth

Securing the card is only the beginning. To truly “get” the Amex Gold in a way that benefits your long-term wealth, you must understand how to leverage its rewards structure to offset the annual fee and generate surplus value.
Maximizing the 4x Multipliers
The core value proposition of the Amex Gold is its earning power in two primary categories:
-
4x at Restaurants: This includes takeout and delivery in the U.S.
-
4x at U.S. Supermarkets: On up to $25,000 in purchases per calendar year.
For a household that spends $1,000 a month on groceries and dining, the Amex Gold generates 4,000 Membership Rewards points monthly, or 48,000 points annually. At a conservative valuation of 2 cents per point (when transferred to travel partners), that is $960 in value from everyday spending alone.
Utilizing Monthly Statement Credits
The Amex Gold carries an annual fee (currently $250), which can be daunting. However, the card offers two primary credits that, if used, bring the “effective” annual fee down to nearly zero:
-
$120 Uber Cash: Distributed as $10 monthly credits for Uber eats or Uber rides in the U.S.
-
$120 Dining Credit: Distributed as $10 monthly credits for use at specific partners like Grubhub, The Cheesecake Factory, and Five Guys.
If you already use these services, the card effectively costs you $10 a year. If you do not use these services, the Amex Gold may not be the right financial tool for your specific lifestyle.
The Power of Membership Rewards (MR) Points
Unlike “cash back” cards, the Amex Gold earns Membership Rewards points. These are a form of private currency that is highly valuable because of its flexibility. While you can use points for gift cards or Amazon purchases, the highest value is found by transferring points to airline and hotel partners. Transferring points to partners like British Airways, Air Canada’s Aeroplan, or Hilton Honors can often result in redemption values far exceeding the standard 1 cent per point, effectively subsidizing luxury travel through daily grocery spending.
Is the Annual Fee Justified? A Cost-Benefit Analysis
A crucial part of personal finance is ensuring that every tool in your wallet earns its keep. The Amex Gold is not a “set it and forget it” card; it requires active management.
Calculating the Break-Even Point
To determine if the card is right for you, perform a simple break-even analysis. Subtract the value of the credits you will realistically use from the $250 annual fee. If you use the Uber and Dining credits, your remaining “cost” is $10. You would only need to earn 1,000 MR points in a year (which requires just $250 of spending at 4x) to break even. However, if you do not use the credits, you would need to earn 25,000 MR points (valued at 1 cent each) just to cover the fee. For the average consumer, this requires $6,250 in annual spending in the 4x categories.
Comparison with the Amex Platinum and Green Cards
In the hierarchy of American Express, the Gold Card is the “lifestyle” card. The Platinum Card ($695 annual fee) is a travel card focused on lounge access and hotel status, while the Green Card ($150 annual fee) focuses on general travel and transit. If your biggest monthly expenses are gas and travel, the Gold might actually be less efficient for you than the Green or a Blue Cash Preferred card. Successful personal finance is about matching the tool to the specific spending pattern.
Long-Term Management and Credit Health
Once the Amex Gold is part of your financial ecosystem, maintaining it is key to building a long-term relationship with American Express, which can lead to higher spending power and future premium offers.
Responsible Spending and Internal Limits
Because the Gold Card has no preset spending limit, it is vital to monitor your spending closely. Amex tracks your “Pay Over Time” limit, which is the amount they will allow you to carry as a balance with interest. However, for maximum financial health, the Gold Card should be treated as a charge card: pay the balance in full every month. This avoids high-interest charges and builds a “Spend Power” profile that allows you to make large purchases in the future without the card being declined.
Diversifying Your Credit Mix
The Amex Gold is a “revolving” account but behaves differently on a credit report than a standard credit card. It contributes to your “Payment History” but often does not factor into “Credit Utilization” in the same way because it doesn’t have a fixed limit. To build a robust credit profile, it is often wise to pair the Amex Gold with a traditional credit card (like the Amex Blue Business Plus or a Chase Freedom card) that has a high fixed limit, ensuring your utilization remains low while you rack up points on the Gold.
In conclusion, getting the Amex Gold is a process of aligning your credit profile with the issuer’s standards, timing your application to capture the best incentive, and then rigorously applying a strategy to ensure the card’s benefits outweigh its costs. When used correctly, it is not just a card, but a powerful engine for personal financial optimization.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.