
For many, possessing an American Express card represents more than just a piece of plastic; it signifies a certain level of financial standing, access to exclusive perks, and a commitment to responsible money management. American Express (Amex) has cultivated a reputation for premium travel rewards, exceptional customer service, and a diverse range of financial products tailored for individuals and businesses alike. If you’re considering joining the ranks of Amex cardholders, understanding the application process, eligibility criteria, and the unique value proposition is the crucial first step. This guide will demystify how to secure an American Express card, anchoring itself firmly within the realm of personal finance and financial tools.
Understanding the Allure of American Express
Before diving into the mechanics of application, it’s insightful to grasp why American Express cards are so sought after. Their brand legacy is deeply intertwined with luxury, travel, and a distinct approach to credit and financial services.
A Legacy of Premium Financial Services
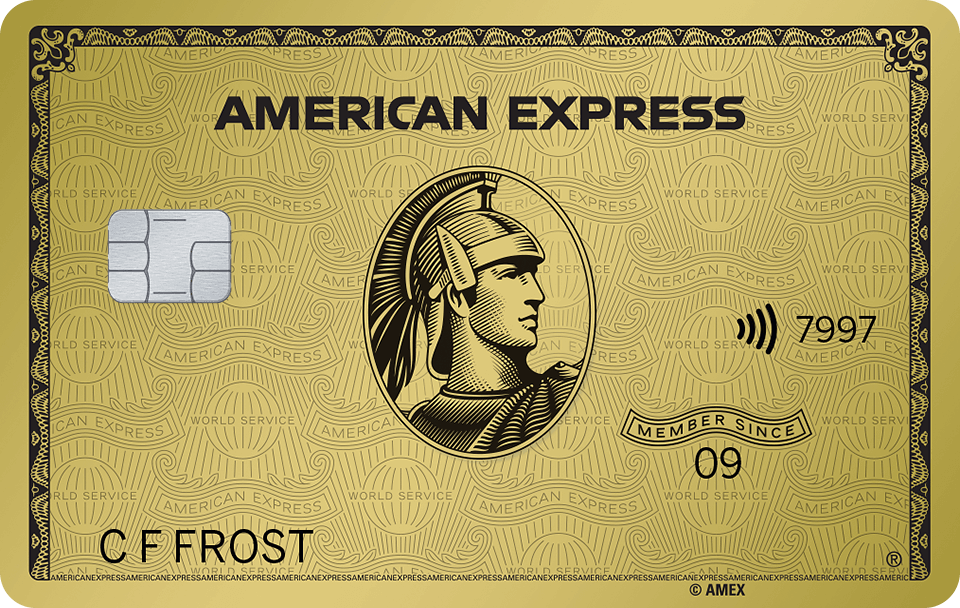
American Express began as an express mail business in 1850, evolving through the years to become a global financial services powerhouse. Unlike traditional banks that offer credit cards as one of many services, American Express specializes in payment solutions, travel-related services, and financial products. This focused approach has allowed them to carve out a niche, particularly among consumers who value high-tier rewards, concierge services, and comprehensive travel benefits. Their charge cards, which typically require payment in full each month, further differentiate them from standard revolving credit cards, often appealing to individuals with strong financial discipline and higher spending patterns. The Amex Green, Gold, and Platinum cards are iconic examples of this model, offering significant rewards in exchange for annual fees that unlock substantial value for frequent spenders and travelers.
Diverse Card Portfolio for Every Financial Need
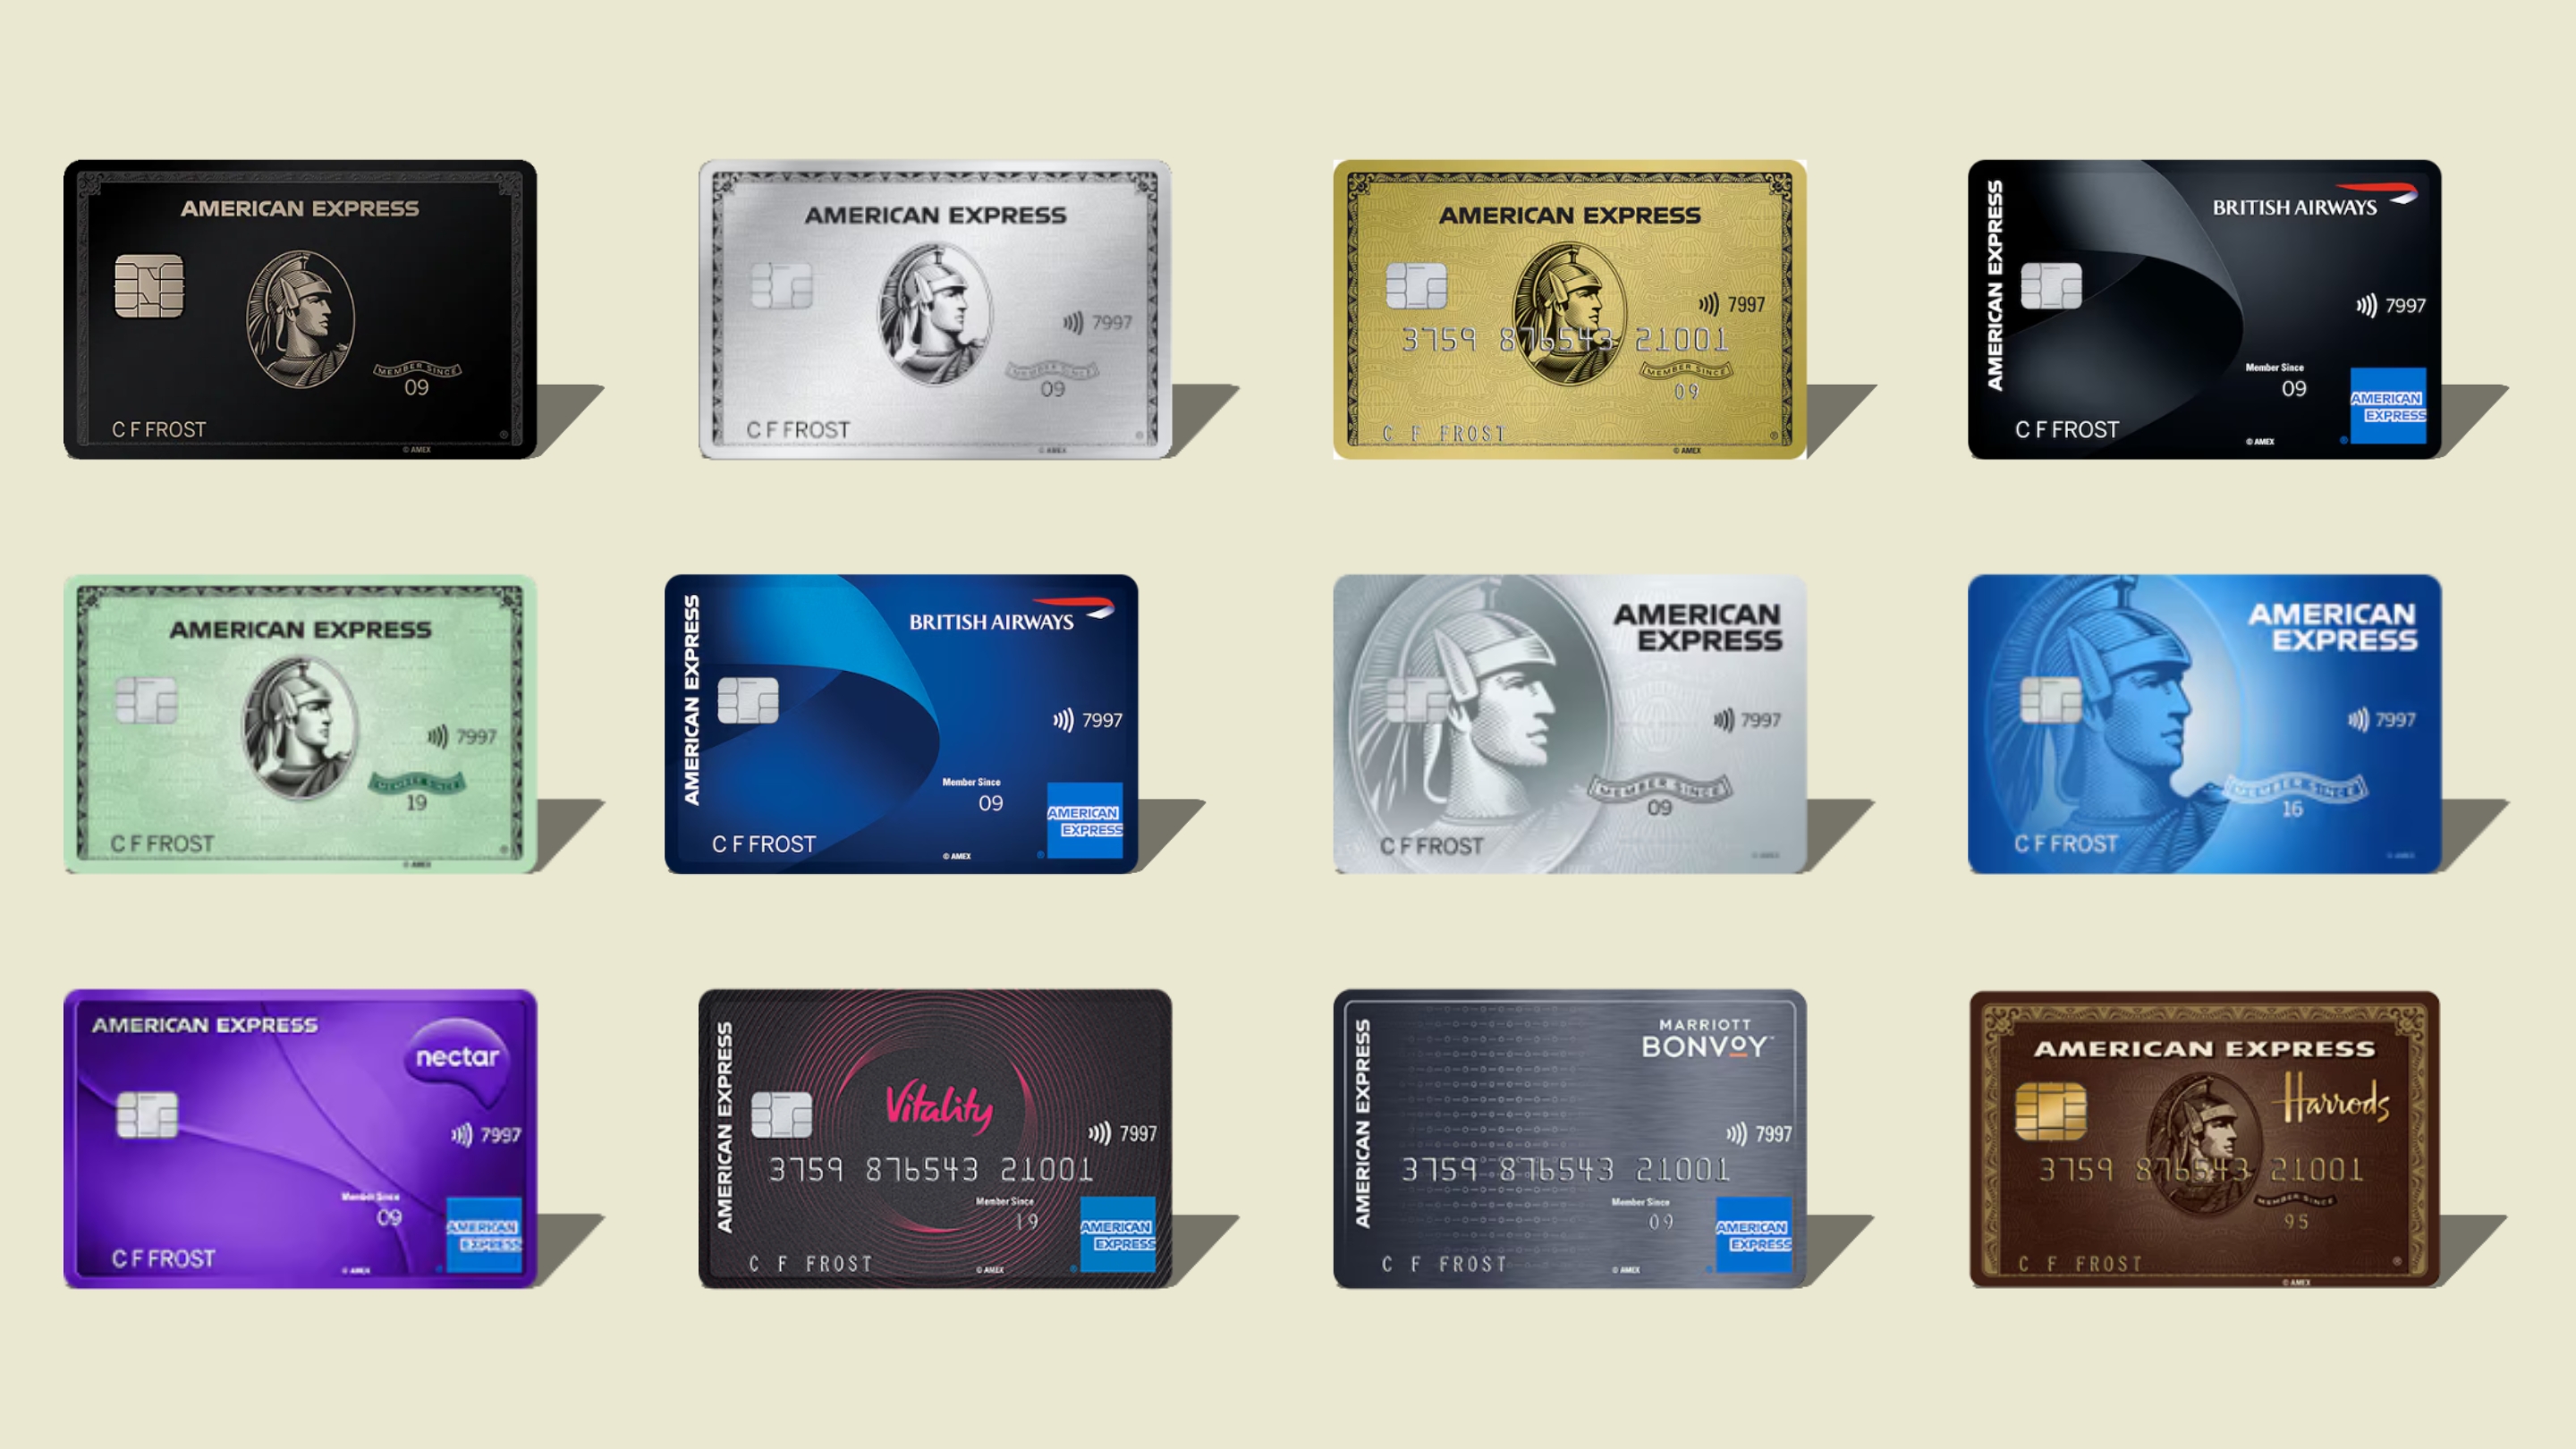
One common misconception is that American Express only caters to the ultra-wealthy. While they certainly have premium offerings, their portfolio is surprisingly broad, designed to meet a spectrum of financial needs and spending habits. From robust cash-back cards like the Blue Cash Everyday® Card to powerful travel cards such as the American Express® Gold Card or The Platinum Card®, there’s an Amex product for almost everyone. Business owners can also find tailored solutions with cards like The Business Platinum Card® from American Express or the Blue Business® Plus Credit Card. Each card is strategically designed with specific spending categories in mind, offering accelerated rewards on groceries, dining, travel, or business expenses. Identifying which card aligns best with your financial goals and spending patterns is paramount to a successful application and maximizing future benefits.
Key Eligibility Requirements for an Amex Card
Applying for an American Express card involves a rigorous evaluation of your financial health. Understanding what Amex looks for is critical to preparing a strong application. While specific criteria can vary slightly between card products, several core elements consistently influence approval decisions.
Credit Score: The Foundation of Your Application
Your credit score is arguably the most significant factor in qualifying for an American Express card. Amex typically targets applicants with excellent credit. While there’s no official minimum, most successful applicants for their popular travel and rewards cards, particularly those with higher annual fees, generally have a FICO score of 670 or higher, with many having scores well into the “very good” (740-799) or “excellent” (800+) ranges. Some entry-level or co-branded cards might be accessible with good credit (670-739), but aiming for a strong credit profile significantly enhances your chances. Amex uses various credit bureaus (Experian, TransUnion, Equifax) and their own proprietary scoring models, so ensuring your credit reports are accurate and healthy across the board is essential.
Income and Financial Stability
American Express wants to see that you have the financial capacity to manage your credit obligations. This means your income plays a vital role. While there isn’t a strict income threshold that applies to all cards, higher-tier cards with substantial benefits and annual fees often implicitly require a higher income level to ensure you can not only pay your bills but also take full advantage of the card’s offerings. Amex will assess your reported income, employment stability, and potentially other assets. They are looking for a consistent ability to generate income that supports your lifestyle and credit usage. Be honest and accurate when reporting your income, as misrepresentation can lead to application denial or even account closure later.
Debt-to-Income Ratio and Credit History
Beyond just your income, Amex evaluates your debt-to-income (DTI) ratio. This metric compares your total monthly debt payments to your gross monthly income. A lower DTI indicates that you have more disposable income available to meet new financial obligations, which is favorable to lenders. Furthermore, your overall credit history, including the length of your credit history, payment consistency, and the types of credit you’ve held, is scrutinized. A long history of on-time payments, responsible use of diverse credit products (like mortgages, auto loans, and other credit cards), and a low credit utilization ratio (how much credit you use versus how much you have available) all contribute positively to your application. Avoid recent bankruptcies, foreclosures, or a history of missed payments, as these are significant red flags.
Understanding Amex’s Unique Underwriting Process
American Express is known for its nuanced underwriting process. They often consider your relationship with them if you’re an existing customer, potentially offering pre-approvals or easier access to new products. They also use what’s sometimes called “the Amex internal score” which takes into account your past spending and payment behavior with them. Unlike some other lenders, Amex has been known to be somewhat more sensitive to recent credit applications (hard inquiries) if you have many in a short period. They value loyalty and a consistent, positive financial track record, both within and outside their ecosystem.
Navigating the American Express Card Application Process
Once you’ve assessed your financial readiness, the next step is to navigate the actual application. The process is generally straightforward, but a strategic approach can improve your outcomes.
Choosing the Right Amex Card for You
This is arguably the most critical preliminary step. Do you prioritize travel points, cash back, or business expense management? Are you willing to pay an annual fee for premium benefits, or do you prefer a no-annual-fee option? Research different Amex cards thoroughly. Use online comparison tools, read reviews, and carefully examine the rewards structure, benefits (e.g., lounge access, rental car insurance, purchase protection), and annual fees. Understanding the specific eligibility requirements for your chosen card will prevent a wasted application and a hard inquiry on your credit report. For instance, The Platinum Card is geared towards frequent travelers, while the Blue Cash Preferred® Card is excellent for everyday spending at U.S. supermarkets and streaming services.
Gathering Necessary Information
Before you start the online application, ensure you have all the required information readily available. This typically includes:
-
Personal Information: Full name, date of birth, Social Security Number (SSN) or Individual Taxpayer Identification Number (ITIN), contact information (address, phone, email).
-
Financial Information: Gross annual income (from all sources), employment status, and potentially your current employer’s details.
-
Housing Information: Monthly housing payment (rent or mortgage).
Having these details at hand will make the application process quick and seamless, minimizing the chance of errors or incomplete submissions.
Submitting Your Application: Online vs. Other Methods
The vast majority of American Express card applications are submitted online through their official website. This is generally the fastest and most convenient method. The online form is intuitive, guiding you through each section.
Other methods include:
-
Mail Offers: If you receive a pre-approved or pre-selected offer in the mail, it often comes with a unique offer code you can use to apply online or via mail. These offers often indicate a higher chance of approval.
-
Phone Application: You can call American Express directly to apply, though this is less common for new applicants unless you have specific questions.
-
In-Person (Limited): While rare for direct credit card applications, some financial advisors or specific business relationship managers might facilitate applications.
Always apply directly through American Express’s official channels to ensure security and prevent scams.
What Happens After You Apply?
Once you submit your application, one of three immediate outcomes usually occurs:
-
Instant Approval: Congratulations! You’ll receive a notification that your application has been approved, often with details about your credit limit (for credit cards) or spending limit (for charge cards) and an estimated card arrival date.
-
Instant Denial: You’ll be notified that your application has been denied, usually with a brief reason. American Express is required to provide a more detailed adverse action notice by mail within a certain timeframe, explaining the specific factors that led to the denial.
-
Pending Review: Your application might go into a “pending” status for further review. This could mean Amex needs more information, wants to verify certain details, or is conducting a more in-depth assessment. In such cases, you might receive a call or email from Amex, or you can call their application status line to inquire. This is not necessarily a bad sign and often results in approval after verification.
Maximizing Your Chances of American Express Approval
Even with good credit, gaining approval for an American Express card can be competitive. Here are strategies to bolster your application.
Strategically Improving Your Credit Profile
If your credit score isn’t in the “excellent” range, take steps to improve it before applying.
-
Pay Bills on Time: Payment history is the most critical factor. Set up reminders or auto-pay.
-
Reduce Credit Utilization: Keep your credit utilization ratio below 30%—ideally much lower, around 1-10%.
-
Address Errors on Credit Reports: Obtain free copies of your credit reports from AnnualCreditReport.com and dispute any inaccuracies.
-
Avoid New Credit Inquiries: Limit applications for new credit in the months leading up to your Amex application, as multiple hard inquiries can temporarily lower your score.
-
Build a Long Credit History: The longer your positive credit history, the better. Don’t close old, unused credit accounts, as this can shorten your average account age.
Demonstrating Financial Responsibility
Beyond your credit score, showing overall financial prudence is key.
-
Maintain Stable Employment: A consistent job history reflects reliability.
-
Manage Existing Debt Wisely: If you have student loans or a mortgage, ensure you’re making consistent payments.
-
Have Sufficient Emergency Savings: While not directly asked on the application, a healthy savings account reflects a strong financial buffer, indirectly supporting your ability to manage credit.
-
Accurately Report Income: Provide a realistic and verifiable income figure. Amex may ask for proof of income, especially for high-limit cards.
Leveraging Existing Relationships (if applicable)
If you already have a banking relationship with American Express (e.g., an Amex savings account, or perhaps you’re an authorized user on another Amex card), this might subtly benefit your application. Amex values existing customer relationships and has more data on your financial behavior if you’re already in their system. Sometimes, being an authorized user on a well-managed Amex account can provide a positive entry point into building a relationship with the company, although it doesn’t guarantee approval for your own primary card.
Beyond Approval: Making the Most of Your Amex Card
Congratulations, your American Express card has arrived! This is just the beginning. To truly harness its power and avoid common financial pitfalls, strategic management is crucial.
Understanding Your Card’s Benefits and Rewards
Don’t just activate your card and start spending. Take the time to thoroughly read the cardholder agreement and benefits guide. Understand:
-
Reward Structure: How do you earn points, miles, or cash back? Are there bonus categories? Are there spending caps?
-
Annual Fee: Be clear on when it’s charged and if it’s offset by the value you receive.
-
Travel Benefits: Lounge access, travel insurance, hotel status, car rental perks.
-
Purchase Protections: Extended warranty, return protection, purchase protection.
-
Statement Credits: Many premium cards offer annual statement credits for specific purchases (e.g., airline fees, dining, digital entertainment). Make sure you know how to activate and utilize these.
Many Amex cardholders fail to maximize their benefits simply because they aren’t aware of them.
Responsible Card Management
An American Express card, like any financial tool, requires responsible handling.
-
Pay Your Bills On Time, Every Time: This is non-negotiable for maintaining good credit and avoiding late fees. For charge cards, the full balance is typically due each month. For credit cards, paying the full statement balance is always recommended to avoid interest charges.
-
Monitor Your Spending: Avoid overspending simply because you have a higher credit limit or feel entitled to luxury. Stick to a budget.
-
Review Statements Regularly: Check for unauthorized transactions and ensure all charges are accurate.
-
Utilize Online Tools: American Express offers excellent online account management and mobile app features to track spending, monitor rewards, and manage payments.
Considering the Annual Fee and Value Proposition
For many American Express cards, particularly the rewards-rich travel and premium options, an annual fee is standard. Before your card’s renewal, conduct a yearly “value audit.” Add up the monetary value of the rewards you’ve earned, the statement credits you’ve used, and the qualitative value of benefits like lounge access or concierge services. If this total value consistently outweighs the annual fee, then the card is likely a worthwhile investment. If not, it might be time to consider a different Amex product, downgrade to a no-annual-fee option, or explore cards from other issuers.
Obtaining an American Express card is a journey that starts with solid financial planning and a clear understanding of your needs. By demonstrating financial responsibility, strategically choosing the right card, and diligently managing your account, you can unlock a world of benefits and enjoy the prestige associated with the American Express brand, truly making it a valuable asset in your personal financial toolkit.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.