
At its core, a tax filing is a formalized communication between an individual or business entity and a government tax authority. It serves as a comprehensive report of one’s financial activities over a specific period—typically a calendar year—and is used to determine the exact amount of tax owed to the state or federal government. While many view the annual ritual of filing taxes with a sense of dread or confusion, it is fundamentally a pillar of personal and corporate finance that ensures the funding of public infrastructure, social services, and national security.
Understanding what a tax filing entails is essential for navigating the modern financial landscape. It is not merely a list of numbers; it is a legal declaration of income, expenses, and eligibility for various government-sponsored financial incentives. Whether you are an employee receiving a standard salary, a freelancer navigating the gig economy, or a business owner managing a complex payroll, the tax filing process is the mechanism through which your financial contributions to society are calculated, verified, and finalized.
The Anatomy of a Tax Return: Beyond the Paperwork
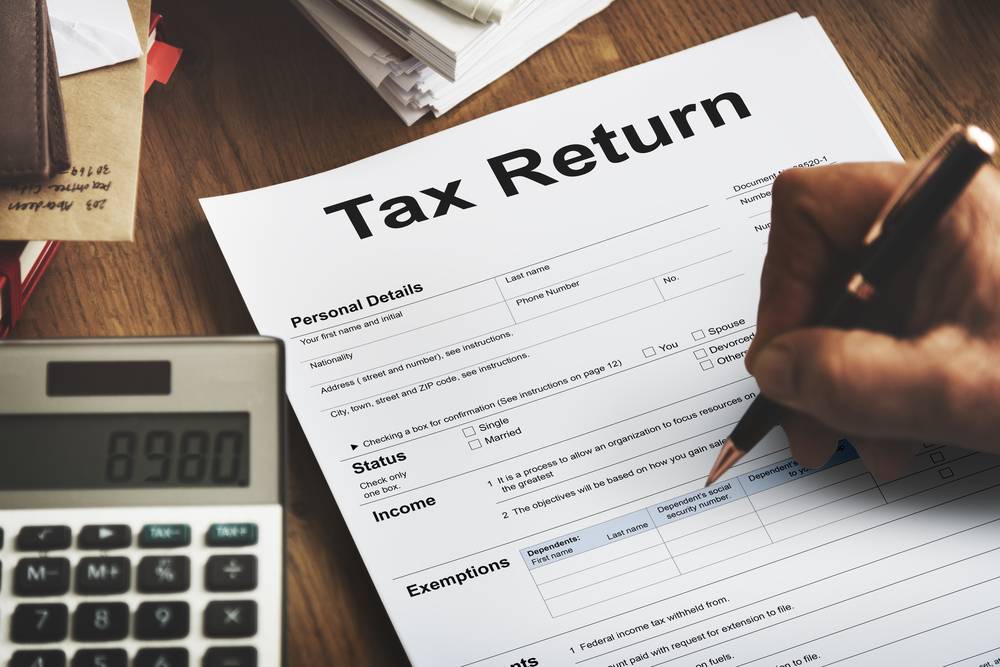
To understand a tax filing, one must first understand the “tax return.” The return is the actual document—or set of documents—submitted to an agency like the Internal Revenue Service (IRS) in the United States or equivalent bodies internationally. The anatomy of a return is built upon several critical financial pillars: income reporting, the application of deductions, and the calculation of credits.
Defining the Scope of Income
Income is the primary variable in any tax filing. However, from a financial perspective, income is not a monolithic concept. Taxable income includes “earned income,” such as wages, salaries, tips, and professional fees. It also encompasses “unearned income,” which includes interest from savings accounts, dividends from stocks, capital gains from the sale of assets, and even certain types of passive income like rental payments or royalties. A thorough tax filing must account for every stream of revenue to ensure that the taxpayer is in compliance with the law. Failing to report even a minor source of income can lead to penalties, interest, and in some cases, a comprehensive audit.
The Duality of Deductions and Credits
Once total income is established, the filing process moves into the realm of “adjustments.” This is where strategic financial management comes into play. Taxpayers use deductions and credits to lower their overall tax liability.
-
Deductions: These are expenses that the government allows you to subtract from your gross income. By reducing the amount of income that is subject to taxation, you effectively lower your tax bill. Common deductions include mortgage interest, student loan interest, and contributions to traditional retirement accounts like a 401(k) or an IRA. Most taxpayers choose between a “standard deduction”—a flat amount set by the government—and “itemized deductions,” which require detailed records of specific expenses.
-
Credits: While deductions reduce the income you are taxed on, credits are even more powerful because they reduce the actual tax dollar-for-dollar. For example, if you owe $5,000 in taxes and qualify for a $2,000 child tax credit, your total bill drops directly to $3,000. Credits are often used by the government to incentivize certain behaviors, such as adopting green energy solutions, pursuing higher education, or supporting low-income families.
Navigating the Legal and Financial Obligations
A tax filing is more than a calculation; it is a legal obligation with significant consequences. The “filing requirement” is determined by several factors, including your gross income, your age, and your filing status. Even if you do not owe any money to the government, filing a return may be necessary to claim a refund for taxes that were over-withheld from your paycheck throughout the year.
Who is Required to File?
The threshold for filing changes periodically based on inflation and legislative updates. Generally, if your income exceeds the standard deduction for your age and status, you are legally required to file. For the self-employed, the rules are often stricter; even a small amount of net earnings (often as low as $400) can trigger a filing requirement to account for self-employment taxes, which cover Social Security and Medicare contributions. Understanding these thresholds is vital for avoiding the “failure to file” penalties that can accrue over time.
Federal vs. State Jurisdictions
In many regions, tax filing is a multi-layered process. In the United States, for instance, a taxpayer may need to file a federal return with the IRS and a separate state return with their state’s department of revenue. Each jurisdiction has its own set of rules, tax brackets, and available credits. Some states, like Florida or Texas, do not impose a state income tax at all, whereas others, like California or New York, have robust systems that require meticulous reporting. This dual-filing system requires a high level of organizational skill to ensure that data is consistent across all platforms.
Choosing Your Filing Status: A Strategic Decision
One of the first decisions a taxpayer must make during the filing process is selecting a “filing status.” This choice is not merely a label; it dictates the tax rates applied to your income and the size of the standard deduction you are eligible to claim.

Individual Statuses and Their Impacts
The most common statuses include Single, Married Filing Jointly, Married Filing Separately, and Head of Household.
-
Single: Generally for those who are unmarried and do not qualify for another status.
-
Married Filing Jointly: Often the most beneficial for couples, as it usually offers lower tax rates and higher deduction limits.
-
Head of Household: Designed for unmarried individuals who pay more than half the cost of keeping up a home for a qualifying person (such as a child or a dependent parent). This status provides more favorable rates than the “Single” status, acknowledging the higher cost of living associated with supporting dependents.
Choosing the wrong status can lead to overpaying or underpaying, both of which have long-term financial implications. For example, married couples may sometimes find that “Filing Separately” is more advantageous if one spouse has significant medical expenses or if they wish to keep their financial liabilities distinct.
Business Entities and Special Filing Requirements
For entrepreneurs and business owners, tax filing becomes significantly more complex. The “structure” of the business—whether it is a Sole Proprietorship, an S-Corporation, a Partnership, or a C-Corporation—determines how income is reported.
-
Pass-through Entities: In sole proprietorships and many LLCs, the business’s income “passes through” to the owner’s personal tax return. These are reported on specific schedules (like Schedule C) as part of the individual’s tax filing.
-
Corporate Filings: Larger corporations are treated as separate legal entities and must file their own dedicated tax returns (such as Form 1120). These filings involve balance sheets, detailed profit and loss statements, and complex calculations regarding depreciation and capital expenditures.
The Modern Filing Process: From Documentation to Submission
The era of hand-calculating tax returns on paper is largely over, replaced by sophisticated software and digital ecosystems. However, the fundamental process of gathering documentation remains the most labor-intensive part of any filing.
Gathering Essential Documentation
A successful tax filing relies on the accuracy of the underlying data. Throughout the year, taxpayers should maintain a “tax file” containing:
-
W-2 Forms: Provided by employers to report annual wages and taxes withheld.
-
1099 Forms: Used for independent contractors, interest, dividends, and other miscellaneous income.
-
1098 Forms: Used to report mortgage interest or tuition payments.
-
Receipts and Invoices: Essential for those itemizing deductions or claiming business expenses.
Accuracy at this stage is paramount. The IRS receives copies of most W-2s and 1099s directly from the payers. If the numbers on your filing do not match the numbers in the government’s database, it triggers an automated red flag, often resulting in a “CP2000” notice—a letter informing you of a discrepancy and a potential increase in your tax bill.
The Shift to Digital: E-Filing and Security
E-filing has become the standard, offering faster processing times and quicker refunds. Modern tax software uses interview-style questions to guide users through the process, helping to identify deductions that might otherwise be missed. However, the digitization of tax filing has also introduced new risks regarding digital security. Tax returns contain the most sensitive personal information imaginable—Social Security numbers, bank account details, and income history. Using secure, encrypted platforms and being wary of phishing scams is a critical component of the modern filing experience.
Strategic Tax Management: Optimizing for Long-Term Wealth
Viewing a tax filing as a once-a-year event is a missed opportunity for wealth creation. Instead, savvy taxpayers view the filing as the culmination of a year-long strategy of “tax efficiency.”
Avoiding Common Pitfalls and Audits
The best way to manage a tax filing is to ensure it is “audit-proof.” This means keeping meticulous records for at least three to seven years, depending on the complexity of the return. Common triggers for audits include disproportionately high charitable contributions relative to income, large business losses in consecutive years, or failing to report offshore bank accounts. By understanding these triggers, taxpayers can ensure their filings are aggressive enough to save money but conservative enough to avoid unwanted government scrutiny.
Integrating Tax Filing into a Financial Plan
Finally, a tax filing should serve as a diagnostic tool for your overall financial health. A large tax refund, while often celebrated, is technically an interest-free loan you gave to the government. Adjusting your withholdings throughout the year can put that money back into your monthly budget or investment accounts where it can grow. Conversely, a large tax bill at the end of the year indicates a need for better planning, perhaps through increased contributions to tax-deferred retirement accounts or better management of estimated quarterly payments.
In conclusion, a tax filing is much more than a mandatory government form. It is a comprehensive financial statement that reflects your income, your family structure, and your financial priorities. By mastering the nuances of income types, deductions, and filing statuses, you can transform a routine administrative task into a powerful tool for financial optimization and long-term wealth building. Understanding what a tax filing is—and how to navigate it effectively—is the first step toward true financial literacy and independence.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.