
The concept of “avoiding tax” often carries a negative connotation, yet in the world of personal finance, tax avoidance is a perfectly legal and essential strategy for wealth preservation. Unlike tax evasion, which involves illegal practices to misrepresent income or hide assets, tax avoidance is the art of utilizing the tax code as it was written to minimize your liability. By understanding the nuances of the financial system, you can ensure that you are not paying more than your fair share, allowing you to reinvest that capital into your future, your business, or your family.
To navigate the complexities of the tax landscape, one must move beyond the simple filing of an annual return and instead adopt a year-round mindset of tax efficiency. This involves strategic planning across various pillars of finance, including retirement savings, investment management, and business structuring.
Leveraging Tax-Advantaged Retirement Accounts
One of the most effective ways to lower your taxable income is to divert funds into accounts specifically designed by the government to encourage long-term saving. These accounts provide immediate relief or long-term benefits that can significantly alter your financial trajectory.
The Power of Traditional 401(k)s and IRAs
For many professionals, the Traditional 401(k) or 403(b) remains the primary tool for tax reduction. Contributions to these accounts are made “pre-tax,” meaning the money is taken out of your paycheck before the IRS calculates your income tax for the year. If you earn $100,000 and contribute $20,000 to your 401(k), the government views your taxable income as $80,000. This can effectively drop you into a lower tax bracket, providing immediate savings.
Similarly, a Traditional Individual Retirement Account (IRA) offers tax-deductible contributions depending on your income level and whether you have access to a workplace plan. While these funds are taxed upon withdrawal in retirement, the strategy assumes you will be in a lower tax bracket during your golden years than you are during your peak earning years.
The Health Savings Account (HSA) Secret
Often overlooked as a retirement tool, the Health Savings Account (HSA) is arguably the most tax-efficient vehicle available in the United States. To qualify, you must be enrolled in a High Deductible Health Plan (HDHP). The HSA offers a “triple tax advantage”:
-
Contributions are tax-deductible (or pre-tax via payroll).
-
The growth on investments within the account is tax-free.
-
Withdrawals for qualified medical expenses are tax-free.
After age 65, the HSA functions much like a Traditional IRA; you can withdraw funds for any purpose and pay ordinary income tax, but the medical withdrawal benefit remains intact. For those looking to avoid tax while building a safety net, maximizing an HSA is a top-tier strategy.
Strategic Investing and Tax-Loss Harvesting
Investing in the stock market is a cornerstone of wealth building, but without a tax-efficient approach, a significant portion of your gains can be eroded by capital gains taxes. Mastering the timing and nature of your investments is crucial.
Tax-Loss Harvesting: Turning Lemons into Lemonade
Tax-loss harvesting is the practice of selling an investment that has lost value to offset the capital gains earned from other successful investments. If you realized a $10,000 gain on Stock A but are holding Stock B which is down $10,000, selling Stock B allows you to cancel out the taxable gain from Stock A.
Even if you don’t have capital gains to offset, the IRS allows you to use up to $3,000 of capital losses to offset your ordinary income each year. Any excess losses can be “carried forward” to future tax years. This strategy requires a firm grasp of the “Wash Sale Rule,” which prevents you from claiming a loss if you buy a “substantially identical” security within 30 days before or after the sale.
Long-Term vs. Short-Term Capital Gains
The duration for which you hold an asset significantly impacts your tax rate. Assets held for one year or less are subject to short-term capital gains taxes, which are taxed at your ordinary income tax rate (up to 37%). However, assets held for more than a year qualify for long-term capital gains rates, which are significantly lower—0%, 15%, or 20%, depending on your total income. By simply waiting 366 days to sell an appreciated asset, you can effectively “avoid” a massive portion of the tax that would have otherwise been due.
Municipal Bonds and Tax-Exempt Interest
For investors in high tax brackets, municipal bonds offer an attractive way to generate income. The interest earned on bonds issued by state and local governments is generally exempt from federal income tax. In many cases, if you live in the state where the bond was issued, the interest is also exempt from state and local taxes. This “double” or “triple” tax-exempt status makes municipal bonds a staple for those seeking to minimize their annual tax bill while maintaining a fixed-income portfolio.
Maximizing Deductions for Business Owners and Freelancers
The tax code is particularly favorable toward business owners, entrepreneurs, and those with “side hustles.” By shifting your perspective from an employee to a business entity, you unlock a vast array of deductible expenses that can dramatically reduce your taxable profit.

The Section 199A Qualified Business Income Deduction
A significant benefit for many small business owners is the Qualified Business Income (QBI) deduction. This allows eligible self-employed individuals and “pass-through” entity owners (like S-Corps and LLCs) to deduct up to 20% of their qualified business income from their taxes. This is a “below-the-line” deduction, meaning it reduces your taxable income regardless of whether you itemize your deductions or take the standard deduction.
Home Office and Operational Expenses
If you use a portion of your home exclusively for business, you may be eligible for the home office deduction. This allows you to deduct a percentage of your rent or mortgage interest, utilities, insurance, and repairs. Beyond the home office, almost any expense that is “ordinary and necessary” for your business can be deducted. This includes:
-
Marketing and Advertising: Website hosting, social media ads, and branding services.
-
Professional Services: Legal fees, accounting software, and business coaching.
-
Travel and Meals: While rules regarding meal deductions fluctuate, business-related travel remains a potent way to reduce taxable income.
Investing in Equipment via Section 179
For businesses that require physical assets—such as computers, machinery, or vehicles—Section 179 of the tax code allows for an immediate deduction of the full purchase price of qualifying equipment. Instead of depreciating the asset over several years, you can take the entire deduction in the year you put the equipment into service, providing a massive shield against that year’s revenue.
Real Estate Strategies and Wealth Transfer
Real estate has long been touted as one of the best asset classes for tax avoidance. The combination of structural incentives and specialized exchange rules makes it a powerful vehicle for building untaxed or tax-deferred wealth.
Depreciation: The “Paper Loss”
Depreciation is a non-cash expense that allows property owners to deduct the costs of buying and improving a property over its useful life. For residential real estate, this is typically 27.5 years. Even if your property is increasing in market value and generating positive cash flow, the depreciation deduction can often result in a “tax loss,” meaning you pay zero tax on the rental income you receive.
The 1031 Exchange: Deferring Gains Indefinitely
One of the most potent tools in a real estate investor’s arsenal is the 1031 Exchange. Named after Section 1031 of the Internal Revenue Code, this provision allows you to sell an investment property and reinvest the proceeds into a “like-kind” property while deferring all capital gains taxes. There is no limit to how many times you can perform a 1031 exchange. Theoretically, an investor can trade up into larger and more profitable properties throughout their lifetime, never paying a cent in capital gains tax along the way.
Strategic Gifting and the Step-Up in Basis
When it comes to passing wealth to the next generation, the “step-up in basis” is a critical concept. If you sell an asset that has appreciated significantly, you pay tax on the growth. However, if you hold that asset until death and pass it to your heirs, the “basis” of the asset is “stepped up” to its current market value. If your heirs sell the asset immediately, they pay zero capital gains tax on the appreciation that occurred during your lifetime.
Additionally, using the annual gift tax exclusion allows individuals to give away a certain amount per recipient (currently $18,000 as of 2024) without triggering gift taxes or utilizing their lifetime estate tax exemption. This proactively reduces the size of your taxable estate.
The Importance of Timing and Location
Tax avoidance is often a matter of “when” and “where.” By controlling the timing of your income and expenses, and being mindful of your geographic location, you can exert significant control over your total tax burden.
Year-End Tactical Planning
As the calendar year draws to a close, high-net-worth individuals often engage in “income shifting” or “deduction bunching.” If you expect to be in a lower tax bracket next year, you might delay sending out invoices until January. Conversely, if you want to lower this year’s bill, you might prepay certain expenses—like your January mortgage payment or a charitable contribution—to pull those deductions into the current tax year.
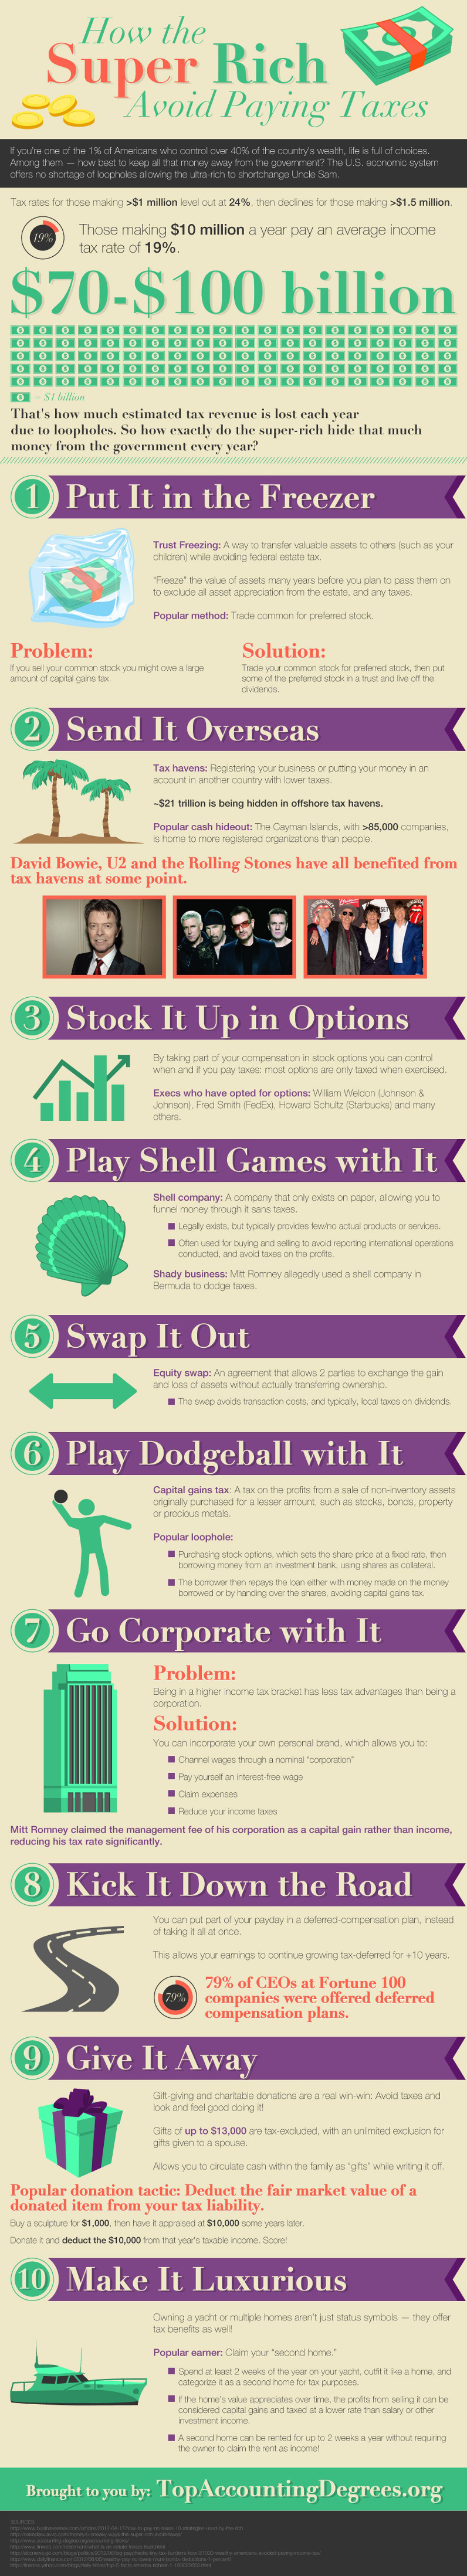
Charitable giving is another powerful year-end tool. By utilizing a Donor-Advised Fund (DAF), you can contribute a large sum today, receive an immediate tax deduction, and then distribute those funds to charities over several years.
Geographic Arbitrage
Finally, the state in which you reside or operate your business plays a massive role in your total tax liability. Several U.S. states—including Florida, Texas, Nevada, and Washington—levy no state income tax. For high earners, moving from a high-tax state like California or New York to a no-income-tax state can result in an immediate 5% to 13% “raise” in take-home pay. While lifestyle factors are always a consideration, the financial impact of geographic arbitrage is one of the most direct ways to avoid a substantial portion of your annual tax bill.
In conclusion, legal tax avoidance is not about finding loopholes or cutting corners; it is about making informed, strategic decisions that align with the incentives built into the financial system. By maximizing retirement contributions, managing investments with an eye toward tax efficiency, leveraging business deductions, and utilizing real estate advantages, you can significantly reduce your tax liability and accelerate your journey toward financial independence.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.