
For the majority of households, a vehicle represents the second-largest purchase after a home. However, unlike real estate, which generally appreciates over time, a car is a depreciating asset that requires a nuanced financial approach to manage effectively. Understanding how to find car value is not merely a task for those looking to sell or trade in a vehicle; it is a fundamental component of personal finance management. Accurate valuation informs your net worth calculations, influences your insurance premiums, dictates your borrowing power, and helps you time the market for a strategic exit or upgrade.
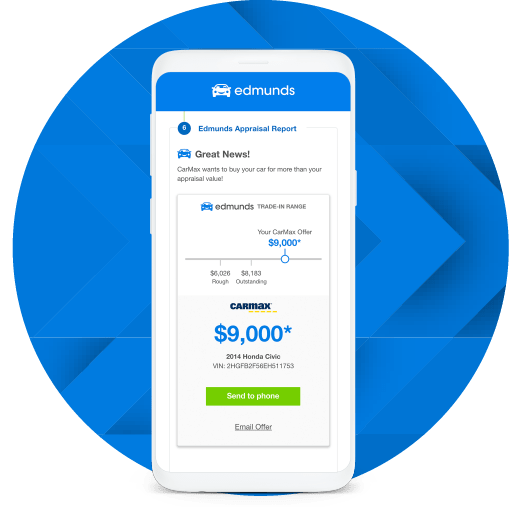
In a volatile economic landscape where supply chain disruptions and shifting interest rates have fundamentally altered the used car market, relying on a single “gut feeling” or an outdated estimate is a financial risk. To truly understand what your vehicle is worth, you must look through the lens of market data, depreciation curves, and financial tools.
The Financial Implications of Vehicle Valuation
Before diving into the “how,” it is essential to understand the “why” from a wealth management perspective. A car is not just a mode of transportation; it is a line item on your balance sheet that fluctuates daily.
Understanding Depreciation and Net Worth
Depreciation is the silent killer of wealth. Most new cars lose approximately 20% of their value in the first year and roughly 60% after five years. For individuals tracking their net worth, failing to account for this decline leads to an inflated sense of financial health. By regularly finding your car’s current value, you can adjust your personal balance sheet to reflect reality. This practice is particularly vital for those who use “gap insurance” or have high-interest auto loans, as it helps identify if you are “underwater”—meaning you owe more on the car than it is worth. Knowing this value allows you to make informed decisions about whether to make extra principal payments to reach equity faster.
Optimizing Insurance and Tax Liabilities
Your car’s value directly impacts your insurance costs. If your vehicle has depreciated significantly, you may be overpaying for comprehensive and collision coverage. Many financial advisors suggest that once a car’s value drops below a certain threshold—often ten times the cost of the insurance premium—it may be financially savvy to reduce coverage to liability only. Furthermore, in many jurisdictions, vehicle property taxes are based on the current market value. If the local tax assessor overvalues your vehicle, providing documented proof of a lower market value through reputable valuation tools can save you hundreds of dollars annually.
Navigating Professional Valuation Tools and Metrics
The digital age has democratized access to the same data sets once reserved for dealership managers and auction houses. However, not all valuation tools are created equal, and each serves a specific financial purpose.
Decoding KBB, NADA, and Black Book
To find car value accurately, you must understand the “Big Three” of automotive data:
-
Kelley Blue Book (KBB): Perhaps the most consumer-friendly tool, KBB is excellent for establishing a baseline for “Private Party Value.” It uses a proprietary algorithm that considers regional trends and consumer demand. However, it is often criticized for being slightly optimistic, which is beneficial for sellers but requires caution for buyers.
-
NADAguides (J.D. Power): The National Automobile Dealers Association (NADA) data is the gold standard for lenders. When you apply for an auto loan or look to refinance, the bank is likely using NADA values to determine the Loan-to-Value (LTV) ratio. NADA values tend to lean toward the “Retail Value,” reflecting what a dealer would ask on the lot.
-
Black Book: This is the tool of choice for dealerships and professional wholesalers. It focuses heavily on weekly auction data, providing a “Wholesale” or “Trade-In” value. It is often the most conservative of the three because it reflects what a professional is willing to pay to ensure a profit margin upon resale.
The Role of Real-Time Auction Data
In a rapidly shifting economy, traditional guides can sometimes lag behind real-world prices. For enthusiast vehicles, luxury cars, or rare models, digital auction platforms like Bring a Trailer or Cars & Bids provide a more accurate “real-time” valuation. These platforms show what actual buyers are paying in an open market today. From a financial planning perspective, reviewing “Sold” listings on these sites provides a transparency that algorithmic tools cannot match, especially when market volatility is high.

Factors Influencing Market Price in the Current Economy
Finding your car’s value is not a static calculation. Several external economic factors can cause the value of your asset to swing by thousands of dollars within a single quarter.
Supply Chain Dynamics and Interest Rates
The most significant driver of used car values in recent years has been the availability of new car inventory. When new car production slows due to semiconductor shortages or labor strikes, the demand for used cars skyrockets, driving up values across the board. Conversely, as interest rates rise, the cost of financing a vehicle increases. This reduces the pool of eligible buyers and puts downward pressure on car values. When assessing your car’s value, you must consider the current federal interest rate environment; high rates generally mean your car is harder to sell at a premium price.
Regional Variance and Seasonal Trends
Geography plays a massive role in valuation. A rear-wheel-drive convertible has a much higher value in Miami during February than it does in Minneapolis. Similarly, a four-wheel-drive SUV commands a premium in mountainous or snowy regions. Financial tools often ask for your zip code for this very reason.
Additionally, seasonality affects liquidity. Convertibles and sports cars peak in value during the spring and summer, while trucks and SUVs often see a value bump in the autumn. From an investment perspective, the best time to “find” value is when you are selling into a high-demand season and buying during a low-demand period.
Strategic Asset Management: Maximizing Resale and Trade-In
Once you have identified the market value of your vehicle, the next step in sound financial management is taking proactive steps to protect and enhance that value.
Documenting Service History for Premium Pricing
In the world of personal finance, documentation is everything. A car with a meticulously documented service history can command a 10% to 15% premium over an identical model with no records. This is because a paper trail reduces the risk for the next buyer, effectively lowering their “expected cost of ownership.” Using digital tools to track every oil change, brake job, and tire rotation ensures that when you finally go to capture the value of your asset, you have the proof necessary to justify a “Top Tier” or “Excellent” condition rating.
The Cost-Benefit of Pre-Sale Reconditioning
When finding car value, you will often see different tiers: Fair, Good, Very Good, and Excellent. Moving a car from “Fair” to “Good” through minor cosmetic repairs—such as PDR (Paintless Dent Repair) or a professional detail—often yields a 2x to 3x return on investment. If a $200 professional detail adds $600 to the private party value, it is a high-yield financial move. However, one must be careful not to over-capitalize; spending $2,000 on a new paint job for a car worth $5,000 is a poor allocation of capital.

Conclusion: Integrating Car Value into a Holistic Financial Plan
Finding your car’s value is more than a curiosity; it is a discipline. By utilizing a combination of algorithmic tools like KBB, lender-focused data from NADA, and real-time market trends from auction sites, you gain a clear-eyed view of your financial standing.
In the broader context of personal finance, your vehicle should be managed with the same rigor as a stock portfolio or a retirement account. This means tracking its depreciation, timing its replacement to avoid the “maintenance cliff” where repair costs exceed the vehicle’s value, and understanding how its equity contributes to your overall wealth. Whether you are looking to liquidate the asset for a down payment on a home, or simply want to ensure you are not over-insured, knowing the precise value of your car is an essential skill for the financially literate individual. In the end, a car is a tool for mobility, but its value is a tool for financial freedom.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.