
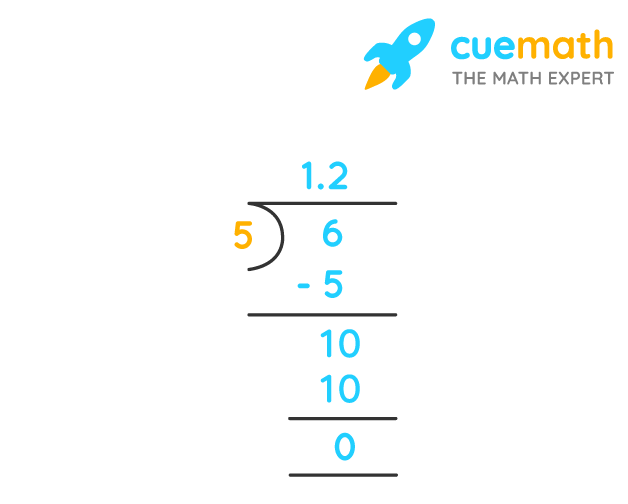
The direct answer to “what’s 1/5 as a decimal?” is 0.2. While seemingly a straightforward mathematical conversion, understanding how to fluidly move between fractions, decimals, and percentages is not merely an academic exercise; it forms a critical bedrock for astute financial decision-making, whether managing personal budgets, evaluating investments, or comprehending broader economic trends. In the realm of money, numerical fluency transforms raw data into actionable insights, empowering individuals and businesses to navigate complex financial landscapes with greater confidence and precision.
The Foundational Role of Decimals in Personal Finance
Mastering the conversion of fractions to decimals, such as 1/5 to 0.2, is more than just basic arithmetic; it’s a fundamental step towards achieving true financial literacy. Financial decisions, from the mundane to the monumental, are invariably rooted in numbers that represent proportions, rates, and values. Without a solid grasp of how these numerical forms interrelate, individuals risk misinterpreting critical financial information, leading to suboptimal choices or missed opportunities.
Understanding Basic Financial Conversions
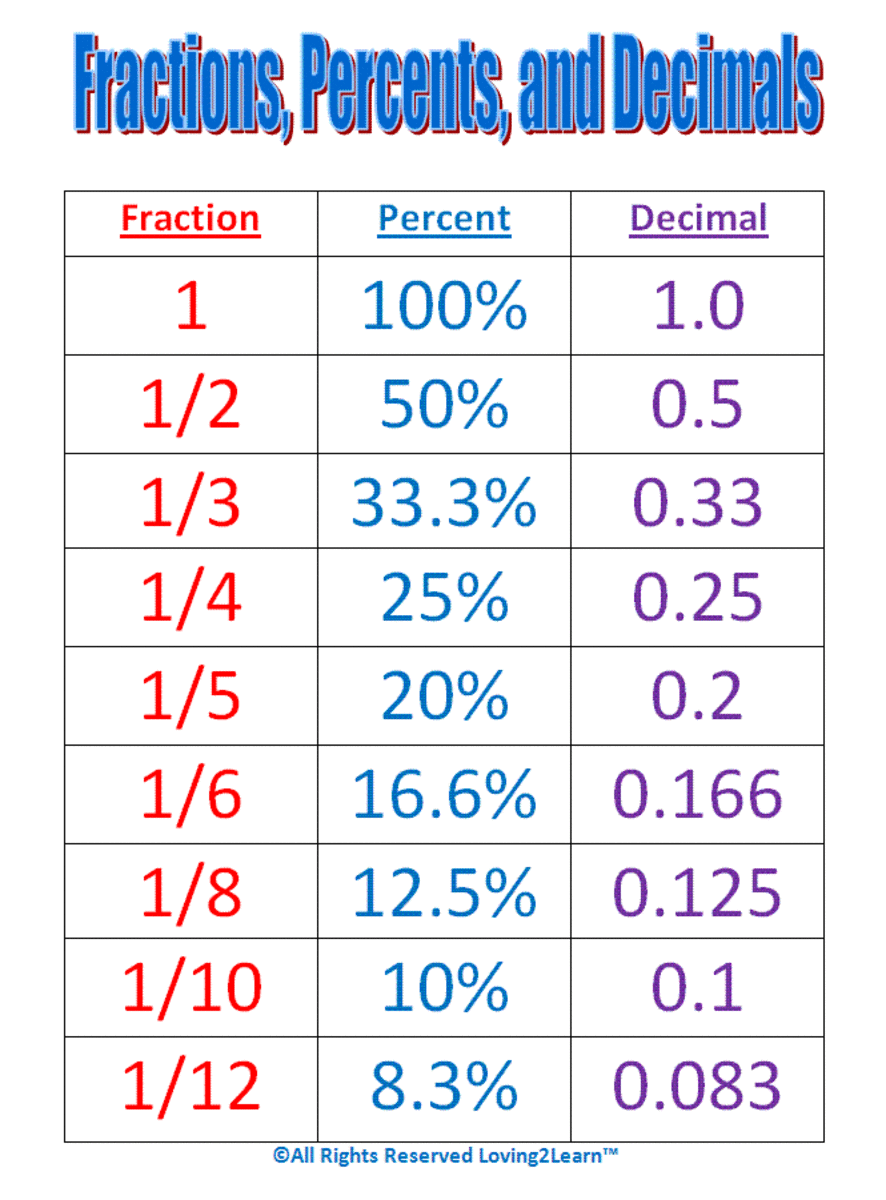
Financial concepts are rarely presented solely in one numerical format. Interest rates are often percentages (e.g., 5%), but when calculated, they become decimals (0.05). Shares in a company might be expressed as a fraction of total ownership (e.g., “owning 1/5 of the startup”), which is most meaningfully interpreted as a decimal (0.2) or a percentage (20%) for comparison and calculation. Understanding that 1/5, 0.2, and 20% are simply different representations of the same underlying proportion is essential. This fluidity allows for rapid comparison of different financial products, assessment of investment returns, and accurate budgeting. For instance, a discount advertised as “1/5 off” is immediately recognizable as a 20% reduction when you translate it to its decimal equivalent.
From Fractions to Percentages: The Bridge to Financial Clarity
The journey from a fraction to a decimal, and then often to a percentage, creates a bridge to clearer financial understanding. Percentages are the language of finance, used to describe everything from investment returns and loan interest rates to inflation figures and budget allocations. When you understand that 1/5 equals 0.2, you inherently grasp that it also equals 20%. This conversion skill is invaluable when allocating assets in an investment portfolio. If an advisor recommends dedicating “1/5 of your portfolio to emerging markets,” translating this to 20% immediately helps visualize the proportion relative to other asset classes, making the overall strategy more tangible and easier to analyze. Similarly, when assessing the contribution rates to a retirement fund, seeing that you are contributing “1/5 of your paycheck” immediately quantifies that commitment as 20% of your earnings.
Calculating Proportions and Shares: Applying Decimal Knowledge
The ability to convert fractions to decimals becomes acutely relevant when dealing with financial proportions and shares, whether in personal budgeting or more complex investment scenarios. It enables precise calculations and informed comparisons.
Investment Portfolios and Asset Allocation
In investment management, decimals are indispensable for understanding asset allocation. A diversified portfolio often comprises various asset classes like stocks, bonds, real estate, and commodities. An investment strategy might dictate that “1/5 of your capital should be in bonds.” This translates directly to 0.2, or 20%, of your total investment. Calculating the exact monetary value of this allocation requires decimal understanding (e.g., 0.2 * $100,000 portfolio = $20,000 in bonds). Furthermore, tracking performance involves comparing the percentage gain or loss of each segment, where decimal conversion is inherent in the calculation. If one stock represents 1/50th of your portfolio, understanding this as 0.02 or 2% allows for a clearer perspective on its impact on overall portfolio volatility and returns.
Budgeting and Expense Ratios
Personal budgeting is another area where decimals shine. Many financial advisors suggest allocating specific percentages of income to different categories: housing, food, savings, entertainment, and debt repayment. If a common rule of thumb is to spend no more than “1/5 of your net income on housing,” converting this to 0.2 helps quantify that limit precisely. For someone earning $5,000 a month, 0.2 * $5,000 = $1,000. This decimal calculation provides the concrete dollar amount, allowing for practical comparison against actual expenses. Similarly, calculating your savings rate or determining what percentage of your income goes towards discretionary spending relies heavily on converting income and expenditure figures into ratios and then into decimals or percentages.
Ownership Stakes and Business Equity
In business, understanding ownership stakes often begins with fractions. A founder might grant a partner “1/5 ownership” of a new venture. Translating this to 0.2 or 20% is crucial for understanding profit distribution, voting rights, and eventual valuation. When a company is sold, the proceeds are distributed based on these fractional or decimal ownership stakes. For example, if a business sells for $1 million, a 0.2 ownership stake means $200,000. These calculations are fundamental for any entrepreneur or investor involved in startups and private equity.
Decimals in Investment Analysis and Performance
Beyond basic allocations, decimals are the standard language for detailed investment analysis, allowing for accurate comparisons and projections.
Interpreting Stock Prices and Dividends
Stock prices are almost always quoted in decimals, reflecting fractional cents (e.g., $150.25). Dividend yields, which are crucial for income-focused investors, are calculated as a percentage (dividend per share / stock price), inherently involving decimals. If a company pays a $1.00 annual dividend and its stock trades at $50.00, the yield is $1.00/$50.00 = 0.02, or 2%. Understanding these decimal conversions allows investors to compare the income potential of different stocks. Stock splits, where one share becomes multiple shares (e.g., a 1-for-5 reverse split means 5 shares become 1), directly alter the per-share price and require decimal understanding to calculate the new share price.
Understanding Interest Rates and Loan Calculations
Interest rates for loans, mortgages, and savings accounts are almost universally expressed as percentages, which are effectively decimals in disguise during calculations. An Annual Percentage Rate (APR) of 5% on a loan translates to a decimal factor of 0.05 in payment and interest accrual formulas. Calculating monthly mortgage payments, the total interest paid over the life of a loan, or the effective annual yield on a savings account all rely on converting these percentage rates into their decimal equivalents for precise computation. Missing the slight difference between a 1/8th of a percent reduction in a mortgage rate (0.00125 as a decimal) can translate to thousands of dollars over the loan’s term.
Analyzing Returns and Growth Rates
Whether evaluating the Return on Investment (ROI) for a project or the compound annual growth rate (CAGR) of an investment, decimals are the operational numbers. If an investment yields a 1/5 return, that’s a 0.2 (or 20%) gain. Comparing an investment with a 0.2 return to one with a 0.18 return is a direct decimal comparison that clearly indicates which performed better. Compound interest formulas, the bedrock of long-term wealth accumulation, are fundamentally built upon decimal representations of interest rates and time periods, demonstrating the profound impact of even small decimal differences over extended durations.
Practical Applications: Leveraging Decimal Proficiency for Financial Decisions
The practical benefits of strong decimal proficiency permeate every aspect of personal and business finance, from mundane comparisons to complex strategic planning.
Comparing Financial Products
When comparing savings accounts, certificates of deposit (CDs), or different bond offerings, their yields are almost always presented as percentages or decimal rates. A bank might offer a savings account with a 0.05% Annual Percentage Yield (APY) while another offers 0.049%. Without understanding decimals, these minuscule differences might seem insignificant, but over large sums and long periods, they can add up. Similarly, comparing fees that are a “fraction of the transaction value” or “a fixed decimal percentage” requires this conversion skill to determine the true cost.
Managing Debt Effectively
Effective debt management hinges on understanding the decimal implications of interest rates and repayment schedules. Minimum payments are often calculated as a small percentage (decimal) of the outstanding balance plus accrued interest. Understanding that a high-interest credit card charges, for example, 1/5 of a percent daily interest translates to 0.002 per day, which quickly compounds. This knowledge empowers individuals to prioritize higher-interest debts and understand the true cost of carrying balances, motivating them to accelerate payments and reduce the overall financial burden.
Strategic Tax Planning
Tax planning involves navigating various rates, deductions, and credits, many of which are expressed as percentages or decimal factors. Tax brackets define what percentage (decimal) of income falls into different taxation levels. Understanding how deductions and credits reduce taxable income, often as a percentage, helps individuals and businesses optimize their tax liabilities. For instance, a tax credit worth “1/5 of an eligible expense” means a direct reduction of 0.2 times the expense from the tax bill, a significant saving that requires decimal conversion to fully appreciate and utilize.
Beyond the Basics: Advanced Financial Concepts Rooted in Decimals
Even the most sophisticated financial models and economic theories are built upon the foundational understanding of decimals.
Understanding Inflation and Purchasing Power
Inflation, the rate at which the general level of prices for goods and services is rising, and subsequently, purchasing power is falling, is always measured in percentages (decimals). An inflation rate of 3% (0.03) means that what $100 bought last year now costs $103. Understanding how future values are eroded by inflation, often over multiple years, necessitates decimal-based calculations of compound inflation, impacting retirement planning and long-term investment strategies.
Discount Rates and Present Value Calculations
In corporate finance and investing, the concept of present value is paramount. It involves discounting future cash flows back to their current value using a discount rate, which is always a decimal percentage. For example, if you expect to receive $100 in one year and your discount rate (representing the time value of money or required return) is 1/5, or 20% (0.2), then the present value of that $100 is $100 / (1 + 0.2) = $83.33. This calculation is fundamental to valuing businesses, projects, and investments, demonstrating how even complex financial valuation is ultimately rooted in basic decimal operations.
Risk Assessment and Diversification Ratios
Quantifying financial risk, such as volatility or standard deviation, involves intricate statistical calculations where decimals are the core components. Furthermore, diversification strategies often involve maintaining specific ratios or percentages of different assets to mitigate risk. Maintaining “1/5 of a portfolio in low-risk government bonds” translates to a 0.2 allocation, a strategic decision underpinned by decimal understanding to balance potential returns against acceptable risk levels.
In essence, while “1/5 as a decimal” is a simple arithmetic problem with the answer 0.2, its implications for managing, growing, and understanding money are vast. From budgeting and investment to advanced financial analysis, the ability to effortlessly convert and interpret numbers in decimal form is an indispensable skill, empowering financial intelligence and better decision-making in an increasingly complex financial world.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.