
The question “what is half of 3 1/2” appears deceptively simple, a relic from elementary arithmetic. Solved directly, half of 3 1/2 (or 3.5) is 1 3/4 (or 1.75). However, within the intricate landscape of personal finance, investing, and business operations, this seemingly basic calculation serves as a powerful metaphor and a foundational skill. Understanding how to divide, proportion, and manage fractional amounts is not merely an academic exercise; it is an indispensable component of sound financial decision-making, impacting everything from investment allocations to profit sharing and expense management. This article delves into the various applications of such fundamental division within the financial world, demonstrating why mastering simple arithmetic principles is crucial for navigating complex monetary scenarios.
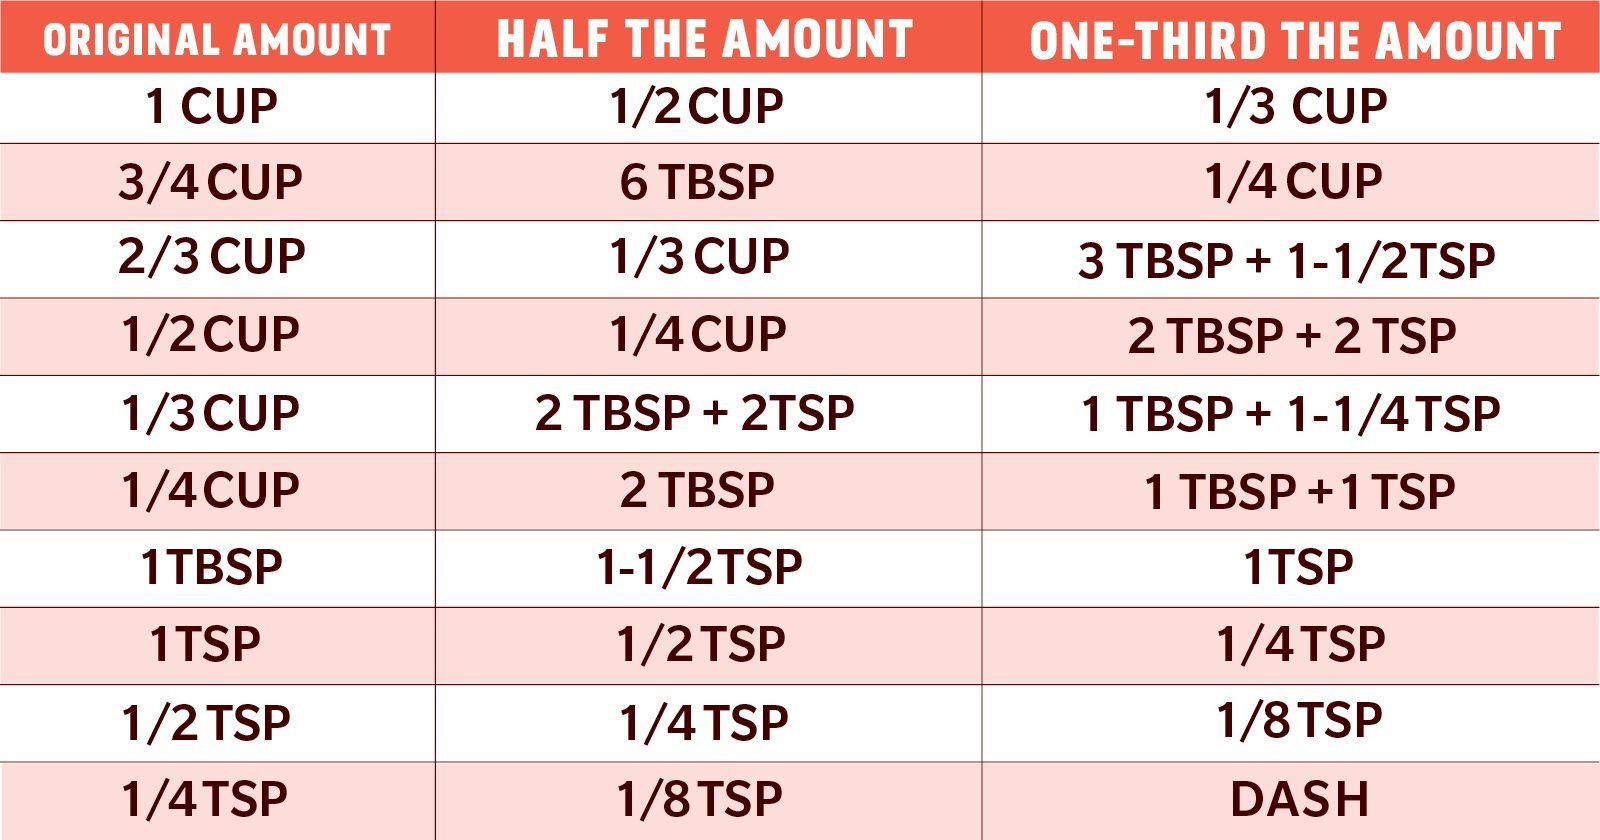
Decoding “Half of 3 1/2”: A Fundamental Financial Concept
At its core, “half of 3 1/2” represents a proportional division, a concept that permeates every facet of finance. Whether it’s splitting a profit, allocating a budget, or calculating interest, the ability to accurately divide quantities is non-negotiable. The answer, 1.75 or 1 3/4, is a precise outcome that, when applied to financial contexts, dictates equitable distribution, informs strategic planning, and ensures transparency. This simple problem underscores the broader necessity of numerical fluency in managing personal and business finances effectively.
The Primal Role of Division in Wealth Management
Every major financial decision, from constructing a diversified portfolio to planning for retirement, involves proportional reasoning. Wealth management isn’t about accumulating a single lump sum; it’s about strategically dividing and allocating resources across various asset classes, risk profiles, and time horizons. The concept of “half” is just one manifestation of division, but it highlights the necessity of breaking down larger financial figures into manageable, actionable components. For instance, an investor might decide that half of their portfolio should be in equities, with the other half split between bonds and alternative investments. Without a firm grasp of such divisions, strategic allocation becomes guesswork, leading to suboptimal returns or increased risk exposure. Similarly, when inheriting an estate, beneficiaries often need to divide assets, sometimes in precise fractional shares, making accurate calculation critical for fairness and legal compliance.
From Basic Arithmetic to Complex Financial Modeling
The transition from calculating half of 3 1/2 to constructing sophisticated financial models might seem vast, but the underlying principles remain constant. Complex financial instruments, derivatives, and algorithmic trading strategies are built upon layers of arithmetic operations, including division, multiplication, and percentages. Understanding the granular impact of these operations begins with mastering the basics. Financial analysts frequently use fractions and decimal equivalents to project growth rates, discount cash flows, and assess valuations. For example, a company might project earnings growth of “3 1/2 percent” annually, and a partial-year forecast would require calculating “half” of that annual projection. These calculations, while performed by software, demand human comprehension of the inputs and expected outputs, ensuring that the models accurately reflect real-world financial dynamics.
Strategic Division: Applying Halves to Investments and Assets
The direct application of dividing assets or returns into halves, or more complex fractions, is a cornerstone of investment strategy and business operations. From portfolio diversification to equitable profit distribution, the principle of division ensures balance, fairness, and risk mitigation.
Portfolio Allocation and Risk Diversification
Investors routinely face decisions about how to allocate their capital across various investments. A common strategy involves dividing investments to mitigate risk and optimize returns. For example, an investor might aim to have 3.5% of their total investment capital dedicated to a specific emerging market fund. If they decide to rebalance and only commit half of that initially, they are directly applying the “half of 3 1/2” principle. This approach allows for gradual entry into volatile markets or testing new investment hypotheses without full commitment. Furthermore, diversified portfolios inherently involve dividing investments across different asset classes—equities, bonds, real estate, commodities—each representing a distinct fraction of the total portfolio, designed to achieve specific risk-return objectives.
Partnership Equity and Profit Distribution
In business partnerships, joint ventures, or co-owned assets, the concept of dividing quantities is fundamental to operations and dispute resolution. Imagine a small business where three partners own 3 1/2 units of a key asset (e.g., intellectual property units, equipment shares). If one partner wishes to sell half of their stake, the calculation “half of 3 1/2” becomes immediately relevant for determining the new ownership structure and potential buy-out value. Similarly, profit distribution clauses often involve complex fractions or percentages. If a partnership generates a profit and one partner is entitled to a specific fraction of that profit, the ability to perform such divisions accurately ensures equitable compensation and maintains business harmony. Disputes often arise from miscalculations or a lack of clarity in fractional ownership or distribution, underscoring the importance of precise arithmetic.
Budgeting, Expenses, and Interest: The Everyday Application of Proportions
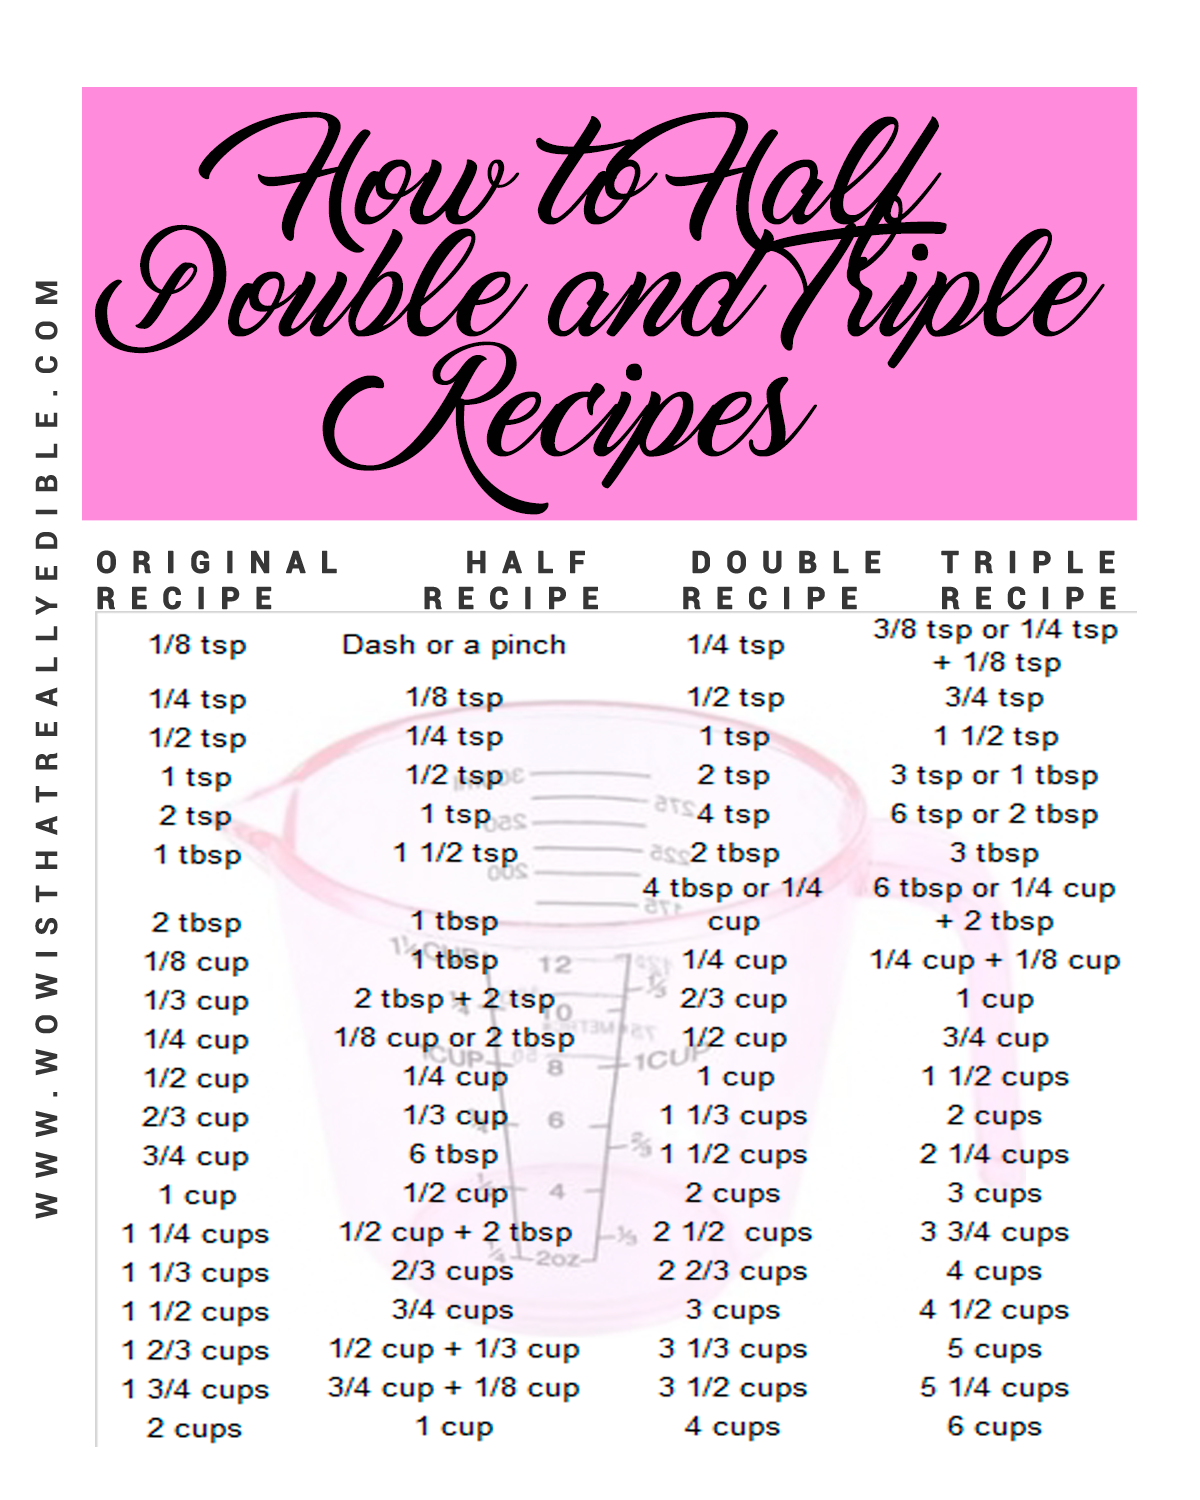
Beyond large-scale investments and business ventures, the principle of proportional division manifests in the daily management of personal finance. From sharing household expenses to understanding loan interest, accurate fractional calculations are essential for maintaining financial health and making informed spending decisions.
Halving Debts and Accelerating Repayments
Strategic debt management often involves proportional thinking. While not directly “half of 3 1/2,” the concept of allocating portions of income to debt repayment is critical. For instance, if an individual is advised to dedicate an extra 3.5% of their monthly income towards an accelerated debt repayment plan, deciding to commit “half” of that recommended additional amount to a specific high-interest loan requires a proportional calculation. This approach can help individuals chip away at their obligations faster, reduce interest paid over time, and free up cash flow sooner. Understanding how to divide a total debt burden into manageable chunks or how to proportionally increase payments on specific loans can significantly impact one’s financial freedom.
Understanding Half-Yearly or Quarterly Financial Obligations
Many financial products and obligations are structured around periods less than a full year. Bonds may pay interest semi-annually (half-yearly), mortgages might have quarterly reviews, and certain subscriptions or insurance premiums are billed bi-annually. If an annual interest rate is 3 1/2%, understanding that a semi-annual payment would effectively be half of that annual rate (though actual calculations involve more complex interest formulas, the initial proportional understanding is key) is crucial for budgeting. For instance, if a company reports an annual profit of X, and quarterly dividends are declared, the dividend per share is a fraction of the total annual profit, requiring precise division to determine individual shareholder payouts. This attention to periodic divisions ensures that individuals and businesses accurately forecast cash flows and manage liquidity.
Budgeting for Shared Household or Business Expenses
The most common everyday application of proportional division comes in managing shared expenses. Whether it’s roommates splitting rent and utilities, or business partners dividing operational costs, the ability to accurately calculate fractional contributions is paramount. If three individuals share a utility bill that typically averages $350 (or 3.5 units of $100), and one person agrees to pay half of that specific share due to a specific arrangement, the calculation of “half of 3 1/2” (in terms of hundreds of dollars) becomes a direct, practical application. Such divisions extend to shared streaming services, groceries, and travel expenses, where precise calculations prevent misunderstandings and foster equitable financial relationships.
Beyond the Calculator: Leveraging Technology for Financial Precision
While the calculation “half of 3 1/2” is easily done mentally or with a basic calculator, the real-world financial applications of such divisions often involve larger numbers, more complex fractions, and iterative processes. This is where modern financial tools and technologies become indispensable for ensuring precision, efficiency, and insight.
Spreadsheets as Dynamic Financial Division Tools
Spreadsheets like Microsoft Excel or Google Sheets are the backbone of personal and business financial management. They transform simple arithmetic into powerful analytical tools. For tasks involving proportional division, spreadsheets excel. An investor can easily set up a sheet to calculate half of 3.5% of their total portfolio value, or a business owner can model profit distributions based on varying fractional ownership percentages. Formulas automatically update with new inputs, allowing for dynamic scenario planning and accurate financial forecasting. This capability moves beyond a single, static calculation to provide a comprehensive, adaptable framework for managing financial divisions across multiple variables and over time.
Automated Financial Platforms and AI in Asset Management
The advent of automated financial platforms and Artificial Intelligence (AI) has revolutionized how complex financial divisions are handled. Robo-advisors, for example, leverage AI to automate portfolio rebalancing, ensuring that investment allocations remain at their target fractional percentages without manual intervention. These systems can dynamically adjust holdings to maintain a 3.5% allocation in a specific sector, for instance, and if a decision is made to halve that exposure, the AI can execute the trades efficiently and accurately. Similarly, AI-powered budgeting apps can automatically categorize expenses and allocate income into various “pots” or fractional percentages, helping users manage shared expenses or savings goals with unprecedented precision, often performing hundreds of proportional calculations in the background.

The Human Element: Verifying Calculations and Strategy
Despite the sophistication of technological tools, the human element remains critical. While software can perform calculations with speed and accuracy, the strategic decisions—whether to take half of a profit, reduce a stake by 3 1/2 percent, or reallocate half of a specific investment—are human judgments. Financial literacy, beginning with an understanding of basic arithmetic operations like division and fractions, empowers individuals to critically evaluate the outputs of financial tools, challenge assumptions, and make informed strategic choices. The question “what is half of 3 1/2” isn’t just about the answer; it’s about the fundamental thinking process that underpins intelligent financial management, a process that even the most advanced AI cannot fully replicate without human guidance and oversight.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.