
At first glance, the question “what is 7 in fraction form?” appears to be a basic arithmetic query, a relic from elementary school mathematics. However, beneath its simple exterior lies a fundamental concept that underpins much of personal finance, investing, and business operations. Understanding how a whole number can be expressed as a fraction—and, more broadly, the power of proportional thinking—is not merely academic; it is an indispensable tool for financial literacy, strategic allocation, and wealth management. In the realm of money, virtually every calculation, from budgeting your income to diversifying your investment portfolio, relies on grasping the relationship between a whole and its constituent parts.
The Foundation of Financial Proportions: From Whole Numbers to Actionable Insights
The transformation of a whole number into a fraction is the bedrock of understanding financial proportions. It teaches us how to break down complex financial scenarios into digestible, quantifiable parts, enabling more informed decision-making.
Understanding “7/1”: The Simplest Fraction and Its Profound Implications
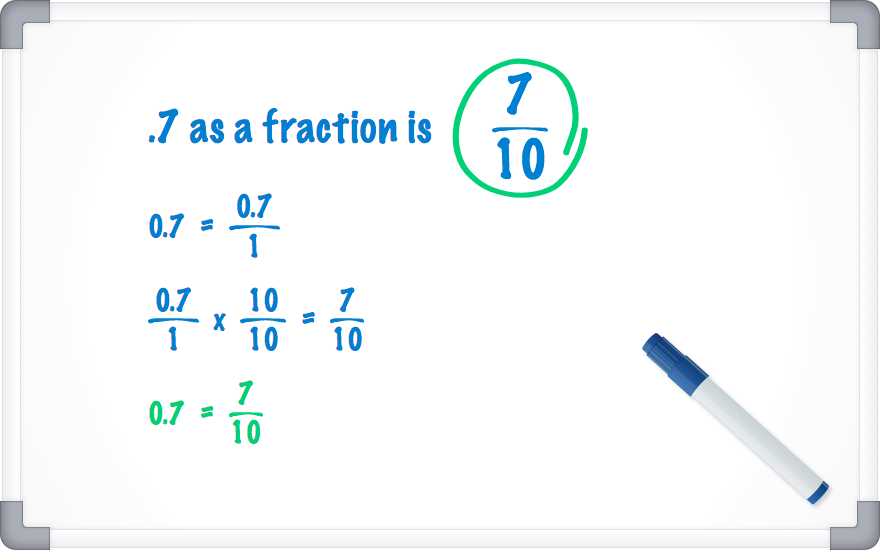
The most straightforward answer to “what is 7 in fraction form?” is 7/1. This means seven divided by one, or seven wholes. While seemingly trivial, this representation is profoundly significant in finance. It establishes the concept of a single, undifferentiated whole as the starting point for all subsequent division and allocation.
Consider your monthly income. Before you allocate it to various expenses, savings, or investments, it exists as a single whole—let’s say $7,000. Expressing this as $7,000/1 emphasizes its status as the entire pool of funds available for distribution. This seemingly obvious step is critical because it mentally sets the stage for slicing this whole into percentages, ratios, and fractions, which are the language of financial planning. It’s the baseline from which all fractional deductions or additions will be made.
Beyond the Obvious: When the Whole Takes Different Forms
While 7/1 is the simplest representation, a whole number can be expressed in countless equivalent fraction forms, such as 14/2, 21/3, or even 700/100. Each of these fractions still equals 7. This mathematical principle has direct parallels in finance, illustrating how the same financial value or proportion can be represented in different ways, depending on the context or the desired level of granularity.
For instance, owning a 1/7th share of a company is mathematically equivalent to owning 100/700ths of that same company. The absolute numbers change (1 share versus 100 shares), but the underlying proportional ownership remains the same. Understanding equivalent fractions allows investors to recognize that differing nominal values can represent identical true proportions, a crucial insight when evaluating stock splits, reverse splits, or comparing different investment vehicles. It also highlights how a budget might allocate 1/7th of income to savings, which is the same as allocating approximately 14.28% (14.28/100). The form changes, but the impact on the whole remains constant.
Fractions in Personal Finance: Budgeting and Resource Allocation
The principles of fractions are not abstract concepts when it comes to managing personal finances; they are the very tools through which we achieve financial stability and growth.
Budgeting as Fractional Division of Your Income
Your monthly income is the “whole,” and every expense, saving contribution, and debt payment represents a fraction of that whole. Budgeting is, at its core, the deliberate act of dividing your total income into various fractional allocations.
Consider the popular 50/30/20 rule, which advises allocating 50% of your income to needs, 30% to wants, and 20% to savings and debt repayment. This is a direct application of fractional thinking:
-
Needs: 1/2 of your income (or 50/100)
-
Wants: 3/10 of your income (or 30/100)
-
Savings & Debt: 1/5 of your income (or 20/100)
By conceptualizing your budget in fractional terms, you gain a clearer understanding of how each spending category impacts your overall financial health. It moves beyond simply tracking dollars and cents to understanding the proportion of your resources dedicated to different purposes. This proportional view allows for easier adjustments and ensures that no single category disproportionately consumes your income, jeopardizing your financial goals.
Saving Goals and Fractional Progress Towards the Whole
Saving for a down payment, a child’s education, or retirement can feel overwhelming when viewed as a single, monumental sum. However, by breaking down these goals into smaller, manageable fractions, the path becomes clearer and more attainable. If you need to save $70,000, and you decide to save $7,000 each year, you are effectively saving 1/10th of your goal annually (or 7,000/70,000).
Each deposit, however small, represents an accumulated fraction of your ultimate target. Visualizing your savings progress as the gradual accumulation of fractions towards a complete whole provides motivation and a tangible sense of achievement. It transforms an intimidating lump sum into a series of achievable, fractional steps. This same thinking applies to debt reduction: each payment reduces a fraction of the total principal owed, inching you closer to zero.
Investing and Ownership: Equity as Fractions of Enterprise
In the world of investing, fractions move from personal budgeting to the ownership of assets and the strategic diversification of wealth.
Stock Ownership: A Fraction of a Company
When you purchase a single share of a company’s stock, you are acquiring a minute, yet real, fraction of that company’s ownership. If a company has 7 million outstanding shares, and you own 7 shares, your ownership stake is 7/7,000,000. While this is a tiny fraction, it grants you proportional rights, such as a vote on company matters and a claim to a fraction of its earnings (dividends, if issued).
Understanding this fractional ownership is crucial for investors. It informs decisions about the significance of a stock split (where each share’s value is divided, but your fractional ownership remains the same, just represented by more shares of lower individual value) or the impact of issuing new shares (which dilutes your existing fractional ownership unless you purchase more). Investors often think of “a piece of the pie,” and that “piece” is precisely a fraction of the total enterprise.
Portfolio Diversification: Fractional Allocation Across Assets
Diversifying an investment portfolio is arguably one of the most critical applications of fractional thinking in finance. Your entire investment capital represents the “whole.” Strategic diversification involves dividing this whole into various asset classes—stocks, bonds, real estate, commodities, cash—each representing a specific fraction of your total portfolio.
For example, a common diversification strategy might involve allocating:
-
1/2 to equities (stocks)
-
1/4 to fixed income (bonds)
-
1/8 to real estate
-
1/8 to cash or alternative investments
This proportional distribution is designed to manage risk and optimize returns according to your financial goals and risk tolerance. As market values fluctuate, these fractions will naturally shift. The process of “rebalancing” your portfolio involves periodically adjusting these fractions back to your desired proportions, often by selling assets that have grown disproportionately large (exceeding their desired fraction) and buying those that have become too small. This continuous management of fractions is vital for maintaining a disciplined investment strategy.
Real Estate and Business Finance: Dividing Assets and Profits
The concept of fractions extends beyond individual finance into the complex realms of real estate ownership and business profit distribution.
Shared Ownership in Real Estate and Partnerships
Real estate often involves shared ownership, where multiple parties hold fractional interests in a single property. Whether it’s co-owning a vacation home, investing in a syndicated real estate deal, or holding property in a trust, each owner typically possesses an explicit fractional share (e.g., 1/2, 1/3, or 7/100). These fractions dictate not only the proportion of capital contributed but also the share of rental income, expenses, and capital gains or losses. Legal agreements meticulously define these fractional rights and responsibilities.
In business partnerships, capital contributions and profit-sharing agreements are almost always expressed in fractional or percentage terms. If two partners contribute uneven amounts of capital or expertise, their profit split might be, for example, 3/7ths to one partner and 4/7ths to the other. These fractions are not arbitrary; they reflect agreed-upon valuations of contributions and future expectations.
Business Profit Distribution and Equity Splits
For businesses, particularly startups, “equity splits” are a crucial application of fractions. Founders and early employees receive fractional ownership (shares) of the company, which represent their claim on future profits and company value. A founder who owns 7% of a company technically owns 7/100ths of its equity. As the company grows and raises capital, new investors might acquire fractions of the company, potentially diluting existing ownership, but always maintaining the principle that the sum of all fractional ownership must equal one whole. Understanding these dynamics is paramount for entrepreneurs seeking to secure funding and for employees evaluating compensation packages that include stock options or equity grants.
The Power of Proportional Thinking in Financial Decisions
Beyond specific calculations, the mental framework of proportional thinking—inherent in understanding fractions—empowers individuals to make more insightful financial decisions across the board.
Interest Rates and Fractional Growth
Interest rates, whether on loans or savings, are fundamentally fractional. An annual interest rate of 7% means that each year, you accrue 7/100ths of the principal amount. This simple fraction governs the exponential power of compounding interest. Understanding how small, consistent fractional gains (or losses, in the case of debt) accumulate over time is key to appreciating long-term wealth building or the long-term cost of borrowing. A savings account earning a fractional return, compounded over decades, can transform modest principal amounts into significant sums. Conversely, credit card interest, a high fraction of the outstanding balance, can quickly spiral if not managed.
Debt Management: Reducing the Burden Fraction by Fraction
Managing debt, whether a mortgage, student loan, or credit card balance, involves a persistent effort to reduce the “whole” amount owed. Each payment consists of two parts: a fraction that covers interest and another fraction that reduces the principal. Understanding these fractions allows borrowers to see how accelerating principal payments, even by small amounts, significantly alters the fractional composition of future payments, leading to substantial savings on interest over the life of the loan. It’s about systematically chipping away at the whole debt, one fraction at a time, until zero is reached.
In conclusion, the seemingly simple question “what is 7 in fraction form?” opens a gateway to fundamental financial understanding. From personal budgets and savings goals to complex investment strategies and business equity, the ability to conceptualize whole numbers as fractions and to engage in proportional thinking is an invaluable asset. It allows us to dissect financial challenges, optimize resource allocation, and strategically plan for a more secure and prosperous future.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.