
Understanding fundamental mathematical concepts like fractions is not merely an academic exercise; it forms a bedrock for practical financial literacy. In the intricate world of personal finance, investing, and business operations, the ability to comprehend and apply fractional values is paramount for making informed decisions. The fraction 2/3, while seemingly simple, serves as an excellent illustration of how basic numerical relationships translate into significant financial implications, from budgeting and savings to investment diversification and profit sharing.
The Financial Lens: Decoding 2/3 and its Numerical Significance
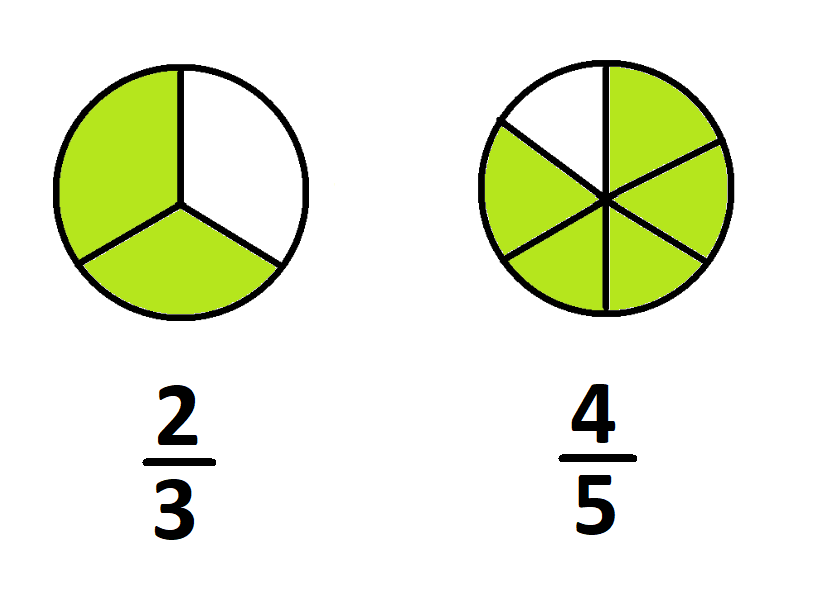
At its core, 2/3 represents two parts out of a total of three equal parts. In decimal form, this equates to approximately 0.6667, and as a percentage, it is roughly 66.67%. This foundational understanding is the first step in unlocking its relevance in financial contexts. Unlike integers, fractions introduce the concept of proportion and distribution, which are central to managing financial resources effectively.
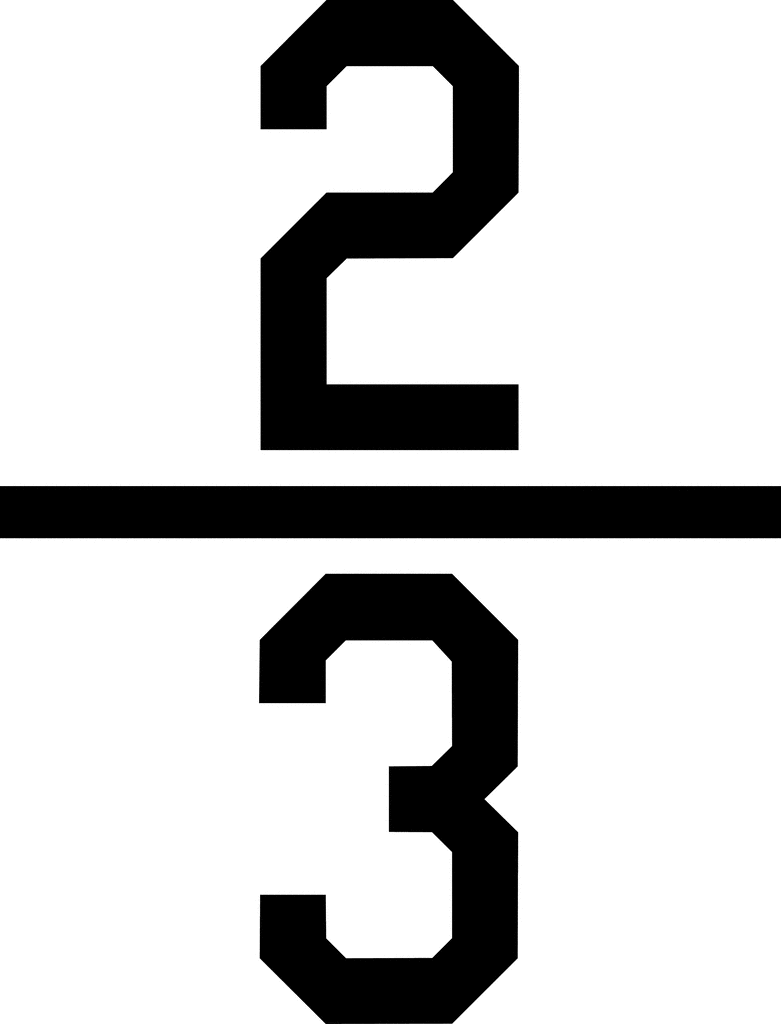
Deciphering the Numerator and Denominator in Money Matters
The numerator (2) and the denominator (3) in 2/3 each carry specific weight when applied to financial scenarios. The denominator often signifies the total amount or the whole entity being considered—be it total income, a complete investment portfolio, or an entire business venture. The numerator, conversely, denotes the specific portion or share of that whole that is being discussed or allocated.
For instance, if a business partner holds a 2/3 stake in a company, the ‘3’ represents the total ownership of the company, and the ‘2’ indicates the proportion of that ownership held by the specific partner. This immediately clarifies the power dynamic, profit distribution, and voting rights within the entity. Similarly, if 2/3 of a household’s income is allocated to essential expenses, the ‘3’ is the total monthly income, and the ‘2’ is the significant portion dedicated to non-negotiable costs, leaving only 1/3 for savings, investments, or discretionary spending. This simple breakdown provides immediate insight into financial health and areas for potential adjustment.
Visualizing 2/3: Real-World Financial Proportions
The ability to visualize 2/3 helps in quickly grasping financial scenarios without needing complex calculations. Imagine a pie chart representing your monthly budget: two out of three slices would be dedicated to a particular category. This mental model aids in quickly assessing distributions.
Consider a mutual fund where 2/3 of its assets are invested in equities, and the remaining 1/3 in bonds. This immediately communicates the fund’s risk profile and diversification strategy to a potential investor. A higher proportion in equities (2/3) suggests a more aggressive stance with greater potential for growth but also higher volatility, compared to a fund with an equal or lower equity allocation. This quick mental assessment, derived from understanding a simple fraction, empowers investors to align their choices with their personal risk tolerance.
2/3 in Personal Finance: Budgeting, Debt, and Consumer Decisions
The practical application of 2/3 extends across various facets of personal finance, offering a clear framework for managing income, expenditures, and consumer behavior.
Strategic Budgeting and Income Allocation
A common financial guideline, though not universally applicable, suggests allocating specific fractions or percentages of income to different categories. While the “50/30/20 rule” (50% needs, 30% wants, 20% savings/debt) is popular, variations often emerge where a significant portion like 2/3 might be dedicated to core living expenses. For example, if 2/3 of your net income goes towards rent, utilities, groceries, and transportation, it highlights a potentially tight budget, leaving only 1/3 for all other financial goals. Understanding this proportion helps individuals evaluate their spending habits and identify opportunities to optimize. If 2/3 of income is consistently consumed by fixed expenses, it signals a need to either increase income or reduce fixed costs to create more financial flexibility. This precise fractional understanding allows for clear financial goal-setting and corrective action.
Debt Management and Repayment Strategies
Fractions also play a critical role in understanding debt. Imagine a scenario where you’ve paid off 2/3 of a loan. This provides a clear picture of your progress and the remaining obligation. Knowing that only 1/3 of the principal remains can be a significant motivator, indicating that the bulk of the repayment is behind you. Conversely, if 2/3 of your income is allocated to debt repayments, this is a red flag, suggesting an unsustainable debt burden that requires immediate attention and restructuring. The 2/3 threshold here acts as a stark indicator of financial stress, prompting a re-evaluation of current financial strategies.
Understanding Discounts, Sales, and Value

Consumers frequently encounter fractions disguised as percentages in retail. A “2/3 off” sale, while less common than “33% off” or “66% off,” is conceptually identical. Knowing that 2/3 off means you pay only 1/3 of the original price can dramatically influence purchasing decisions. For a product originally priced at $90, a 2/3 discount means saving $60 and paying only $30. This quick mental conversion from fraction to actual monetary value is crucial for identifying genuine bargains and calculating the true cost of items during promotional periods, preventing impulse buys based solely on a “sale” label.
2/3 in Investment and Business Finance: Growth, Distribution, and Performance
Beyond personal finance, the fraction 2/3 finds extensive application in the realms of investing and business, guiding decisions related to asset allocation, partnership agreements, and financial analysis.
Portfolio Allocation and Diversification
Professional investors and financial advisors frequently use fractions and percentages to describe investment portfolios. A common recommendation for a growth-oriented portfolio might suggest that 2/3 of the assets be allocated to equities (stocks) and the remaining 1/3 to fixed income (bonds) or other less volatile assets. This 2/3 equity allocation signifies a strategy that prioritizes capital appreciation over stability, accepting higher risk for potentially greater returns. Understanding this fractional breakdown helps investors evaluate whether a particular portfolio aligns with their risk tolerance and long-term financial objectives. It’s a quick, shorthand way to communicate the fundamental structure of an investment strategy.
Partnership Shares and Profit Distribution
In business, particularly in partnerships or small enterprises, ownership stakes and profit-sharing agreements are often defined using fractions. If two partners agree that one will receive 2/3 of the company’s profits and the other 1/3, this fractional split dictates the financial relationship and the distribution of wealth generated by the business. This agreement ensures transparency and clarity in financial dealings, preventing disputes over revenue sharing. Similarly, decisions requiring majority votes might stipulate that 2/3 approval is needed, giving a clear threshold for significant strategic shifts or large expenditures.
Interpreting Financial Ratios and Company Performance
Financial analysts frequently use ratios to assess a company’s health and performance. While not always expressed as 2/3 directly, the underlying proportional understanding is crucial. For example, if a company’s current assets are 2/3 of its current liabilities, this indicates a potentially concerning liquidity situation where it may struggle to meet short-term obligations. Conversely, if a company generates 2/3 of its revenue from a single product line, it highlights a concentration risk, making the company vulnerable to fluctuations in that specific market segment. These interpretations, built on fractional thinking, provide valuable insights for investors and stakeholders evaluating a company’s financial stability and growth prospects.
The Power of Perspective: Why 2/3 Matters Beyond the Numbers
Understanding 2/3 is not just about crunching numbers; it’s about developing a sophisticated financial perspective that allows for more astute decision-making. It enables individuals and businesses to contextualize financial information, assess risk, and plan strategically.
Risk Assessment and Opportunity Evaluation
When faced with financial choices, framing potential outcomes as fractions can simplify complex scenarios. If an investment has a 2/3 chance of success, it implies a 1/3 chance of failure, allowing for a clearer risk assessment. This probabilistic thinking, rooted in fractions, empowers individuals to weigh potential gains against potential losses more effectively, leading to more calculated and confident financial decisions. It moves beyond a simple “yes” or “no” to a nuanced understanding of likelihood.
Long-Term Financial Planning and Goal Setting
For long-term financial goals, fractions help in breaking down large objectives into manageable steps. If you aim to save a substantial sum for retirement, you might realize you need to save 2/3 of your discretionary income each month to meet your target within a specific timeframe. This provides a tangible, actionable target that can be continuously monitored. Similarly, planning for a major purchase, like a down payment on a house, might involve setting aside 2/3 of annual bonuses or tax refunds. The fraction acts as a benchmark and a constant reminder of progress toward a significant financial milestone.
Avoiding Common Financial Misconceptions
A solid grasp of fractions like 2/3 helps in debunking common financial myths and avoiding pitfalls. For example, understanding that a 2/3 drop in value requires a 200% gain to return to the original value (if an asset drops from $90 to $30, it needs to triple to get back to $90) is crucial for investors facing market downturns. This insight prevents unrealistic expectations about recovery and encourages a more disciplined, long-term approach to investing. The fundamental understanding of fractional relationships provides a realistic lens through which to view market fluctuations and financial trends.
In conclusion, while “what is 2/3 fraction” might seem like a rudimentary mathematical question, its implications permeate every aspect of sound financial management. From the personal budget to global investment strategies, understanding this simple proportion empowers individuals and businesses to allocate resources, assess risks, and interpret financial data with greater clarity and confidence, ultimately fostering robust financial health and informed decision-making.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.