
The question “what is 1/3 in a fraction?” might seem deceptively simple, recalling elementary school arithmetic. However, its implications stretch far beyond basic mathematics, underpinning a vast array of critical concepts in personal finance, investing, and business strategy. Understanding 1/3, and fractions in general, is not merely about numerical representation; it’s about grasping proportionality, allocation, risk management, and the very fabric of financial decision-making. In a world increasingly driven by data and complex financial instruments, a solid grasp of these fundamental fractional concepts empowers individuals and businesses to make informed, strategic choices, optimize resources, and build lasting wealth. This article delves into the profound relevance of 1/3 within the financial landscape, transforming a basic math concept into a powerful lens for financial literacy and strategic planning.
The Foundational Role of Fractions in Financial Literacy
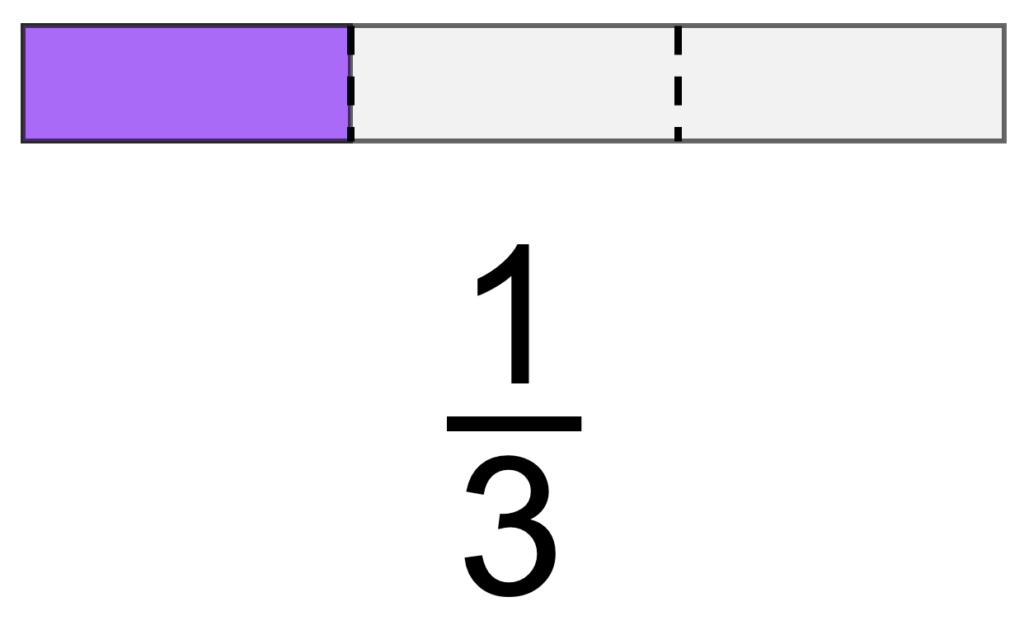
At its core, a fraction represents a part of a whole. In the case of 1/3, it signifies one part out of three equal parts of a complete entity. This seemingly straightforward definition becomes a cornerstone for understanding virtually every financial transaction, investment strategy, and budgeting decision. Without a clear comprehension of how parts relate to the whole, navigating the complexities of modern finance becomes akin to sailing without a compass.
Beyond Basic Arithmetic: Why Fractions Matter for Your Wallet
For many, the mention of fractions might trigger memories of rote memorization or abstract problems on a whiteboard. However, in the realm of personal finance, fractions transcend mere arithmetic; they become a language for expressing relationships, comparing values, and identifying proportions that directly impact your financial well-being. Consider the simple act of budgeting: understanding what percentage (a specialized form of a fraction) of your income goes towards housing, food, or savings is crucial. If you allocate 1/3 of your income to rent, you immediately grasp the significant portion of your earnings dedicated to that single expense. This isn’t just about the dollar amount; it’s about the proportion and its impact on your remaining disposable income or savings capacity.
Fractions provide an intuitive way to visualize financial health. When you hear about a “third” of the population struggling with debt, or a company dedicating “one-third” of its profits to research and development, these fractional representations offer immediate context and scale. They allow for quick mental calculations and comparisons, helping you contextualize your personal financial situation against broader economic trends or industry benchmarks. Mastery of fractions empowers individuals to move beyond simply tracking expenditures to proactively planning allocations, identifying inefficiencies, and setting realistic financial goals.
Understanding “Parts of a Whole” in Financial Contexts
The concept of “parts of a whole” is ubiquitous in finance. Whether it’s dividing a company’s equity among shareholders, allocating an investment portfolio across different asset classes, or splitting a restaurant bill, fractions provide the framework. For instance, when you invest in a mutual fund, you own a “fraction” of the total fund, which in turn owns “fractions” of various companies. Understanding this fractional ownership is critical for comprehending returns, risks, and diversification.
In a business context, profit sharing, revenue distribution, and cost allocation are all governed by fractional thinking. If three partners equally own a business, each owns 1/3 of the enterprise. This fractional ownership dictates their share of profits, responsibilities, and decision-making power. Similarly, a company might announce that 1/3 of its quarterly earnings will be distributed as dividends, instantly communicating a significant portion of its profitability being returned to shareholders. The ability to dissect financial scenarios into their constituent parts through the lens of fractions is an indispensable skill for both personal wealth management and professional financial analysis.
Deciphering 1/3: Practical Applications in Personal Finance
The abstract concept of 1/3 gains immense practical relevance when applied to the everyday decisions that shape our financial lives. From structuring a budget to managing debt, the proportion of one-third serves as a powerful guide.
Budgeting by Thirds: The 50/30/20 Rule and Beyond
One of the most widely recognized budgeting methodologies, the 50/30/20 rule, is a direct application of fractional thinking, albeit often expressed as percentages. It suggests allocating 50% of your after-tax income to needs, 30% to wants, and 20% to savings and debt repayment. While not exactly one-third, this rule underscores the principle of dividing income into proportional categories.
However, a simpler, more intuitive “budgeting by thirds” can also be highly effective for those seeking a straightforward approach. Imagine dedicating 1/3 of your income to essential living expenses (housing, utilities, food), 1/3 to savings and investments (retirement, emergency fund, future goals), and the remaining 1/3 to discretionary spending (entertainment, dining out, hobbies). This simple framework offers a clear visual and mental model for managing cash flow, ensuring that a substantial portion of your earnings is directed towards wealth building, rather than just consumption. While specific percentages may vary based on individual circumstances and financial goals, the underlying fractional division provides a robust starting point for financial planning.
Allocating Income and Savings: The Power of Proportional Planning
Beyond budgeting, the concept of 1/3 is invaluable for strategically allocating income and savings towards various financial objectives. For instance, many financial advisors recommend allocating a certain fraction of each paycheck to retirement accounts, another fraction to an emergency fund, and perhaps a third fraction to a down payment for a house or a child’s education fund. This proportional planning ensures steady progress across multiple goals without overwhelming any single area.
Consider an individual receiving a bonus. Instead of spending it all impulsively, they might decide to allocate 1/3 to paying down high-interest debt, 1/3 to boosting their emergency savings, and 1/3 to a long-term investment. This disciplined, fractional approach maximizes the impact of unexpected windfalls, transforming them into building blocks for financial security and growth. Proportional planning instilled by fractional understanding makes financial goals seem more attainable and manageable, reducing the psychological burden of overwhelming lump sums.
Understanding Debt Ratios and Financial Health
Fractions are critical for assessing financial health, particularly when it comes to debt. Lenders frequently evaluate debt-to-income (DTI) ratios, which are essentially fractions expressing how much of your gross monthly income goes towards debt payments. A common benchmark, for example, might suggest that your total monthly debt payments should not exceed 1/3 (or approximately 33%) of your gross monthly income. Exceeding this fraction can signal financial strain and make it difficult to secure new loans or manage existing obligations.
Similarly, understanding the fraction of your net worth tied up in illiquid assets versus liquid assets can provide insights into your financial flexibility. If 1/3 of your assets are tied up in a single, hard-to-sell investment, it exposes you to certain risks. Analyzing these fractional relationships helps individuals identify potential vulnerabilities and make adjustments to maintain a healthy and balanced financial profile.
1/3 in the World of Investing and Business Finance
The application of 1/3 extends significantly into the more complex arenas of investing and business finance, where strategic allocation, risk management, and ownership structures frequently rely on fractional divisions.
Portfolio Diversification: Spreading Risk Across Asset Classes
One of the cardinal rules of investing is diversification – not putting all your eggs in one basket. Fractions are the very language of diversification. An investor might decide to allocate 1/3 of their portfolio to stocks, 1/3 to bonds, and 1/3 to real estate or alternative investments. This fractional division is a deliberate strategy to spread risk, ensuring that a downturn in one asset class doesn’t decimate the entire portfolio.
Within asset classes, further fractional breakdown occurs. For example, the 1/3 allocated to stocks might be further divided: 1/3 to large-cap equities, 1/3 to small-cap, and 1/3 to international stocks. These proportional allocations are based on an investor’s risk tolerance, time horizon, and financial goals. Understanding that a specific fraction of your wealth is exposed to a particular market segment is crucial for informed decision-making and for adjusting your investment strategy as circumstances change.
Equity Stakes and Ownership: What a Third Can Mean for Your Business
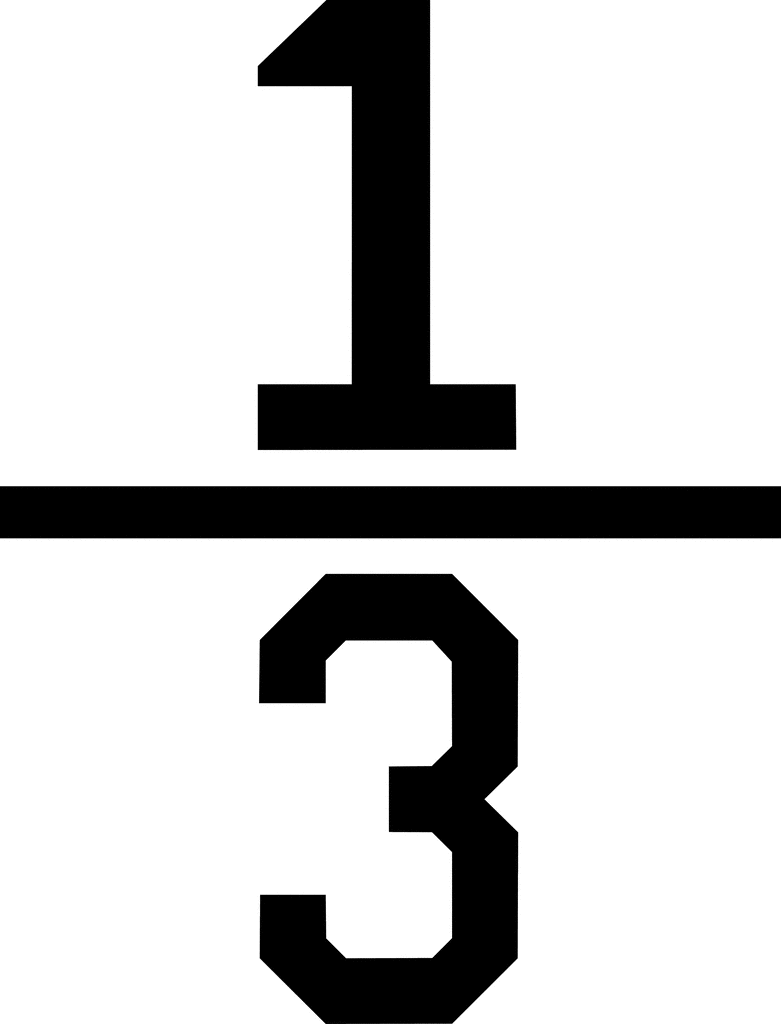
In the business world, fractions define ownership. If a startup has three co-founders, they might each own 1/3 of the company’s equity. This 1/3 stake is not just a number; it represents a significant share of control, voting rights, and future profits (or losses). The initial fractional allocation can have profound long-term implications for the company’s governance, future fundraising, and eventual valuation.
Similarly, as businesses grow and seek external funding, they often sell fractions of their ownership to investors. A venture capitalist might take a 1/3 stake in exchange for significant capital, fundamentally altering the ownership structure and dilution for existing shareholders. For entrepreneurs and business owners, a clear understanding of what a 1/3 stake entails – both its value and its implications for control – is paramount in negotiations and strategic planning.
Profit Sharing and Revenue Distribution Models
Many businesses, especially partnerships or those with employee incentive programs, utilize fractional models for profit sharing and revenue distribution. A common agreement might stipulate that 1/3 of net profits will be reinvested into the business, 1/3 distributed to partners, and 1/3 set aside for employee bonuses or a reserve fund. These fractional guidelines ensure transparency, fairness, and a structured approach to managing earnings.
In royalty agreements, artists or authors might receive a specific fraction of sales. Freelancers or contractors might negotiate a 1/3 upfront payment, 1/3 upon project milestone completion, and 1/3 upon final delivery. These fractional payment structures manage cash flow for both parties and define performance milestones. The precision afforded by fractional understanding prevents ambiguity and fosters clear financial communication in complex business arrangements.
The Psychology of Proportions: Making Smarter Financial Decisions
Beyond the purely mathematical and logistical applications, fractions play a subtle yet powerful role in shaping our psychological approach to money. Understanding proportions helps us avoid cognitive biases and make more rational choices.
Avoiding Fractional Fallacies: Why “A Third Off” Isn’t Always a Bargain
Marketers are adept at leveraging fractional language to influence consumer behavior. “A third off!” or “Buy two, get one free” (which translates to 1/3 off the total price per item if buying three) are common tactics. While these can represent genuine savings, understanding the underlying fractions helps consumers evaluate the true value proposition. Is 1/3 off a deeply discounted item more impactful than 10% off a premium product? The perceived saving of “a third” might feel substantial, but without context, it can be a “fractional fallacy.”
A financially literate individual understands that 1/3 off a $9 item saves $3, while 1/3 off a $900 item saves $300. The absolute value of the saving, and its impact on one’s budget, is what truly matters, not just the fractional discount itself. This critical thinking, rooted in fractional understanding, empowers consumers to distinguish between perceived value and actual financial benefit, leading to smarter spending and investing decisions.
Leveraging Fractional Thinking for Long-Term Wealth Building
The consistent, long-term application of fractional thinking is a cornerstone of wealth building. The idea of “paying yourself first” is often expressed as allocating a fraction (e.g., 1/10 or 1/5, or even 1/3) of every paycheck to savings or investments before paying any bills. Over time, these small, consistent fractional contributions compound into substantial wealth.
Understanding that a small fraction of your current income, consistently invested over decades, can grow into a significant portion of your retirement nest egg is a powerful motivator. It shifts the perspective from instant gratification to disciplined, proportional allocation for future prosperity. This fractional mindset encourages patience, consistency, and a belief in the power of compounding.
Communicating Financial Concepts Clearly with Fractions
Fractions offer a concise and universally understood way to communicate complex financial concepts. Instead of saying “you need to save X dollars for retirement, which is Y percent of your current income and will represent Z percent of your anticipated living expenses,” you can simplify by using fractions: “aim to save at least 1/3 of your current income for retirement to comfortably cover 2/3 of your post-work expenses.”
This clarity is invaluable when discussing financial plans with family members, employees, or clients. It breaks down intimidating figures into digestible, relatable proportions. Whether explaining a stock split (where each share becomes a fraction of its former self, like 1/2 in a 2-for-1 split) or the distribution of an estate, fractional language ensures that everyone understands the “parts of the whole” without getting lost in overwhelming numbers.
Tools and Techniques for Applying Fractional Concepts
While the theoretical understanding of fractions is crucial, modern financial management benefits greatly from practical tools and techniques that automate and visualize these proportional concepts.
Digital Calculators and Budgeting Apps: Automating Proportional Splits
Today’s digital landscape offers a plethora of tools designed to simplify financial management, many of which inherently apply fractional and percentage-based thinking. Budgeting apps like YNAB (You Need a Budget), Mint, or Personal Capital allow users to categorize expenses and income, effectively creating fractional allocations of their money. Users can set targets like “no more than 1/3 of income on housing” and the app will track progress towards this proportional goal.
Investment calculators, loan amortization schedules, and retirement planners also leverage fractional calculations to project future values, illustrate the impact of different contribution rates (a fraction of income), and break down large sums into manageable periodic payments. These tools empower individuals to model different fractional scenarios and visualize their financial future with greater accuracy and ease.
Visualizing Financial Allocations: Pie Charts and Bar Graphs
The human brain often grasps visual information more readily than raw numbers. This is where graphical representations like pie charts and bar graphs become incredibly powerful for financial literacy. A pie chart, by its very nature, is a representation of fractions, with each slice denoting a part of the whole (1/3 of your income to housing, 1/3 to savings, 1/3 to discretionary spending).
These visuals immediately convey the relative weight of different financial categories, making it easy to spot imbalances or areas for adjustment. Seeing that a disproportionately large “slice” of your income goes towards a particular expense can be a strong motivator for change. Financial planning software and online banking platforms frequently incorporate these visual aids to help users understand their spending patterns and asset allocation at a glance, making fractional concepts intuitively clear.

Continuous Learning: Enhancing Your Financial Fraction Fluency
Ultimately, mastering the practical application of 1/3 and other fractions in finance is an ongoing journey. It involves continuous learning, critical thinking, and a willingness to apply these fundamental concepts to evolving financial situations. Reading financial news, understanding economic reports, and evaluating investment opportunities all benefit from a robust “fractional fluency.”
Whether it’s dissecting a company’s financial statements (where ratios are fractions), understanding tax brackets (which apply different fractions of income to taxation), or comparing interest rates (expressed as fractions of the principal), the ability to think proportionally is an indispensable asset. Embracing this continuous learning mindset transforms the simple question “what is 1/3 in a fraction?” from a basic math query into a foundational pillar of comprehensive financial understanding and strategic decision-making.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.