
In the intricate world of personal finance and investment, the concept of “what as a fraction” serves as a deceptively simple yet profoundly powerful lens through which to view, understand, and manage our money. While fractions might evoke memories of elementary school math, their application in financial planning, budgeting, investing, and wealth creation is anything but basic. They are the bedrock upon which sound financial decisions are often built, allowing us to break down complex financial landscapes into digestible, actionable components. From understanding your budget’s allocation to embracing the democratizing power of fractional ownership, thinking in fractions empowers individuals to gain clarity, exert control, and strategically navigate their financial journey. This article delves into the multi-faceted significance of fractions in the realm of money, revealing how this fundamental mathematical concept underpins some of the most crucial strategies for achieving financial well-being and growth.
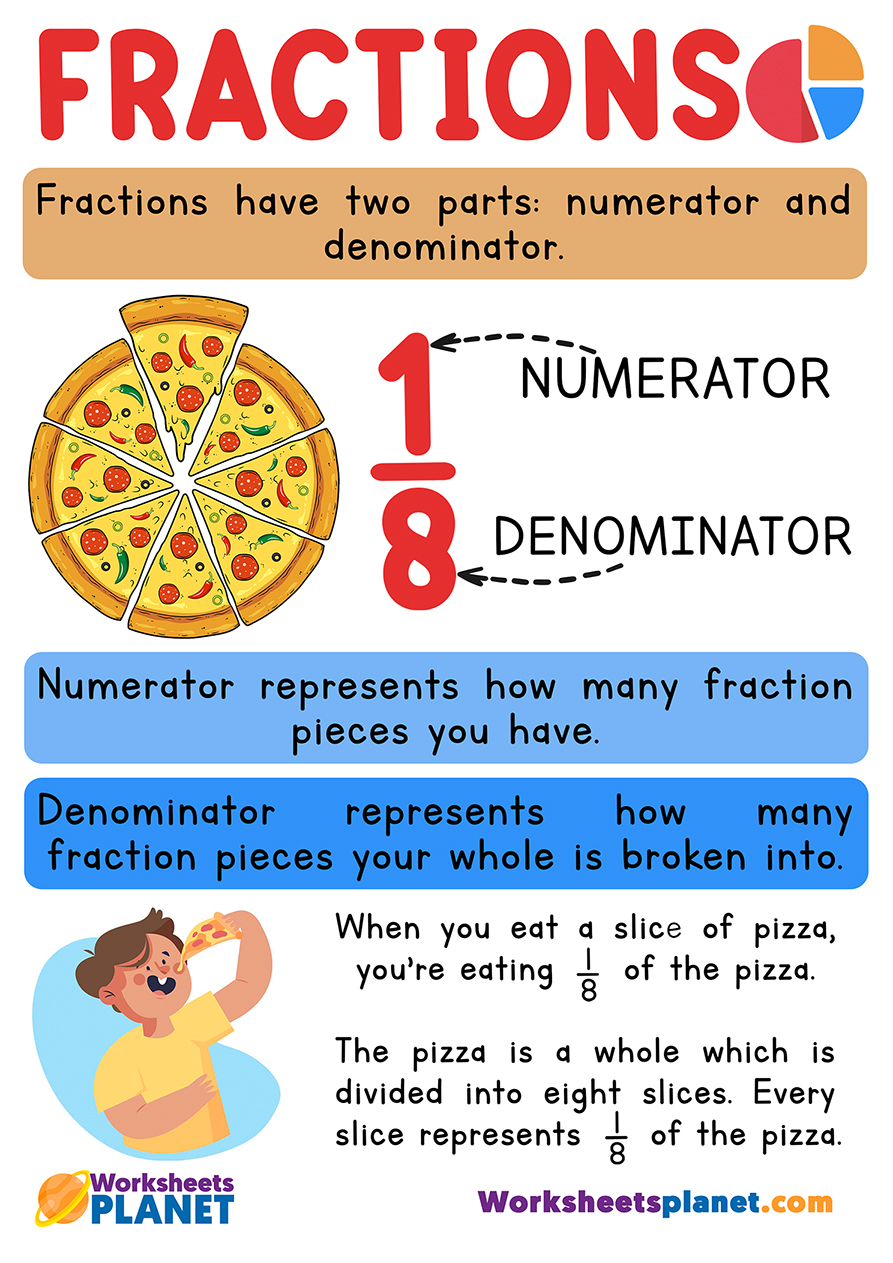
The Indispensable Role of Fractions in Personal Finance
At its core, personal finance is about managing resources – income, expenses, savings, and investments – which are all inherently quantifiable. Fractions provide a universal language for understanding the relationships and proportions between these different financial components. They allow us to move beyond absolute numbers and grasp the relative importance and impact of various financial decisions.
Beyond Simple Arithmetic: Why Fractions Matter
While we often deal with whole numbers when discussing salaries or account balances, the real insights emerge when we consider these numbers in relation to others. For instance, knowing your monthly income is $5,000 is one thing; understanding that your rent consumes 30% of that income (or 3/10 as a fraction) provides a much deeper understanding of your financial burden and disposable income. Fractions help us compare, contrast, and prioritize across different categories, making it easier to identify areas for improvement or strategic allocation. They transform raw data into meaningful intelligence, enabling a more nuanced approach to financial management than simply tracking ins and outs. This proportional thinking is critical for developing financial discipline and making informed choices that align with long-term goals.
From Budgeting to Investing: Everywhere You Look
The presence of fractions permeates almost every aspect of personal finance. In budgeting, we allocate a “fraction” of our income to housing, food, transportation, and entertainment. In saving, we aim to put aside a certain “fraction” of every paycheck. When investing, we evaluate what “fraction” of our portfolio is allocated to stocks versus bonds, or domestic versus international markets. Even in understanding our financial health, ratios like debt-to-income or savings rate are, at their heart, fractions expressed as percentages. This ubiquitous application means that a solid grasp of fractional thinking is not just an academic exercise but a practical skill that underpins effective financial stewardship. It’s the difference between merely tracking expenses and understanding where your money is truly going and what proportion it represents of your overall financial picture.
Fractional Ownership: Redefining Accessibility in Investing
One of the most revolutionary applications of the “what as a fraction” concept in modern finance is the rise of fractional ownership. Historically, owning substantial assets like shares of high-priced companies, real estate, or valuable collectibles was exclusive to those with significant capital. Fractional ownership has shattered these barriers, democratizing access to a wider range of investment opportunities.
Demystifying Fractional Shares: Stocks for Everyone
Perhaps the most visible manifestation of fractional ownership is in the stock market. Fractional shares allow investors to buy a portion of a single share of stock, rather than being limited to full shares. This means that if a company’s stock trades at $1,000 per share, an investor with just $100 can still purchase 0.1 of that share. This innovation has had a profound impact:
-
Accessibility: It lowers the entry barrier for investing in high-value companies like Amazon, Google, or Tesla, making them available to everyday investors with smaller budgets.
-
Diversification: Investors can spread smaller amounts of capital across a wider array of stocks, instantly enhancing portfolio diversification without needing large sums for full shares of each desired company.
-
Dollar-Cost Averaging: It simplifies the practice of investing a fixed amount regularly, regardless of share price, allowing investors to consistently buy fractions of shares and take advantage of market fluctuations over time.
This paradigm shift empowers individuals to participate in wealth creation from market growth, regardless of their starting capital.
Expanding Horizons: Fractional Real Estate and Alternative Assets
The concept of fractional ownership extends far beyond traditional stocks. It’s increasingly prevalent in other asset classes, further opening up exclusive markets:
-
Fractional Real Estate: Platforms allow investors to buy a “fraction” of a property, whether it’s residential, commercial, or even vacation rentals. This enables participation in real estate investing without the substantial capital, management headaches, or illiquidity typically associated with direct property ownership. Investors can earn rental income and benefit from property appreciation proportional to their fractional stake.
-
Alternative Assets: From fine art and rare wines to collectible luxury watches and even professional sports teams, fractional ownership platforms are emerging for a diverse range of alternative investments. These assets, traditionally reserved for ultra-high-net-worth individuals, are now becoming accessible to a broader audience, allowing smaller investors to diversify their portfolios with tangible, often appreciating, assets.
The Mechanics and Benefits of Fractional Investing
The mechanics typically involve an intermediary platform that aggregates funds from multiple investors to purchase the full asset, then divides the ownership and any associated returns (e.g., dividends, rental income, appreciation) proportionally. While fractional ownership offers immense benefits in terms of accessibility and diversification, it also comes with considerations such as understanding the platform’s fees, liquidity of fractional shares (especially for alternative assets), and the regulatory environment. Despite these considerations, the overarching benefit is a democratized investment landscape where “what as a fraction” significantly lowers barriers to entry and allows for more granular and strategic portfolio construction.
Budgeting and Wealth Allocation: Slicing the Financial Pie
At the heart of sound financial management lies the ability to allocate resources effectively. Whether it’s your monthly income or your entire investment portfolio, thinking in fractions or percentages allows for a systematic and strategic distribution of funds. This “slicing the financial pie” approach ensures that every dollar has a purpose and contributes to your overarching financial objectives.
The Golden Rules: 50/30/20 and Beyond
One of the most widely cited budgeting strategies is the 50/30/20 rule, which dictates how to divide your after-tax income into three main categories:
-
50% for Needs: This fraction covers essential expenses like housing, utilities, groceries, transportation, and minimum loan payments.
-
30% for Wants: This fraction is allocated to discretionary spending such as dining out, entertainment, hobbies, and travel.
-
20% for Savings & Debt Repayment: This crucial fraction is dedicated to building an emergency fund, saving for retirement, investing, and paying down high-interest debt beyond the minimums.
This rule, a perfect example of “what as a fraction,” provides a simple yet effective framework for ensuring financial stability and progress. While it serves as a valuable starting point, individuals can adapt these fractions to better suit their unique circumstances and goals. For example, someone aggressively paying off debt might shift to a 50/20/30 rule, dedicating a larger fraction to debt repayment. The power lies in its flexibility and its emphasis on proportional allocation.
Strategic Asset Allocation: Diversifying Your Portfolio
In investing, asset allocation is the process of dividing your investment capital among different asset classes, such as stocks, bonds, and cash. This is another critical area where “what as a fraction” thinking comes into play. The chosen fractions for each asset class depend on an investor’s risk tolerance, time horizon, and financial goals.
-
Risk Tolerance: Younger investors with a higher risk tolerance might allocate a larger fraction (e.g., 80%) to stocks, which offer higher growth potential but also higher volatility. Older investors closer to retirement might shift a larger fraction (e.g., 60%) to bonds, which are generally less volatile and provide income.
-
Diversification: By consciously allocating specific fractions to different asset classes, investors can diversify their portfolios, reducing overall risk. If one asset class underperforms, the others may compensate, mitigating potential losses. Rebalancing your portfolio periodically, which involves adjusting the fractions back to your target allocation, is also crucial for maintaining the desired risk profile.
Understanding Your Debt-to-Income Ratio
The debt-to-income (DTI) ratio is a key financial metric used by lenders to assess an individual’s ability to manage monthly payments and repay debts. It’s calculated by dividing your total monthly debt payments by your gross monthly income. This ratio is expressed as a percentage, but fundamentally it’s a fraction (debt payments / income).
-
Significance: A lower DTI ratio indicates a better ability to manage debt and suggests less risk to lenders. A DTI of 36% or less is generally considered favorable, while higher ratios can make it difficult to obtain new loans or mortgages.
-
Management: Understanding your DTI allows you to assess your financial leverage. If your DTI is too high, it signals a need to reduce debt (the numerator of the fraction) or increase income (the denominator), thereby improving the fraction and your financial standing. This proportional understanding is vital for managing credit and achieving financial freedom.
Financial Health Metrics: Ratios and Proportions for Insight
Beyond budgeting and investment allocation, fractions underpin many essential financial health metrics. These ratios provide objective insights into your financial standing, helping you track progress, identify weaknesses, and make informed decisions to secure your financial future. They transform raw numbers into actionable intelligence.
Savings Rate: Your Path to Financial Independence
Your savings rate is perhaps one of the most critical fractions in your journey toward financial independence. It represents the percentage of your gross or net income that you save and invest. Calculated as (Amount Saved + Invested) / (Income), this fraction directly correlates with how quickly you can achieve financial freedom.
-
Impact: A higher savings rate means you are accumulating wealth faster. Even small increases in this fraction can have a significant compounding effect over time. For example, increasing your savings rate from 10% to 15% means you are dedicating 50% more of your income to future wealth, drastically reducing the time it takes to reach retirement or other financial milestones.
-
Benchmarking: While a 10-15% savings rate is often recommended as a minimum, many financial independence proponents advocate for much higher rates (e.g., 30-50% or even more) to drastically shorten the working years. Understanding your current savings fraction allows you to set realistic goals and track your progress toward them.
Emergency Fund Coverage: A Critical Safety Net
An emergency fund is a cornerstone of financial security, providing a buffer against unexpected expenses like job loss, medical emergencies, or car repairs. The adequacy of your emergency fund is often measured by how many months of essential living expenses it can cover. This is a direct application of fractional thinking: (Emergency Fund Balance) / (Monthly Essential Expenses).
-
Standard: The common recommendation is to have 3 to 6 months’ worth of essential expenses saved. This fraction acts as a crucial safety net, preventing you from going into debt or derailing your long-term financial plans during unforeseen circumstances.
-
Personalization: The ideal “fraction of coverage” can vary based on job security, number of dependents, and health status. Someone with an unstable income might aim for a larger fraction, perhaps 9-12 months, whereas a dual-income household with stable jobs might be comfortable with 3-6 months. The key is to understand this ratio and adjust it to your personal risk profile.
Investment Portfolio Breakdown: Balancing Risk and Return
Regularly reviewing your investment portfolio’s breakdown is essential for maintaining your desired risk-return profile. This involves understanding the fraction of your portfolio allocated to different asset classes, sectors, geographies, and even individual holdings.
-
Rebalancing: Over time, market fluctuations can cause your portfolio’s fractions to drift from your target allocation. For example, if stocks have performed exceptionally well, their fraction of your portfolio might grow larger than intended. Rebalancing involves selling off some of the overperforming assets and buying more of the underperforming ones to restore your target fractions. This disciplined approach helps manage risk and ensures your portfolio remains aligned with your financial strategy.
-
Risk Concentration: By examining the fractions, you can identify if too much of your wealth is concentrated in a single stock, sector, or geographical region, which could expose you to undue risk. Spreading your investments across various fractions minimizes the impact of a downturn in any single area.
The Power of Proportional Thinking in Long-Term Wealth Building
Ultimately, understanding “what as a fraction” isn’t just about managing present finances; it’s a powerful psychological and strategic tool for building long-term wealth. It shifts our perspective from immediate gratification to sustained growth, emphasizing the cumulative power of small, consistent actions.
Compounding Growth: The Fraction of Reinvestment
The eighth wonder of the world, compounding interest, is a direct manifestation of fractional thinking. It’s the process by which your earnings on an investment are reinvested to generate additional earnings. Every “fraction” of your return that is reinvested becomes part of the principal, growing your base for future returns.
-
Exponential Impact: The magic of compounding lies in its exponential nature. A small fraction of consistent returns, consistently reinvested over decades, can transform modest initial investments into substantial wealth. Understanding this fractional growth motivates investors to start early and remain disciplined, recognizing that each reinvested dollar (or fraction of a dollar) is working harder for them over time.
-
Dividend Reinvestment Plans (DRIPs): DRIPs automatically use cash dividends to purchase additional shares or fractional shares of a company’s stock, directly leveraging the power of compounding with minimal effort. This is a practical example of how fractional reinvestment accelerates wealth accumulation.
Setting Realistic Goals: Incremental Progress
Breaking down large, intimidating financial goals into smaller, manageable “fractions” makes them seem achievable. Instead of thinking about saving $1 million, think about saving 1/10th of that ($100,000) or even a fraction of your monthly income towards that goal.
-
Motivation: This incremental approach prevents overwhelm and maintains motivation. Celebrating the achievement of smaller fractional goals (e.g., reaching your first $1,000 saved, then your first $10,000) builds momentum and reinforces positive financial habits.
-
Actionable Steps: Whether it’s paying off a fraction of your credit card debt each month, saving a fraction of your bonus, or investing a small fraction of your tax refund, these smaller, proportional steps contribute meaningfully to larger objectives, making the path to financial success feel less daunting and more navigable.

The Behavioral Economics of “Small Parts”
Our brains are often better at processing proportions and relative values than absolute large numbers. Framing financial decisions in terms of “what as a fraction” can leverage this cognitive tendency. Instead of cutting out a $5 daily coffee, which might feel like deprivation, consider it as saving a fraction of your monthly “wants” budget – perhaps increasing your savings fraction from 10% to 11%. This reframing can make sacrifices feel less impactful and the benefits more tangible. It helps us see how seemingly small financial adjustments, when viewed as fractions of a larger whole, contribute significantly to our overall financial health.
In conclusion, “what as a fraction” is far more than a mathematical curiosity in the financial world. It is a fundamental framework that provides clarity, enables strategic planning, democratizes investment opportunities, and empowers individuals to take control of their financial destiny. By embracing proportional thinking across budgeting, investing, and financial health assessment, individuals can build a more robust, resilient, and prosperous financial future.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.