
Understanding how your wages are calculated is a fundamental aspect of personal finance, empowering you to budget effectively, plan for the future, and identify any discrepancies in your pay. While a paystub might seem like a complex labyrinth of numbers and acronyms, breaking it down into its core components makes the process transparent and manageable. This guide will walk you through the essential steps to accurately calculate your wages, from your initial earnings to your final take-home pay.
Understanding the Basics: Gross vs. Net Pay
The first step in calculating your wages involves distinguishing between two critical figures: your gross pay and your net pay. These terms represent different stages of your earnings and are vital for a complete understanding of your compensation.

What is Gross Pay?
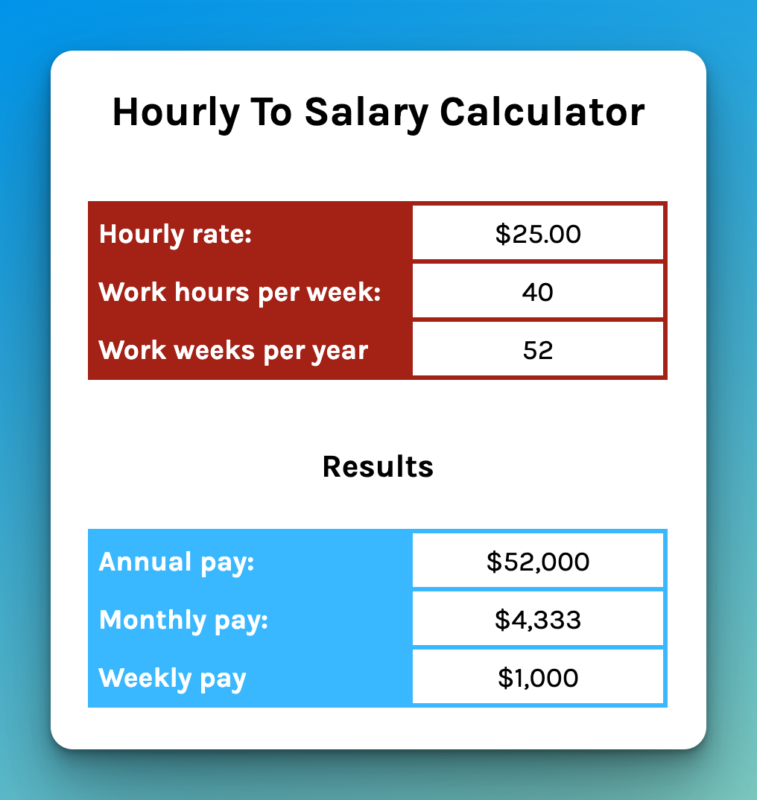
Gross pay is the total amount of money you earn before any deductions or taxes are withheld. It’s the headline figure that reflects your base salary or hourly rate multiplied by the hours worked, plus any additional earnings like overtime, bonuses, or commissions. For salaried employees, gross pay is typically a fixed amount per pay period (e.g., bi-weekly, semi-monthly, or monthly). For hourly employees, it’s calculated by multiplying your hourly rate by the total hours worked in the pay period. If you earn an annual salary, your gross pay for a specific period is simply your annual salary divided by the number of pay periods in a year (e.g., 26 for bi-weekly, 12 for monthly). Gross pay is your total compensation before any money leaves your pocket for taxes or benefits.
What is Net Pay?
Net pay, often referred to as “take-home pay,” is the amount of money you actually receive after all taxes, deductions, and withholdings have been subtracted from your gross pay. This is the figure that gets deposited into your bank account or appears on your physical paycheck. While gross pay reflects your total earnings, net pay reflects the usable income you have available for living expenses, savings, and investments. The difference between gross and net pay can be substantial, making it crucial to understand the various deductions that contribute to this reduction.
Decoding Your Paystub: Key Deductions and Withholdings
Your paystub is a detailed record of your earnings and all the subtractions made to arrive at your net pay. Familiarizing yourself with each deduction category is essential for an accurate wage calculation and for identifying potential errors.
Federal Income Tax Withholding
The largest deduction for many individuals is federal income tax. The amount withheld from each paycheck is determined by the information you provide on your Form W-4 to your employer. This form dictates your marital status, the number of dependents you claim, and any additional income or deductions you anticipate. The IRS provides tax tables and formulas that employers use to calculate the appropriate withholding amount based on your W-4 entries and your gross pay. It’s not the final tax you owe, but an estimate paid throughout the year to avoid a large tax bill at year-end. Adjusting your W-4 can impact your net pay, potentially increasing it if you claim more allowances or decreasing it if you elect for additional withholding.
State and Local Income Taxes
Depending on where you live and work, you may also be subject to state and/or local income taxes. Not all states levy income tax, and even fewer cities or localities do. However, in jurisdictions that do, these taxes are withheld from your gross pay in a manner similar to federal income tax, often based on state-specific withholding tables and forms. The rates and rules for state and local taxes vary significantly, so it’s important to understand the specific requirements for your region.
FICA Taxes: Social Security and Medicare
FICA stands for the Federal Insurance Contributions Act, and it covers two mandatory federal taxes: Social Security and Medicare. These taxes fund federal programs that provide benefits for retirees, the disabled, and children of deceased workers (Social Security) and healthcare for individuals over 65 or with certain disabilities (Medicare).
-
Social Security Tax: As of the current regulations, this is typically 6.2% of your gross wages up to an annual earnings limit (which adjusts annually). Your employer also pays a matching 6.2%.
-
Medicare Tax: This is typically 1.45% of your gross wages, with no annual earnings limit. Your employer also pays a matching 1.45%.
These are non-negotiable deductions for most employees and are a significant portion of the total tax burden.
Pre-Tax vs. Post-Tax Deductions
Deductions can be categorized as either pre-tax or post-tax, and this distinction has a substantial impact on your taxable income.
-
Pre-Tax Deductions: These are deductions taken from your gross pay before income taxes are calculated. This reduces your taxable income, thereby lowering the amount of federal, state, and sometimes local income taxes you owe. Common pre-tax deductions include contributions to 401(k)s, 403(b)s, health savings accounts (HSAs), flexible spending accounts (FSAs), and sometimes health insurance premiums. The benefit is a lower taxable income and, consequently, lower tax liability.
-
Post-Tax Deductions: These deductions are taken from your pay after all taxes have been calculated and withheld. They do not reduce your taxable income. Examples often include Roth 401(k) contributions (though the earnings grow tax-free), loan repayments (e.g., 401(k) loans), union dues, garnishments, and certain types of disability insurance premiums. While they reduce your net pay, they don’t offer the immediate tax advantage of pre-tax deductions.
Understanding Your W-4 Form
The Form W-4, Employee’s Withholding Certificate, is crucial because it directly influences how much federal income tax is withheld from your paycheck. When you start a new job, your employer will ask you to complete this form. You can adjust your W-4 at any time during the year if your financial or family situation changes (e.g., marriage, birth of a child, a second job). Reviewing and updating your W-4 annually, or whenever a major life event occurs, helps ensure that the correct amount of tax is withheld, preventing either a large tax refund (meaning you overpaid throughout the year) or a large tax bill (meaning you underpaid). The goal is to have your withholding match your actual tax liability as closely as possible.
Beyond the Hourly Rate: Overtime, Bonuses, and Commissions
While base salary or hourly pay forms the core of your wages, many individuals earn additional income through various means. Understanding how these are calculated and taxed is key to a complete wage picture.
Overtime Pay Calculations
For non-exempt employees, the Fair Labor Standards Act (FLSA) mandates overtime pay for hours worked beyond 40 in a workweek. The standard overtime rate is “time and a half,” meaning 1.5 times your regular hourly rate. To calculate your gross pay with overtime:
-
Calculate regular pay: Regular hourly rate × 40 hours.
-
Calculate overtime hours: Total hours worked – 40 hours.
-
Calculate overtime pay: Overtime hours × (Regular hourly rate × 1.5).
-
Total gross pay: Regular pay + Overtime pay.
Some states have stricter overtime laws (e.g., daily overtime after 8 hours), so it’s important to be aware of your local regulations. Overtime earnings are subject to the same taxes and deductions as regular pay, though the higher income can push you into a higher tax bracket temporarily for that pay period, leading to higher withholding.
Taxation of Bonuses and Commissions
Bonuses and commissions are considered supplemental wages by the IRS and are generally subject to federal income tax withholding, Social Security, Medicare, and any applicable state and local taxes. Employers typically have two methods for withholding federal income tax on supplemental wages:
-
Percentage Method: The most common method, especially for larger bonuses, where a flat percentage (currently 22% for federal income tax) is withheld. This is often applied when the supplemental wages are identified separately from regular wages.
-
Aggregate Method: The bonus or commission is added to your regular wages for the pay period, and tax is calculated on the total amount as if it were your regular pay. This method might be used for smaller, routine commissions.
Despite the higher withholding rate often seen with the percentage method, it’s important to remember that this is just withholding. Your actual tax liability for the year will be determined when you file your annual tax return, taking into account all your income and deductions.
Salaried vs. Hourly Exemptions
The distinction between salaried and hourly employees often comes with different rules regarding overtime eligibility and how wages are calculated.
-
Exempt Salaried Employees: Certain employees are exempt from FLSA overtime provisions if they meet specific criteria related to their job duties (e.g., executive, administrative, professional) and are paid a salary above a certain threshold. Their wages are generally a fixed amount per pay period, regardless of hours worked, and they do not receive overtime pay.
-
Non-Exempt Hourly Employees: These employees are typically paid based on the hours they work and are entitled to overtime pay for hours exceeding 40 in a workweek. Their wage calculation is straightforward: hourly rate multiplied by hours worked, plus any applicable overtime.
Understanding your exemption status is crucial for correctly calculating your potential earnings, especially concerning additional hours worked.
The Impact of Benefits: Calculating Their Monetary Value
Beyond the direct cash compensation, many employers offer a comprehensive benefits package that significantly adds to your overall compensation. While some benefits are deducted from your pay, others represent a non-cash value that should be considered when assessing your total remuneration.
Health Insurance Premiums
If your employer provides health insurance, a portion of the premium is often deducted from your paycheck. As mentioned earlier, these are frequently pre-tax deductions, reducing your taxable income. The amount deducted depends on the plan you choose (e.g., single, family) and your employer’s contribution towards the premium. While it reduces your net pay, the value of employer-sponsored health insurance often far exceeds your out-of-pocket premium costs, representing a substantial benefit.
Retirement Contributions (401k, 403b)
Contributions to employer-sponsored retirement plans like a 401(k) (for private sector) or 403(b) (for non-profits and public schools) are powerful tools for long-term wealth building. These contributions are typically pre-tax, reducing your current taxable income. Many employers also offer a matching contribution, which is essentially free money added to your retirement account. When calculating your total compensation, always factor in the value of any employer match, as it directly increases your overall financial benefit. For example, if you contribute 5% and your employer matches 3%, your total retirement contribution is 8% of your salary, significantly boosting your long-term savings.
Other Employer-Provided Benefits
Employers often provide a range of other benefits that, while not directly appearing on your paystub as cash, have significant monetary value. These can include:
-
Paid Time Off (PTO): Vacation days, sick leave, and holidays represent paid time when you are not actively working, but still receiving your regular wages.
-
Life and Disability Insurance: Many employers offer basic life insurance and short-term or long-term disability insurance at no cost or a subsidized rate.
-
Tuition Reimbursement: Programs that help employees pay for further education.
-
Wellness Programs: Gym memberships, health screenings, or other initiatives.
-
Employee Stock Purchase Plans (ESPPs): Allow employees to buy company stock at a discount.
-
Commuter Benefits: Pre-tax deductions for public transit or parking.
When evaluating your overall compensation, it’s crucial to look beyond just your take-home pay and consider the full spectrum of benefits your employer provides, as they collectively enhance your financial well-being and security.
Advanced Scenarios and Financial Planning
Understanding wage calculation isn’t just about verifying your paystub; it’s a critical skill for broader financial planning, especially for those with less traditional employment structures.
Calculating for Self-Employment and Freelance Income
For freelancers, independent contractors, or small business owners, wage calculation takes on a different dimension. There are no employers withholding taxes, meaning you are responsible for calculating and paying your own self-employment taxes (Social Security and Medicare for both employee and employer portions, currently 15.3% on net earnings up to the Social Security limit, plus 2.9% for Medicare on all net earnings) and estimated income taxes.
-
Track all income: Meticulously record every payment received.
-
Track all expenses: Deduct legitimate business expenses to arrive at your net profit.
-
Calculate Self-Employment Tax: This is calculated on 92.35% of your net earnings from self-employment.
-
Calculate Estimated Income Tax: Based on your projected annual net income after self-employment tax, you’ll need to estimate your federal, state, and local income taxes.
-
Make Quarterly Estimated Tax Payments: The IRS (and many states) requires self-employed individuals to pay estimated taxes quarterly (Form 1040-ES) to avoid penalties.
Understanding these calculations is paramount for financial stability when self-employed, as underpayment can lead to penalties and a large unexpected tax bill.
The Importance of Regular Wage Audits
Periodically auditing your wages is a smart financial habit. This involves comparing your paystub against your employment contract or offer letter, your W-4 elections, and your understanding of company policies. Check for:
-
Correct hourly rate or salary.
-
Accurate number of hours worked (for hourly employees) or correct pay period salary.
-
Correct federal, state, and local tax withholdings based on your W-4.
-
Correct FICA deductions.
-
Accuracy of pre-tax and post-tax deductions for benefits, retirement contributions, or other items.
-
Any additional pay, such as bonuses or commissions, correctly applied.
Errors can occur, and catching them early can prevent financial headaches. If you find a discrepancy, promptly contact your HR or payroll department with your documentation for clarification and correction.

Using Wage Calculations for Budgeting and Financial Goals
Your net pay is the foundation of your personal budget. By understanding exactly how much you take home, you can realistically allocate funds for housing, food, transportation, debt repayment, and discretionary spending. Furthermore, knowing your gross pay and the impact of pre-tax deductions allows you to strategically adjust your retirement contributions or health savings account contributions to reduce your taxable income and save more for the future. Wage calculation isn’t just an accounting exercise; it’s a vital tool for informed financial decision-making, helping you set achievable savings goals, plan for major purchases, and build a secure financial future.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.