
Understanding your income is the bedrock of sound financial management, whether you’re managing personal finances or overseeing a business. It’s more than just knowing your salary; it’s about meticulously tracking all inflows, understanding deductions, and distinguishing between different types of earnings. Accurate income calculation empowers you to make informed budgeting decisions, set realistic financial goals, plan for taxes, and ultimately achieve financial stability and growth. This guide will walk you through the essential steps and considerations for calculating income, ensuring you gain true clarity over your financial standing.
Understanding Different Income Types
Before diving into the calculation process, it’s crucial to grasp the various classifications of income. Each type has distinct implications for budgeting, taxes, and financial planning.
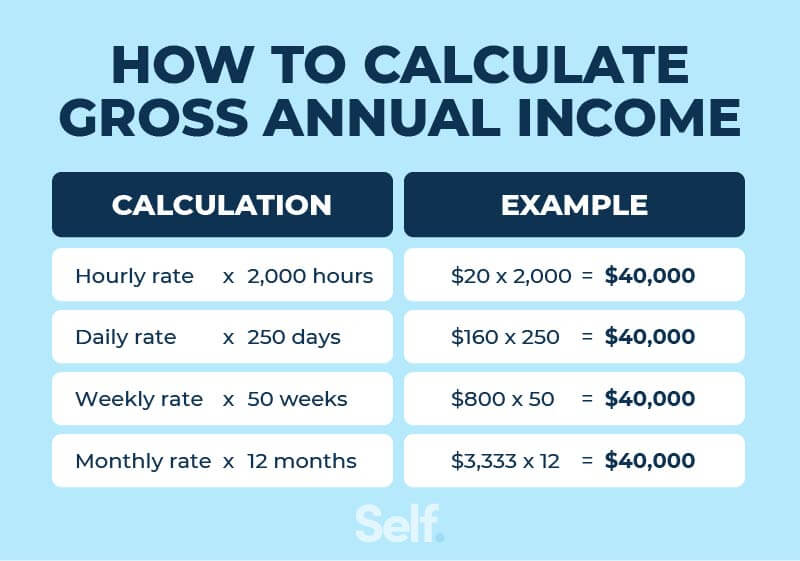
Gross Income
Gross income represents the total amount of money earned or received from all sources before any deductions or taxes are taken out. For individuals, this typically includes:
-
Wages and Salary: Your regular pay from an employer before any deductions.
-
Tips and Commissions: Additional earnings based on performance or service.
-
Bonuses: One-time payments often tied to individual or company performance.
-
Self-Employment/Business Income: Total revenue generated from a business or freelance work before business expenses.
-
Rental Income: Money received from properties you own and rent out.
-
Investment Income: Interest from savings accounts or bonds, dividends from stocks, and capital gains from selling assets.
-
Alimony and Other Miscellaneous Income: Any other funds received that are not gifts or loans.
For businesses, gross income often refers to gross revenue or total sales before accounting for the cost of goods sold or operating expenses. Understanding your gross income gives you a full picture of your earning potential.
Net Income (Take-Home Pay)
Net income, often referred to as “take-home pay” for individuals, is the amount of money you actually receive after all mandatory and voluntary deductions have been subtracted from your gross income. These deductions can include:
-
Federal, State, and Local Taxes: Income taxes, property taxes, etc.
-
FICA Taxes: Social Security and Medicare contributions.
-
Health Insurance Premiums: Your share of health coverage costs.
-
Retirement Contributions: Pre-tax contributions to 401(k)s, IRAs, etc.
-
Loan Repayments: Garnishments or direct deductions for loans.
-
Other Pre-Tax Deductions: Health Savings Accounts (HSAs), Flexible Spending Accounts (FSAs).
-
Voluntary Post-Tax Deductions: Union dues, charitable contributions, specific investment plans.
Net income is the figure you use for daily budgeting and expense management, as it reflects the cash available to you for spending, saving, and investing after essential obligations are met.
Business Income
For entrepreneurs and business owners, calculating income involves a more nuanced approach, distinguishing between different levels of profitability:
-
Revenue: The total income generated from sales of goods or services before any costs are subtracted.
-
Gross Profit: Revenue minus the Cost of Goods Sold (COGS). COGS includes the direct costs attributable to the production of the goods or services sold by a company.
-
Operating Profit (EBIT – Earnings Before Interest and Taxes): Gross profit minus operating expenses (e.g., salaries, rent, utilities, marketing, administrative costs). This indicates the profitability of a company’s core operations.
-
Net Profit (Net Income): The “bottom line” profit after all expenses, including interest and taxes, have been deducted from revenue. This is the ultimate measure of a company’s profitability.
Accurate calculation of business income is vital for assessing performance, making strategic decisions, attracting investors, and fulfilling tax obligations.
Step-by-Step Guide to Personal Income Calculation
For individuals, calculating income primarily revolves around aggregating all sources and then accounting for deductions.
Gathering Your Income Sources
Start by collecting all documents that detail your earnings. This typically includes:
-
Pay Stubs: For regular employment income.
-
Bank Statements: To track deposits from various sources.
-
Investment Statements: For dividends, interest, and capital gains.
-
Business or Freelance Records: Invoices, payment logs, and receipts if you have side hustles or operate as a sole proprietor.
-
Rental Agreements and Payment Records: If you own rental property.
-
Tax Documents: W-2s, 1099s (NEC, MISC, DIV, INT, B), K-1s, which will summarize your income for the year.
Calculating Regular Employment Income
-
Salaried Employees: Your annual salary is your gross income. Divide by the number of pay periods to find your gross pay per period.
-
Hourly Employees: Multiply your hourly rate by the number of hours worked in a pay period. Remember to factor in overtime hours at their higher rates (e.g., 1.5x regular pay).
-
Commissions and Bonuses: Add these amounts to your regular pay when they are received.
Incorporating Irregular Income
For those with freelance work, gig economy earnings, or other variable income streams, consistent tracking is paramount.
-
Maintain a Detailed Log: Record every payment received, the date, and the source.
-
Invoice System: If you invoice clients, keep meticulous records of all invoices issued and payments received.
-
Dedicated Bank Account: Consider using a separate bank account for business/freelance income to simplify tracking.
Accounting for Investment and Other Passive Income
-
Dividends and Interest: Track these amounts from your brokerage statements, bank statements, and 1099-DIV/INT forms.
-
Capital Gains: If you sell investments for a profit, this is a capital gain. Keep records of purchase and sale prices.
-
Rental Income: Sum up all rent collected, potentially deducting certain expenses directly related to the property (though for net income calculation, it’s typically gross rent first).
Summing Up Your Gross Personal Income
Once you have identified and calculated all individual income streams, add them together. This comprehensive total represents your true gross income from all sources over a specific period (e.g., monthly, quarterly, annually).
Deducting for Net Income
After calculating gross income, subtract all pre-tax and post-tax deductions to arrive at your net income.
-
Mandatory Deductions: Federal, state, and local income taxes; Social Security and Medicare (FICA).
-
Pre-Tax Deductions: Contributions to 401(k)s, IRAs (for specific types), HSAs, FSA, and health insurance premiums paid pre-tax. These reduce your taxable income.
-
Post-Tax Deductions: Any deductions taken after taxes, such as Roth 401(k) contributions, certain insurance premiums, or loan repayments.
Your net income is the amount that lands in your bank account, ready for your discretion.
Calculating Business Income for Entrepreneurs and Small Businesses
Business income calculation is more complex, requiring a systematic approach to revenues and expenses.
Understanding Revenue Streams
Identify and categorize all sources of money flowing into your business. This could include:
-
Sales of Goods/Services: The primary source for most businesses.
-
Subscription Fees: For recurring service models.
-
Advertising Revenue: If your business monetizes through ads.
-
Royalties: Income from licensing intellectual property.
-
Interest Income: From business savings or investments.

Differentiating Gross Revenue from Net Revenue
-
Gross Revenue: The total sales value before any deductions.
-
Net Revenue: Gross revenue minus sales returns, allowances, and discounts. This provides a more accurate picture of actual sales.
Cost of Goods Sold (COGS)
If your business sells physical products or directly related services, calculate your COGS. This includes:
-
Direct Materials: Raw materials used in production.
-
Direct Labor: Wages for employees directly involved in production.
-
Manufacturing Overheads: Costs like factory rent, utilities, and equipment depreciation directly tied to production.
-
For Service Businesses: COGS might include direct costs of service delivery.
Calculating Gross Profit
Subtract the Cost of Goods Sold from your Net Revenue.
Gross Profit = Net Revenue – COGS
This figure indicates the profitability of your core product or service before considering operational overheads.
Identifying Operating Expenses
These are the costs incurred in running your business, not directly tied to production. Categorize them carefully:
-
Salaries and Wages (Non-Production): Administrative staff, sales teams.
-
Rent and Utilities: Office space, electricity, internet.
-
Marketing and Advertising: Campaigns, website maintenance.
-
Administrative Expenses: Office supplies, legal fees, accounting services.
-
Depreciation and Amortization: Cost of assets spread over their useful life.
-
Insurance: Business insurance premiums.
Determining Operating Profit (EBIT)
Subtract your total Operating Expenses from your Gross Profit.
Operating Profit = Gross Profit – Operating Expenses
This shows how much profit your business generates from its primary operations.
Accounting for Non-Operating Income/Expenses and Taxes
-
Non-Operating Income: Interest earned on business savings, gains from selling non-core assets.
-
Non-Operating Expenses: Interest paid on business loans, losses from selling assets.
-
Income Tax Expense: The amount of tax your business owes on its profits.
Arriving at Net Income (Net Profit)
Finally, incorporate non-operating items and subtract taxes from your Operating Profit.
Net Income = Operating Profit + Non-Operating Income – Non-Operating Expenses – Income Tax Expense
This is the ultimate measure of your business’s profitability, reflecting what’s left after all costs and taxes.
Tools and Strategies for Accurate Income Tracking
Effective income calculation relies heavily on consistent tracking and smart use of available resources.
Spreadsheets (Excel/Google Sheets)
For personal or small business use, spreadsheets offer incredible flexibility.
-
Customization: Create tailored categories for income and expenses.
-
Templates: Utilize pre-built templates for budgeting and financial tracking.
-
Formulas: Leverage formulas to automate calculations, sum totals, and even visualize trends.
-
Example: Set up columns for Date, Source, Description, Gross Amount, Deductions, and Net Amount.
Financial Software and Apps
Many digital tools can streamline income tracking and financial management.
-
Personal Finance Apps (e.g., Mint, YNAB): Link to your bank accounts, categorize transactions automatically, and provide budgeting insights.
-
Small Business Accounting Software (e.g., QuickBooks, Xero, Wave Accounting): Designed for businesses to manage invoices, track expenses, reconcile bank accounts, and generate financial reports like Profit & Loss statements.
-
Payment Processors (e.g., PayPal, Stripe): Offer reporting features for transactions processed through their platforms.
Professional Assistance
Don’t hesitate to seek expert help when needed.
-
Accountants/Bookkeepers: Indispensable for complex business structures, tax planning, and ensuring compliance. They can help set up robust tracking systems.
-
Financial Advisors: Can integrate income calculation into broader financial planning, including investments, retirement, and wealth management.
Regular Review and Reconciliation
-
Monthly/Quarterly Checks: Regularly compare your records with bank statements and other financial documents to catch discrepancies and ensure accuracy.
-
Set Reminders: Schedule dedicated time to update your income and expense logs.
Record Keeping Best Practices
-
Digital vs. Physical: While digital records are convenient, keep organized physical copies of important documents like pay stubs, tax forms, and key invoices.
-
Cloud Storage: Utilize services like Google Drive or Dropbox for secure backup of digital records.
-
Duration: Keep tax-related records for at least 3-7 years, or longer for certain business documents.
The Importance of Accurate Income Calculation
Beyond mere compliance, precise income calculation underpins critical financial decisions and long-term success.
Informed Budgeting and Spending Decisions
Knowing your true net income allows you to create a realistic budget, allocate funds effectively, and prevent overspending. For businesses, understanding profit margins guides pricing strategies and cost control.
Effective Financial Planning
Accurate income figures are essential for:
-
Saving Goals: Setting achievable targets for emergency funds, down payments, or major purchases.
-
Retirement Planning: Determining how much you can contribute to retirement accounts.
-
Debt Repayment: Structuring a feasible plan to pay off loans and credit card balances.
-
Investment Decisions: Understanding your capacity to invest and grow wealth.
Tax Compliance and Optimization
Calculating income correctly is fundamental for accurate tax filing, avoiding penalties, and identifying potential deductions or credits. For businesses, it’s crucial for understanding tax liabilities and planning for future tax obligations.
Business Performance Evaluation
For entrepreneurs, accurate income statements provide vital insights into profitability, cash flow, and operational efficiency. This data enables strategic decisions, resource allocation, and can be critical for securing funding or attracting investors.
Achieving Financial Goals
Whether personal or business-related, diligently calculating and tracking income provides a clear barometer of progress towards financial objectives. It highlights areas for improvement, celebrates successes, and offers the necessary data to pivot when circumstances change.

Conclusion
Calculating your income is not a one-time task but an ongoing process fundamental to financial empowerment. By systematically tracking all income sources, understanding the distinction between gross and net figures, and leveraging appropriate tools, you gain unparalleled clarity over your financial landscape. This clarity translates into better budgeting, smarter financial planning, robust tax preparation, and ultimately, the confidence to achieve your personal and business financial aspirations. Embrace this essential practice, and take control of your financial future.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.