
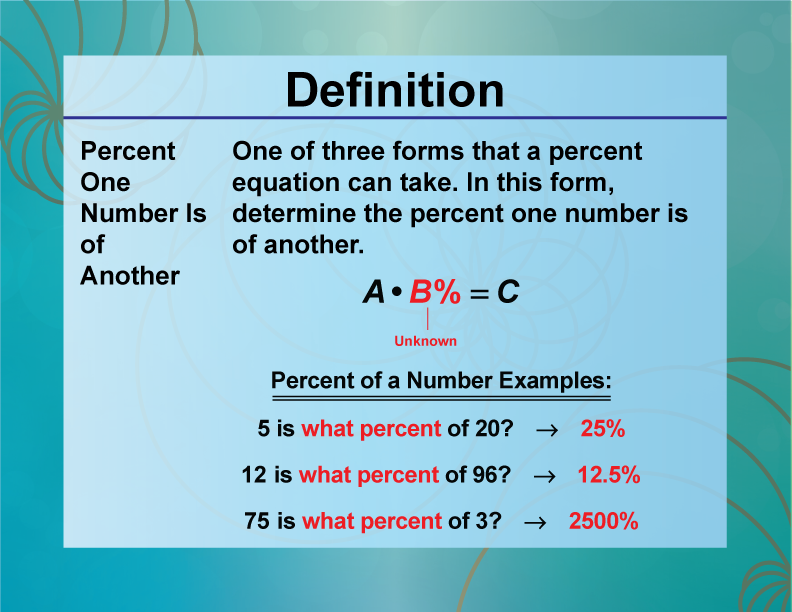
In the intricate world of finance, few questions are as fundamental, as universally applicable, and yet as profoundly insightful as “what percent of what is what.” This seemingly simple query underpins nearly every major decision we make, whether we’re managing personal finances, steering a multi-million-dollar corporation, or strategizing investment portfolios. It is the bedrock of financial literacy, a powerful lens through which we analyze allocation, efficiency, risk, and opportunity. From budgeting household expenses to evaluating market share, from calculating profit margins to diversifying investment assets, percentages provide the crucial framework for understanding relationships and making informed choices. They transform raw numbers into actionable insights, revealing the proportional significance of every financial component and guiding us toward optimal resource deployment.
The Ubiquitous Language of Financial Allocation
Percentages are more than just mathematical symbols; they are the universal dialect of financial communication, translating complex economic realities into easily digestible proportions. They allow for an apples-to-apples comparison across vastly different scales, making it possible to compare a small startup’s marketing spend with that of a multinational corporation, or to assess the relative impact of various expenses within a personal budget. Without this proportional understanding, financial data would remain a daunting array of figures, devoid of context and actionable meaning.
Understanding Proportionality in Personal Finance
For individuals, the “what percent of what is what” question is a daily companion. How much of your income goes towards housing? What percentage is allocated to savings, debt repayment, or discretionary spending? These are not merely academic exercises but vital calculations that define financial health and dictate future possibilities. A high percentage of income consumed by fixed expenses might signal a need for adjustment, while a low percentage dedicated to savings could jeopardize long-term goals. It’s the percentages that reveal the true pressure points and areas of opportunity in a personal financial landscape, allowing for strategic planning and course correction.
Business Decisions Driven by Percentage Metrics
In the corporate world, the stakes are amplified. Businesses constantly dissect their operations through a percentage lens. What percent of revenue is net profit? What percentage of the budget is spent on research and development? What percentage of market share does a particular product command? These metrics are not just indicators; they are drivers of strategic decisions, informing everything from pricing models and operational efficiencies to market expansion and shareholder value. A declining profit margin percentage, for instance, might trigger a comprehensive review of costs, while a growing market share percentage could justify further investment in a product line.
The Psychological Impact of Financial Ratios
Beyond the purely analytical, percentages also carry a significant psychological weight. Knowing that a certain percentage of your income is automatically diverted to savings can instill a sense of security and control. Conversely, seeing a large percentage of your earnings go towards high-interest debt can be a powerful motivator for change. In business, communicating growth or efficiency in percentage terms can galvanize teams and inspire confidence among investors. The clarity and simplicity of a percentage ratio often resonate more deeply than absolute figures, making complex financial situations more approachable and fostering a sense of measurable progress.
Decoding Your Personal Financial Blueprint
For individuals aiming for financial freedom and security, understanding the proportional breakdown of their finances is paramount. It’s about more than just knowing how much money comes in and goes out; it’s about strategically allocating every dollar to align with short-term needs and long-term aspirations. The answers to “what percent of what is what” form the bedrock of a sustainable personal financial blueprint.
The 50/30/20 Rule and Its Variations
Perhaps the most widely cited guideline for personal budgeting is the 50/30/20 rule. This framework suggests allocating 50% of your after-tax income to needs (housing, utilities, groceries, transportation), 30% to wants (dining out, entertainment, hobbies), and 20% to savings and debt repayment. While not a rigid dictum, this percentage-based rule offers an excellent starting point for understanding how your income should ideally be distributed. For those with high debt, a 50/20/30 rule (50% needs, 20% wants, 30% debt/savings) might be more appropriate, showcasing the flexibility and adaptability of percentage-based budgeting to individual circumstances and priorities. The beauty lies in its simplicity and the immediate insight it provides into whether current spending patterns are sustainable or require adjustment.
Debt-to-Income Ratios: A Health Check
Another critical percentage for personal finance is the debt-to-income (DTI) ratio. This metric calculates the percentage of your gross monthly income that goes towards servicing monthly debt payments (credit cards, loans, mortgage). Lenders widely use DTI to assess your capacity to manage additional debt. A DTI below 36% is generally considered healthy, indicating a strong ability to handle financial obligations. A higher percentage, particularly above 43%, can signal financial strain and make it challenging to secure new loans or even lead to increased financial stress. Regularly monitoring your DTI helps you gauge your financial leverage and make informed decisions about taking on new debt. It’s a powerful “what percent of what is what” question that directly impacts your financial flexibility and creditworthiness.
Savings and Investment Contributions: Building Wealth Incrementally
When it comes to building wealth, consistency in savings and investments is often more impactful than the sheer amount saved in any single instance. Here, percentages play a critical role in setting achievable, sustainable goals. What percent of each paycheck are you dedicating to your retirement fund? What percentage goes into an emergency savings account? Financial advisors often recommend saving at least 10-15% of your income for retirement, and ideally more, especially if starting later in life. By framing these contributions as percentages, individuals can scale their efforts with income fluctuations and maintain a disciplined approach to wealth accumulation, ensuring that a portion of every dollar earned is working towards their future.
The Emergency Fund Threshold: What Percent Is Enough?
An emergency fund is a non-negotiable component of financial security, acting as a buffer against unforeseen expenses like job loss, medical emergencies, or significant home repairs. The critical question here is: what percentage of your monthly expenses should your emergency fund cover? The commonly cited advice is to have 3 to 6 months’ worth of essential living expenses saved. For those with unstable income or dependents, this percentage might stretch to 9-12 months. Calculating this percentage gives a clear, actionable target, transforming an abstract goal into a concrete financial milestone. It allows you to understand precisely “what percent of your yearly spending you need to have liquid” to weather potential storms without resorting to high-interest debt.
Strategic Financial Management in Business
For businesses, the question “what percent of what is what” moves from personal sustainability to competitive advantage, operational efficiency, and long-term growth. Every line item on an income statement and balance sheet becomes a percentage metric, scrutinized for performance, potential, and strategic implications.
Revenue Allocation: Profit Margins and Operational Efficiency
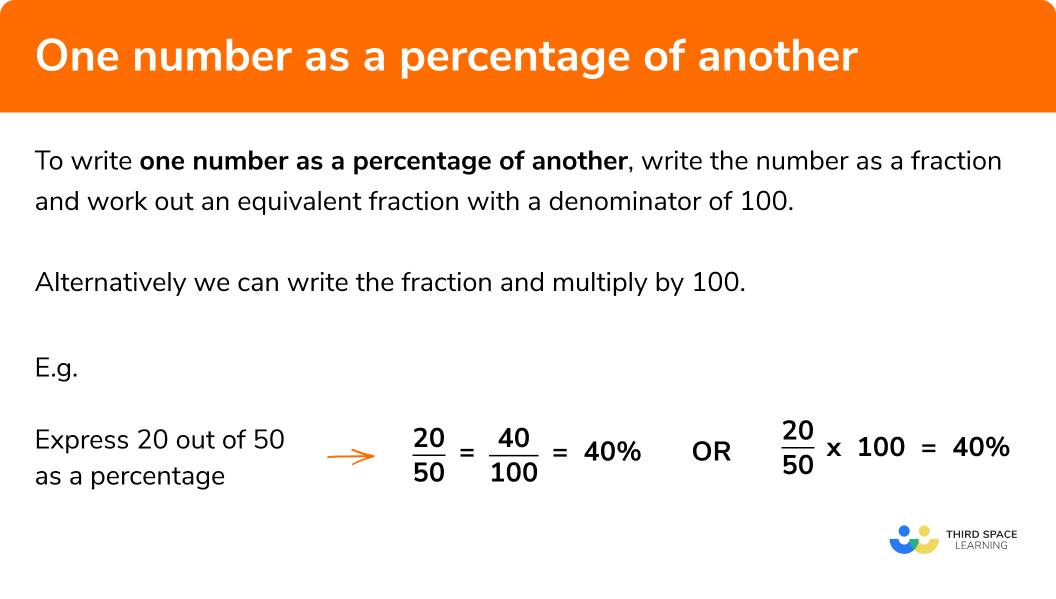
At the heart of any business’s financial health are its profit margins. What percent of total revenue translates into gross profit? What percent ultimately becomes net profit after all expenses? These percentages are critical indicators of operational efficiency, pricing strategy, and cost control. A declining gross profit margin might signal issues with product pricing or manufacturing costs, while a shrinking net profit margin could point to escalating operating expenses. Regularly asking “what percent of revenue is consumed by X expense?” helps businesses identify bottlenecks, streamline operations, and enhance their bottom line. It’s a constant quest to maximize the percentage of revenue that converts into wealth for stakeholders.
Marketing and R&D Spend: Investing in Growth
Investing in growth is vital, but how much is enough, and how much is too much? This is where understanding the percentage of revenue allocated to marketing and research & development becomes crucial. What percent of your revenue should be reinvested into brand building and customer acquisition? What percent should fuel innovation and product development? These percentages vary widely by industry, company size, and growth stage. A high-growth tech startup might allocate a significantly larger percentage of revenue to R&D than a mature utility company. Strategic managers use these percentages to balance current profitability with future potential, ensuring that investments are aligned with long-term strategic objectives and don’t disproportionately erode profits or stunt innovation.
Customer Acquisition Cost (CAC) vs. Customer Lifetime Value (CLTV): A Critical Balance
For businesses, particularly those in subscription or service models, understanding the relationship between Customer Acquisition Cost (CAC) and Customer Lifetime Value (CLTV) is paramount. The critical question becomes: “What percent of your CLTV is represented by your CAC?” Ideally, CLTV should be significantly higher than CAC – often a ratio of 3:1 or more is desired. If CAC is a large percentage of CLTV, it indicates an unsustainable business model where the cost of acquiring a customer eats up too much of the revenue they will generate. Analyzing these percentages helps businesses refine their marketing strategies, optimize customer onboarding, and improve retention efforts to ensure a healthy, profitable customer base over time.
Employee Compensation as a Percentage of Revenue
Human capital is often a company’s largest expense and greatest asset. Examining employee compensation as a percentage of revenue or total operating expenses provides valuable insight into a company’s labor efficiency and cost structure. What percent of your revenue is spent on salaries, benefits, and payroll taxes? This percentage can fluctuate based on industry, automation levels, and business model. A service-based business, for example, will naturally have a higher percentage of revenue dedicated to labor than a highly automated manufacturing plant. Monitoring this percentage helps companies manage their workforce costs, assess productivity, and make strategic decisions regarding hiring, outsourcing, and compensation packages.
Investing with a Percentage Mindset
In the realm of investing, percentages are the language of risk, return, and diversification. They allow investors to quantify their exposure, measure performance, and construct portfolios that align with their financial goals and risk tolerance.
Asset Allocation: Diversification Strategies by Percentage
One of the foundational principles of investing is asset allocation, which involves distributing your investment capital among various asset classes, such as stocks, bonds, real estate, and commodities. The crucial question is: “What percent of your portfolio should be allocated to each asset class?” This strategic decision is driven by factors like age, risk tolerance, and investment horizon. A younger investor might allocate a higher percentage to growth-oriented stocks (e.g., 80% stocks, 20% bonds), while someone nearing retirement might opt for a more conservative approach with a larger percentage in bonds (e.g., 40% stocks, 60% bonds). Understanding and adhering to these percentage allocations is key to managing risk and optimizing returns over the long term.
Risk Tolerance and Portfolio Weighting
Your personal risk tolerance directly influences the “what percent of what is what” in your investment portfolio. An aggressive investor might be comfortable with a higher percentage of their portfolio in volatile assets, seeking higher potential returns, even at the cost of greater short-term fluctuations. A conservative investor, conversely, will opt for a larger percentage in less volatile assets, prioritizing capital preservation over aggressive growth. Portfolio weighting, expressed as percentages, is the practical application of risk tolerance, ensuring that the composition of investments reflects an individual’s comfort level with market ups and downs. This alignment is crucial for sticking to an investment plan during periods of market stress.
Understanding Returns: Compound Interest and Percentage Growth
The power of compound interest, often hailed as the “eighth wonder of the world,” is fundamentally understood through percentages. A consistent annual percentage return, even a seemingly modest one, can lead to substantial wealth accumulation over time. The question “what percent annual return can I expect?” is central to financial planning and goal setting. Furthermore, understanding the percentage growth of individual investments or an overall portfolio is essential for evaluating performance against benchmarks and personal objectives. These percentage returns, when viewed over extended periods, vividly illustrate how initial small percentages can balloon into significant sums due to the compounding effect.
Rebalancing Your Portfolio: Maintaining Desired Percentages
Over time, market fluctuations can cause your portfolio’s asset allocation to drift from its original target percentages. For example, a strong bull market might cause your stock allocation to grow to 85% instead of your desired 70%. Rebalancing is the act of adjusting your portfolio back to your target percentages by selling assets that have grown disproportionately and buying those that have underperformed. This process involves asking “what percent deviation is acceptable before I rebalance?” and “what assets need to be adjusted by what percentage?” Regular rebalancing ensures that your portfolio’s risk profile remains consistent with your long-term strategy and prevents any single asset class from dominating your holdings unexpectedly.
Beyond the Numbers: The “Why” Behind the Percentages
While percentages provide the quantitative framework for financial decision-making, their true power lies in the qualitative context they reveal. The question “what percent of what is what” ultimately leads to deeper inquiries about goals, values, and adaptability.
Goal-Oriented Percentage Planning
Every percentage allocation, whether for personal budgeting, business investment, or portfolio diversification, should be rooted in a specific goal. Why are you saving 20% of your income? Is it for a down payment, retirement, or a child’s education? Why is 15% of your revenue dedicated to R&D? Is it to gain market share, innovate a new product, or improve efficiency? The “what” of the percentage gains its full meaning from the “why” behind it. This goal-oriented approach transforms abstract numbers into tangible steps towards achieving aspirations, providing purpose and motivation for financial discipline.
Adapting Percentages to Life Stages and Market Conditions
Financial plans are not static; they must evolve. The ideal “what percent of what is what” shifts dramatically across different life stages. A young professional’s savings percentage might be focused on building an emergency fund, while an established professional might shift a higher percentage towards aggressive growth investments. Similarly, businesses adapt their spending percentages based on market cycles – increasing marketing spend during growth phases or cutting operational percentages during downturns. The flexibility to adjust these percentages in response to changing personal circumstances, economic climates, and market conditions is a hallmark of intelligent financial management. It underscores the dynamic nature of finance, where static adherence can be as detrimental as a lack of planning.

The Power of Small Percentages Over Time
Finally, the enduring lesson from “what percent of what is what” is often found in the cumulative impact of small percentages. A seemingly insignificant 1% increase in an annual investment return, consistently applied over decades, can result in hundreds of thousands of dollars more in wealth. A 1% reduction in operating costs, year after year, can significantly boost a company’s profitability. Similarly, saving just 1% more of your income each year, or reducing discretionary spending by a small percentage, can lead to substantial financial gains. These marginal improvements, often overlooked in the pursuit of large leaps, are the silent engines of financial success. They highlight that understanding and optimizing even the smallest percentages can unlock immense long-term value, transforming aspirations into realities through consistent, proportional effort.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.